China’s 2030 ICT Plan focus: 50G-PON, AI Traffic and Satellite–Terrestrial Networks
Executive Summary:
China’s Ministry of Industry and Information Technology (MIIT) has issued its 15th Five-Year Plan for the Development of the Information and Communication Industry, setting a 2030 target for a next-generation communications infrastructure with nationwide coverage, high performance, and a foundation for the sector’s broader modernization by 2035.
The plan sets several quantitative goals for 2030:
-
Information and communications industry revenue of RMB 4.1 trillion.
-
Deployment of 50 5G/5G-Advanced base stations per 10,000 people.
-
95% penetration of 5G/5G-Advanced users.
-
320 million fixed-broadband subscribers with access rates of at least 1 Gbit/s.
-
Intelligent-computing capacity of 9,800 EFLOPS.
- Digital economy: Core industries aim to reach 12.5% of GDP by 2030.
- Networks: Build next-generation communications with full coverage and leading performance.
- Security: Enhance domain coordination and practical network/data security.
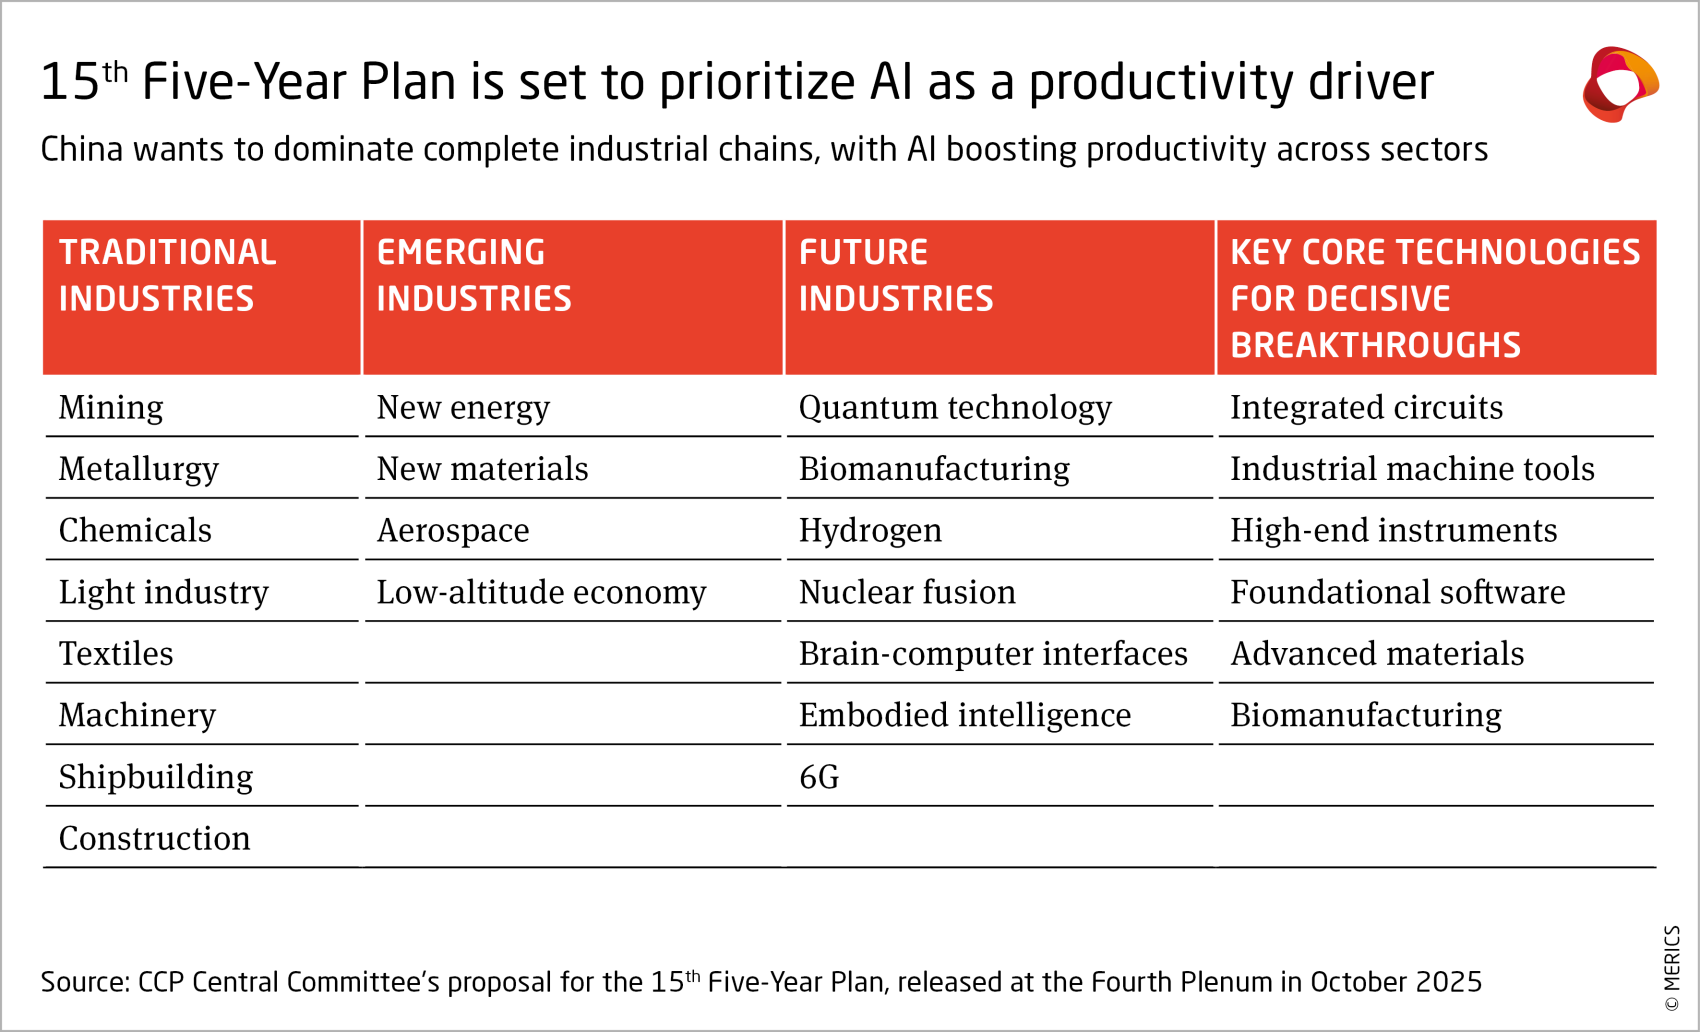
The strategy also emphasizes tighter satellite–terrestrial integration. MIIT calls for coordinated construction of satellite–terrestrial interconnection centers and development of direct-to-device satellite services and satellite IoT applications. It further identifies 6G base stations and terminals as development priorities, alongside stronger standards frameworks for optical communications, computing networks, and quantum communications.
China’s 50G-PON push:
The plan’s broader infrastructure objectives reinforce China’s interest in 50G-PON as a successor to today’s 10G-class PON deployments. ITU-T G.9804 defines 50G-PON as a higher-speed passive optical network supporting 50 Gbit/s downstream capacity and at least 12.5 Gbit/s upstream capacity. The technology is intended to extend fiber-access performance for residential, enterprise, cloud, industrial, and mobile-network backhaul use cases.
While operators and equipment suppliers in most markets remain in early trial and evaluation phases, China has accumulated practical deployment experience through 136 10 Gbit/s network pilots conducted last year. Those trials evaluated 50G-PON ultra-broadband access, fiber-to-the-room (FTTR) integrated with Wi-Fi 7, and optical-AI integration, as well as cloud-computing and cloud-gaming applications.
At the China International Optoelectronic Expo in Shenzhen, industry participants argued that China’s supply chain is technically positioned for larger-scale 50G-PON deployment. The remaining constraints are primarily economic and operational: system cost, terminal economics, and power consumption remain material barriers to broad commercial rollout.
AI changes the access-network equation:
Unlike several earlier optical-access upgrade cycles, 50G-PON is being positioned against a more immediate traffic and workload driver: AI. Zhang Dechao, deputy head of basic-network research at the China Mobile Research Institute, said token-based AI workloads are reshaping optical-network traffic patterns, particularly by increasing upstream and more symmetric bandwidth requirements.
Historically, consumer broadband traffic was strongly downstream-weighted. AI inference, distributed data processing, edge-cloud interaction, enterprise collaboration, and high-resolution interactive applications are changing that profile. Zhang said uplink traffic now represents roughly 40% to 50% of total traffic in some network scenarios, making symmetrical bandwidth an increasingly important design requirement. He also cited projections that AI inference could account for 25% of total network traffic by 2035 and contribute to more than 63% growth in aggregate traffic demand.
That shift matters for PON evolution. A network designed primarily for high downstream residential consumption is not necessarily optimized for AI-era workloads that require sustained upstream capacity, lower latency, more predictable performance, and closer integration between access, edge, cloud, and data-center infrastructure.
Supply-chain conflict:
AI is also creating an uncomfortable contradiction for the optical-access sector. The same AI investment cycle that is expanding demand for higher-capacity access and transport networks is redirecting capital, component capacity, and engineering resources toward AI data centers, high-speed Ethernet optics, accelerator interconnects, and cloud infrastructure.
Lin Tao, marketing director at component supplier Accelink Technologies, warned that this concentration of investment could constrain PON-specific R&D and production capacity. Suppliers may find higher near-term returns in AI-related optical modules and interconnect products than in access-network components, particularly where 50G-PON volumes remain uncertain.
The implication is straightforward: technical readiness alone will not determine the timing of 50G-PON deployment. Operators must establish sufficiently compelling service, enterprise, mobile backhaul, and AI-connectivity business cases to justify investment amid competition for optical components, manufacturing capacity, and capex.
Chinese optical suppliers nevertheless contend that core 50G-PON technology—including ASICs, optical modules, and devices—has reached maturity. Large-scale shipments of standardized customer-premises terminals are expected to begin next year, potentially marking the transition from pilots to broader commercial deployment.
References:
http://finance.people.com.cn/n1/2026/0909/c1004-40794989.html
https://www.lightreading.com/optical-networking/china-targets-1m-50g-pon-ports-by-2030
China Mobile and Huawei Turn High-Speed Railway 5G-A into a Premium Service
Key take-aways: “16th Smart City and Intelligent Economy Expo” for Huawei, Alibaba & China’s three state backed carriers
China vs U.S.: Race to Generate Power for AI Data Centers as Electricity Demand Soars
Analysis & Economic Implications of AI adoption in China
China’s telecom industry rapid growth in 2025 eludes Nokia and Ericsson as sales collapse
China’s open source AI models to capture a larger share of 2026 global AI market
China ITU filing to put ~200K satellites in low earth orbit while FCC authorizes 7.5K additional Starlink LEO satellites
China gaining on U.S. in AI technology arms race- silicon, models and research