U.S. Fixed Broadband Market Outlook: Satellite, FWA, Fiber and Cable Face Changing Competitive Dynamics
Disclaimer: ChatGPT was used extensively to assist with research, technical and market analysis, and drafting of this article. The author independently conducted additional research and incorporated source material and quotations. He reviewed, edited, and fact-checked the final content and is 100% responsible for its accuracy.
Introduction:
The U.S. fixed broadband market is entering a period of significant competitive change as low-Earth-orbit (LEO) satellite broadband expands, cellular fixed wireless access (FWA) growth moderates, fiber-to-the-premises (FTTP) deployment continues, and cable operators face increasing subscriber losses. These developments are changing the competitive relationships among four principal broadband access technologies: satellite, cellular FWA, fiber and hybrid fiber-coaxial (HFC) cable.
A November 19, 2026 report by New Street Research, summarized in Light Reading’s article, Satellite Broadband to Capture Most Market Share from FWA – Report, provides an interesting assessment of these trends. The analysts expect satellite broadband to expand the addressable broadband market while capturing subscribers from existing providers, with cellular FWA experiencing the greatest competitive impact. “Satellite can do things wireline hasn’t been able to, and the take-up demonstrates there is latent demand out there we haven’t incorporated previously,” states the report authored by New Street Research analysts David Barden, Vikash Harlalka and Ryan Smith.
The report also raises a broader question: as fiber’s traditional source of subscriber growth diminishes and satellite capacity expands, will satellite broadband eventually take a meaningful share of the fiber market as well?
Satellite Broadband: Starlink Drives Market Expansion
LEO satellite broadband, led by SpaceX’s Starlink, is becoming an increasingly significant participant in the U.S. residential broadband market. Unlike traditional geostationary satellite systems, LEO constellations operate much closer to Earth, substantially reducing propagation delay and enabling more competitive broadband services.
New Street Research forecasts that Starlink’s U.S. subscriber base will increase from approximately 3 million at year-end 2025 to approximately 10 million by 2030. Its analysis also forecasts that satellite broadband will capture approximately 7% of the existing broadband market in its terminal state. “Satellite net adds have accelerated in recent quarters as Starlink has become a more viable product. We expect Satellite net adds to remain at current levels for the foreseeable future,” the analysts wrote.
The analysts expect satellite net additions to remain around current levels for the foreseeable future. They also believe satellite is expanding the overall addressable market by serving customers whose broadband requirements have not been adequately met by terrestrial providers.
New Street estimates that U.S. residential broadband subscriber growth reached 2.2% year-over-year in Q3 2026. Without satellite broadband additions, growth would have been only 1.6%.
These figures demonstrate that satellite is contributing to overall broadband market expansion, not simply redistributing existing subscribers among competing providers.
Nevertheless, satellite broadband is also a competitive substitute for terrestrial fixed broadband. Starlink can attract customers from cable, cellular FWA and, potentially, fiber providers, depending on local availability, service performance and pricing.
Its competitive position will depend heavily on continued constellation expansion, satellite throughput, spectrum availability, ground infrastructure, terminal costs and the economics of serving increasingly dense geographic markets.
Cellular FWA: Growth Continues but Subscriber Additions May Slow:
Cellular FWA has become an important alternative to wireline broadband, particularly in locations where fiber is unavailable or where customers prefer lower-cost service and simpler installation. T-Mobile, Verizon and AT&T have been the principal U.S. cellular FWA providers. Their services use 4G LTE and 5G radio access networks to deliver broadband connectivity to fixed residential locations.
According to New Street Research, combined FWA net additions have remained in the 3.6–3.9 million range annually over the past four years. However, the analysts report that additions are beginning to slow at T-Mobile and Verizon, with AT&T also believed to have reached peak net additions. New Street expects FWA subscriber growth to decelerate further for all three operators.
“FWA net adds have been in the 3.6-3.9MM range for the past 4 years. Both T-Mobile and Verizon adds have started to slow down with the latter showing this more acutely. AT&T continues to grow but we estimate it has reached peak net adds. We expect FWA net adds to continue slowing down for all 3 carriers from here,” states the report.
The belief that FWA is slowing runs counter to the narrative coming from some executives: “…on FWA, look, we’re seeing continued very strong momentum. So deceleration, et cetera, is not where we are,” T-Mobile CEO Srini Gopalan told analysts on the operator’s Q3 earnings call.
This forecast is significant because cellular FWA has benefited from relatively rapid deployment, attractive introductory pricing and the ability to use existing cellular network infrastructure. However, FWA capacity is constrained by available spectrum, radio resources, cell-site density and competing mobile traffic. As subscriber penetration increases, operators must balance fixed broadband demand against mobile network performance. Additional spectrum, network densification and improved radio efficiency can expand capacity, but they require further investment.
Satellite broadband could therefore become a stronger competitor to cellular FWA, particularly in rural and lower-density markets where terrestrial cellular capacity or coverage is constrained.
It remains important to distinguish subscriber additions from market share. Slower FWA net additions do not necessarily mean that FWA subscribers will migrate directly to satellite; some customers may instead choose fiber or cable, while satellite may also attract previously unserved households.
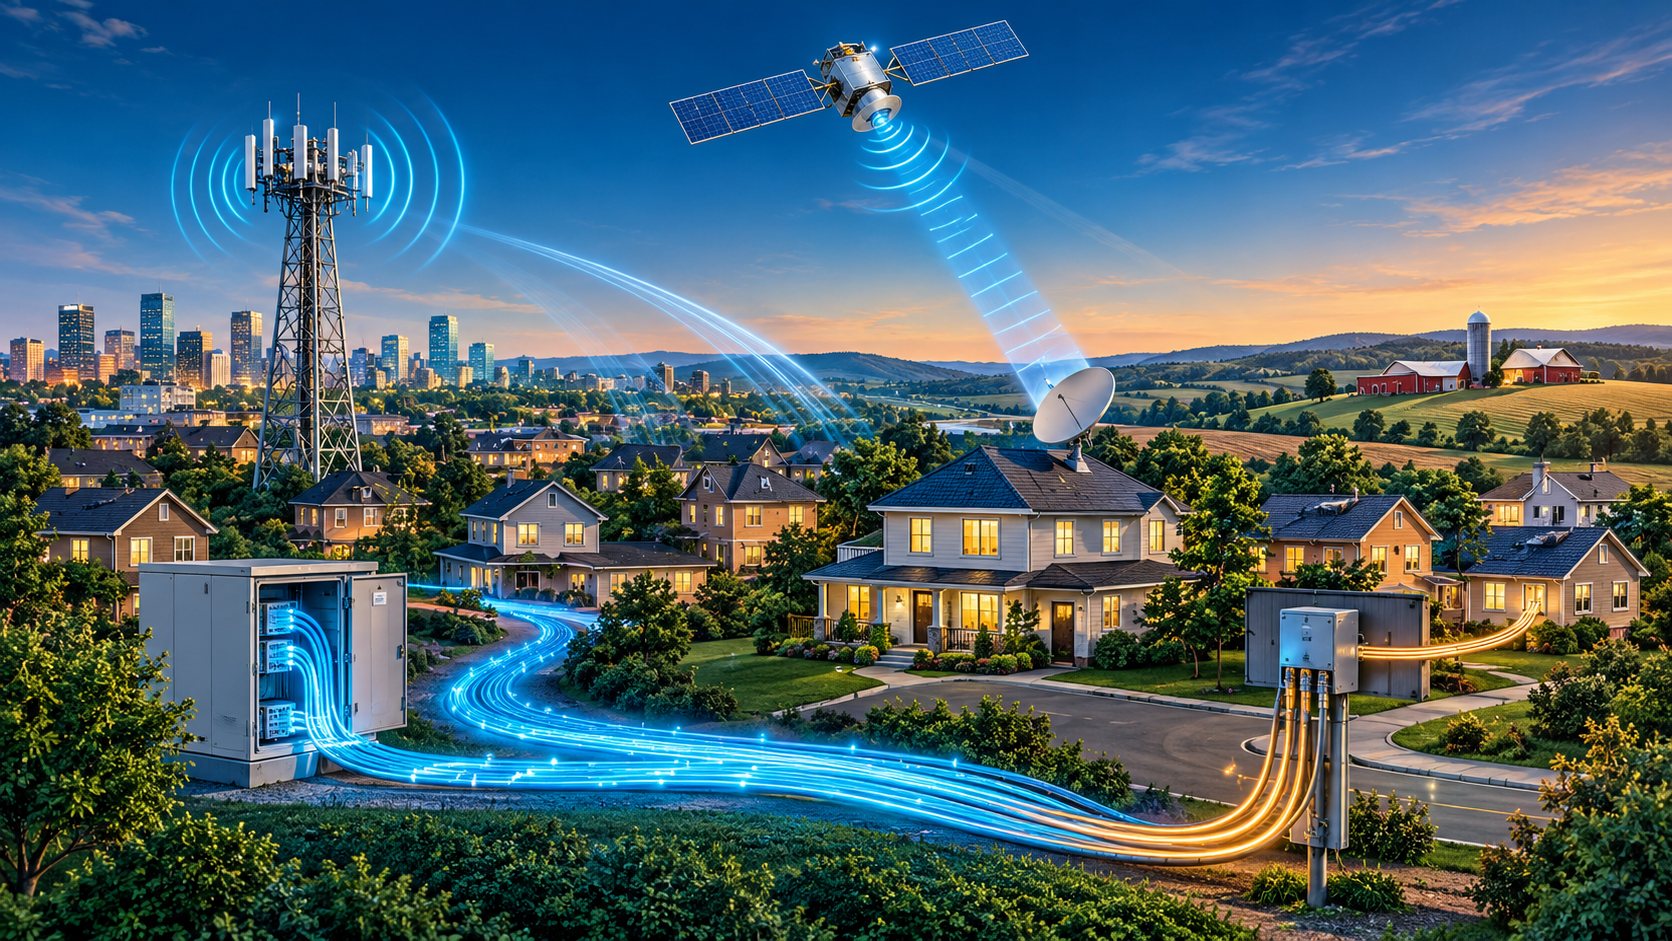
The evolving U.S. fixed broadband landscape: LEO satellite, cellular fixed wireless access (FWA), fiber-to-the-premises (FTTP), and hybrid fiber-coaxial (HFC) networks compete to deliver residential broadband connectivity. Image generated by ChatGPT.
Fiber Broadband: Strong Growth Through 2028, Followed by Deceleration:
Fiber broadband remains the strongest long-term fixed broadband access technology in terms of capacity, scalability, symmetrical bandwidth potential and low latency.
U.S. fiber deployments continue to expand, with telecommunications operators, independent fiber providers and municipal or cooperative networks extending FTTP coverage.
New Street Research expects fiber net additions to reach approximately 3 million in 2026, followed by 2.8–2.9 million annually in 2027 and 2028.
However, the analysts expect fiber net additions to decelerate thereafter as the pool of remaining DSL subscribers available for conversion approaches exhaustion.
They forecast that DSL subscriptions will be nearly zero by 2029. This removes an important source of relatively straightforward fiber subscriber growth: migrating customers from an operator’s legacy copper network to its own fiber infrastructure. As DSL converts to fiber decrease, the analysts also expect fiber net adds to reach a peak of 3 million in 2026 and remain in the 2.8 million-2.9 million range over the next two years “before decelerating thereafter,” according to the report. “We expect a deceleration in fiber net adds because DSL subs will be nearly zero by 2029 and an easy source of fiber net adds will disappear. Fiber operators will need to fight harder to find new subscribers,” the report said.
New Street says its long-term outlook does not expect satellite “to gain any share at the expense of fiber.” Consequently, fiber operators will increasingly need to compete for subscribers already served by cable, cellular FWA and other broadband providers. This represents an important change in the economics of fiber deployment and customer acquisition. Fiber providers will need to demonstrate sufficient advantages in bandwidth, reliability, latency and pricing to persuade customers to switch from existing broadband services.
Will Satellite Broadband Take Market Share From Fiber based Access?
New Street Research does not currently expect satellite broadband to gain market share at fiber’s expense. Instead, its forecast assigns the greatest competitive impact to cellular FWA.
That is a reasonable base-case assumption, particularly because fiber generally provides substantially higher capacity, lower latency, more consistent performance and better economics per delivered bit in densely populated markets.
However, it would be premature to conclude that satellite will not take market share from fiber.
LEO satellite broadband is not limited to customers who lack terrestrial broadband access. Customers in some suburban and exurban locations may consider satellite a viable alternative even when fiber is available, depending on service pricing, performance, installation costs and individual broadband requirements.
Furthermore, improvements in satellite capacity, spectral efficiency and terminal economics could expand the number of locations where satellite can compete effectively.
The geographic distribution of fiber and satellite capacity will be particularly important. Satellite can provide meaningful competition in lower-density markets where fiber deployment and maintenance are expensive, even if its nationwide share of broadband subscribers remains relatively modest.
The distinction is between aggregate market-share forecasts and actual competitive substitution in individual markets. Satellite can take customers from fiber in selected geographic markets without producing a significant change in nationwide fiber market share.
Accordingly, New Street’s forecast that satellite will primarily take share from FWA should be viewed as a projection rather than an established competitive outcome.
Cable Broadband: DOCSIS Upgrades Amid Subscriber Losses:
Cable operators continue to face competitive pressure from fiber, cellular FWA and satellite broadband. New Street Research reports that cable continues to lose market share, reflecting the increasing availability of alternative broadband technologies. Nevertheless, HFC networks remain important broadband infrastructure. Cable operators are investing in DOCSIS upgrades, including DOCSIS 4.0, to increase downstream and upstream capacity and extend the competitive life of their existing coaxial access networks.
DOCSIS 4.0 supports full-duplex and extended-spectrum approaches, with the potential for multi-gigabit downstream and upstream service capabilities. These upgrades allow cable operators to compete more effectively with fiber without replacing their entire HFC access infrastructure. However, technological improvements alone will not necessarily reverse subscriber losses. Cable operators must also address pricing, customer satisfaction, service reliability and the competitive advantages of fiber and wireless alternatives.
Satellite broadband could add another source of competitive pressure, especially in areas where cable is the principal terrestrial broadband alternative.
Technical and Economic Factors Determine the Competitive Outcome:
The four broadband technologies have different performance characteristics, deployment economics and capacity constraints.
| Technology | Principal advantages | Principal constraints |
|---|---|---|
| Fiber (FTTP) | High capacity, symmetrical bandwidth, low latency, scalability and reliability | High initial construction costs, permitting and deployment time |
| Cellular FWA | Rapid deployment, existing cellular infrastructure, flexible service offerings | Spectrum, cell capacity, radio conditions and mobile traffic competition |
| LEO satellite | Broad geographic coverage, rapid availability and service to remote locations | Shared satellite capacity, spectrum, terminal costs, latency and congestion |
| Cable (HFC) | Extensive existing footprint, high downstream capacity and DOCSIS upgrade path | Shared coaxial capacity, upstream limitations and competition from fiber |
An important technical consideration for LEO satellite broadband is that coverage does not necessarily equal unlimited service capacity.
Satellite throughput is shared among users within a service area. Actual performance depends on constellation size, satellite capacity, available spectrum, gateway infrastructure, spot-beam allocation and subscriber density.
Consequently, expanding the number of satellites does not automatically translate into proportional growth in the number of subscribers that can receive consistently high broadband speeds.
A technical assessment of LEO broadband prepared by Cartesian for the Fiber Broadband Association highlights these capacity and performance constraints. Its modeling, based primarily on public information available through November 2024 with minor updates in early 2025, estimates substantial limitations on the number of U.S. locations that Starlink could serve at the FCC’s 100 Mbps download/20 Mbps upload benchmark.
Those estimates should not be treated as current operational measurements or definitive forecasts, particularly given subsequent constellation developments. However, the underlying engineering constraint remains important: satellite capacity must be shared geographically, and concentrated demand can degrade user performance.
Fiber does not face the same last-mile radio spectrum and shared satellite beam constraints. This gives fiber a substantial long-term advantage in high-density markets and locations with significant bandwidth demand.
U.S. Fixed Broadband Market Outlook: 2027–2030:
The competitive outlook can be summarized as follows:
Satellite broadband: Continued expansion, led by Starlink, with increasing competition against terrestrial broadband providers. New Street expects satellite to capture approximately 7% of the existing broadband market in its terminal state, primarily at the expense of cellular FWA.
Cellular FWA: Continued subscriber growth, but with decelerating net additions as operators encounter capacity and market-penetration constraints. Additional spectrum and network investment could extend its growth potential.
Fiber: Strong subscriber additions through 2028, followed by slower growth as DSL conversion opportunities diminish. Fiber operators will increasingly compete for customers already served by other broadband technologies.
Cable/HFC: Continued market-share pressure from fiber, FWA and satellite, despite ongoing DOCSIS upgrades intended to improve network capacity and competitiveness.
The following table summarizes the directional outlook, rather than providing independently verified subscriber forecasts.
| Technology | 2027–2028 outlook | Longer-term direction |
|---|---|---|
| Satellite | Strong growth | Increasing competitive presence |
| Cellular FWA | Growth decelerates | Dependent on spectrum and capacity expansion |
| Fiber | Approximately 2.8–2.9M annual net adds | Deceleration after 2028 |
| Cable/HFC | Continued market-share pressure | DOCSIS upgrades support competitiveness |
| DSL/Copper | Continued subscriber decline | Nearly zero subscribers projected by 2029 |
Conclusions:
The U.S. fixed broadband market is becoming increasingly competitive as satellite, cellular FWA, fiber and cable technologies converge in their ability to deliver residential broadband services.
New Street Research’s forecast that satellite will take most of its market share from cellular FWA is plausible, particularly given the expected slowdown in FWA subscriber additions. However, the assumption that satellite will not take market share from fiber deserves further scrutiny.
Fiber should retain a substantial advantage in densely populated markets because of its capacity, low latency, reliability and scalability. But those advantages do not make it immune to competitive substitution in rural, exurban and selected suburban markets.
At the same time, the approaching exhaustion of DSL-to-fiber conversions will require fiber operators to compete more aggressively for subscribers already served by other broadband providers.
Ultimately, the competitive outcome will depend on the economics of delivering broadband capacity to individual geographic markets, rather than simply comparing nationwide subscriber totals.
The most important question is not whether satellite will replace fiber nationally, but how much of the addressable broadband market satellite can economically serve—and which terrestrial broadband providers will lose subscribers as that capability expands.
……………………………………………………………………………………………………………………………………………………………..
References:
https://fiberbroadband.org/resources/technical-assessment-of-leo-satellite-broadband/
https://www2.itif.org/2025-broadband-convergence.pdf
https://www.sec.gov/Archives/edgar/data/1181412/000162828026052515/earningsreleaseq22608042.htm
New Street Research study: Cable broadband will continue its decline, but total broadband access subscribers will increase
ABI Research joins the chorus: 5G FWA is a competitive alternative to wired broadband access
BroadbandNow Research: Best & Worst States for Broadband Access
U.S. broadband subscriber growth slowed in 1Q-2024 after net adds in 2023
FTTH was ~60% of France fixed broadband market in Q1-2023