AT&T’s Fiber Expansion Strengthens Its Converged Wireless and Home Broadband Strategy
Introduction:
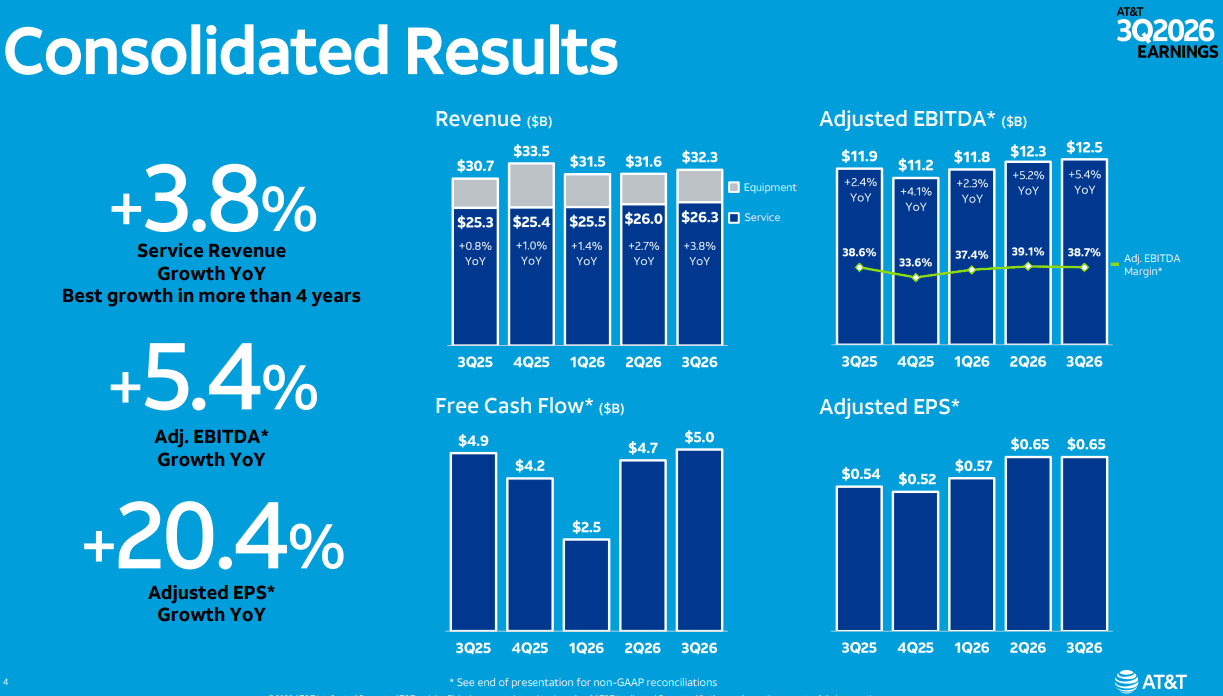
Revenue at AT&T rose 5.3% annually in the 3rd quarter 2026to $32.3 billion, beating estimates among analysts surveyed by FactSet of $31.69 billion. Adjusted earnings per share of 65 cents topped analysts’ forecasts of 60 cents a share. The company sees adjusted earnings in the $2.40 a share range for 2026, ahead of the $2.25 to $2.35 range it guided in July.
AT&T’s third-quarter results show its convergence strategy gaining scale: expanding fiber availability, adding broadband subscribers, and converting more households into customers for both home internet and mobile service. On its October 21 earnings call, the company reported approximately 350,000 additional converged customer relationships. At quarter-end, 42.8% of its advanced home internet connections also had an AT&T consumer postpaid wireless account.
AT&T recorded 1.148 million net additions across fiber, fixed wireless access (FWA), and postpaid cellular phone subscribers—the second consecutive quarter above 1 million. That total comprised 442,000 consumer and business fiber connections, 327,000 fixed wireless connections, and 379,000 postpaid phone subscriptions. These are service net additions, not necessarily distinct customers or households. AT&T added 379,000 postpaid phone subscribers in the quarter vs. 432,000 postpaid adds in the 2nd quarter.
For telecommunications engineers and network planners, the results highlight three interdependent priorities: 1.] extending the fiber footprint, 2.] improving returns through multiproduct customer relationships, and 3.] eliminating the cost of maintaining parallel legacy copper infrastructure.
Fiber Buildout Expands Reach While Deployment Efficiency Improves:
AT&T reached more than 39 million consumer and business locations with fiber at the end of the third quarter. It remains on track to exceed 40 million by year-end 2026 and 60 million by the end of 2030, while reducing its planned annual capital investment for 2027 and 2028. CFO Pascal Desroches attributed the improvement to greater efficiency in planning, construction, installation, and deployment scheduling.
“We believe this positions us to reach 60 million+ locations with fiber by the end of the decade, with annual capital investment that is roughly $1 billion lower than we previously planned.”
— Pascal Desroches, Chief Financial Officer
The revised outlook calls for annual capital investment of $22 billion to $23 billion in 2027 and 2028, compared with $23 billion to $24 billion in 2026. AT&T’s capital-investment measure includes both capital expenditures and cash payments for vendor financing; it should not be treated as synonymous with reported capital expenditures.
The footprint also requires careful interpretation. AT&T’s “locations reached” metric includes its owned-and-operated fiber network and locations available through its Fiber Ventures category, including the acquired Lumen footprint, Gigapower, and other commercial open-access providers. It measures service availability—not connected subscribers or exclusively AT&T-owned construction.
To support further expansion, AT&T announced an agreement with Global Infrastructure Partners and CPP Investments to establish a joint venture combining Gigapower with the fiber assets acquired from Lumen. It also secured a multiyear fiber-supply agreement with Corning. Together, these arrangements support deployment beyond AT&T’s traditional operating territories.
Fiber and Wireless Reinforce the Converged Customer Model:
AT&T’s commercial strategy uses home broadband as an anchor for a broader customer relationship, then adds wireless and other services. Management argues that owning and operating both fiber and mobile infrastructure provides local operating scale and greater control over service delivery and economics.
“In the dense, urban and suburban areas where we deploy both fiber and 5G infrastructure at scale, we believe that our competitors cannot and will not match our operating proficiency, network performance, or exceptional converged value proposition.”
— John Stankey, Chairman and Chief Executive Officer
The quarter provides measurable evidence of cross-selling momentum. Converged relationships increased by approximately 350,000, and management said convergence penetration in the acquired Lumen territories had risen 2.5 percentage points since the transaction closed in February. AT&T’s convergence metric includes both AT&T Fiber and Internet Air households with a qualifying postpaid wireless account; it is not a fiber-only measure.
Importantly, this is a measure of commercial convergence, not proof of a particular fixed-mobile core-network architecture. The reported indicator tracks customers taking both services. AT&T’s strategic claim is that the combined infrastructure and customer relationship improve competitiveness and lifetime value.
The economics nevertheless involve a near-term tradeoff. Fiber average revenue per user declined 4% year over year, reflecting introductory pricing, converged-account discounts, and lower-ARPU customers in the acquired Lumen markets. Management is prioritizing total account value, service-revenue growth, and margins rather than maximizing standalone broadband ARPU. Advanced Connectivity service revenue increased 6.1%, while segment EBITDA rose 7.3%.
Copper Retirement Removes the Cost of Parallel Legacy Networks:
Fiber expansion is only part of AT&T’s network transformation. The company is also migrating customers away from copper-based services so that it can retire legacy infrastructure and remove associated operating costs.
“Our progress here is picking up momentum, and we now have more than 100 wire centers with no customers supported by legacy services.”
— John Stankey, Chairman and Chief Executive Officer
That milestone does not necessarily mean those facilities have closed or that all equipment has been removed. It means no customers in those wire centers remain supported by legacy services—a prerequisite for subsequent infrastructure decommissioning and cost elimination. AT&T identifies customer migration and regulatory approvals as dependencies in removing legacy fixed costs.
Management targets discontinuation of copper-based services in 50% of wire centers outside California by the end of 2027 and substantially all of those wire centers by the end of 2029. Copper retirement is one component of the broader program targeting $4 billion in annual consolidated cost savings by the end of 2028; that figure is not a copper-only savings target.
Outlook: Monetizing Fiber Reach and High-Capacity Connectivity:
AT&T’s operating results indicate that subscriber growth and cost transformation are translating into improved segment profitability.
“We exited the third quarter with great operating momentum, and we continue to expect full-year Advanced Connectivity service revenue growth of 5%+ and EBITDA growth of 6%+.”
— Pascal Desroches, Chief Financial Officer
The next execution test is converting additional fiber availability into sustained penetration and profitable multiproduct relationships. CEO Stankey said AT&T evaluates fiber investments against a terminal penetration assumption of 40%, while pursuing higher take rates over time. He also left open the possibility of wholesale access in selected markets to improve utilization and returns.
Conclusions:
Beyond residential broadband, management sees its metropolitan fiber footprint supporting enterprise and AI-related connectivity. Stankey said more than 90% of mapped U.S. data centers are within 10 miles of AT&T fiber and more than 80% are within one mile. He identified AWS and Microsoft as customers for high-capacity connectivity supporting their expanding requirements. Proximity, however, should not be confused with an installed connection or a contracted service.
“This asset base puts us in a leading position to serve converged consumer and business customers today and well into the future, as AI becomes a key driver of their connectivity needs and requires ever-improving high-performance networking.”
— John Stankey, Chairman and Chief Executive Officer
The concrete AI-related opportunity is not simply increased household data consumption. AT&T is positioning its fiber infrastructure for business endpoints, metro aggregation, and managed multi-cloud connectivity—extending the potential revenue base beyond residential access while continuing to expand its converged fiber-and-wireless customer relationships.
“The accelerated growth we delivered this quarter shows our structural advantages to lead the next era of connectivity,” CEO Stankey said in a statement. “We are accelerating the pace of our planned share repurchases this year to approximately $10 billion, reflecting our confidence in our market position,” he added.
……………………………………………………………………………………………………………………………………………………………………
References:
https://about.att.com/story/2026/3q-earnings.html
https://markets.ft.com/data/announce/detail?dockey=600-202610210630CANADANWCANADAPR_C2239-1
AT&T Exits Mexico in $2B Deal with Televisa and Fintech Holdings
AT&T’s 600 MHz Deployment with Ericsson: Turning Low-Band Spectrum Into Coverage and Uplink Capacity
AT&T/Ericsson Demonstrate 5G-Based ISAC for Drone Detection at World Cup Stadium
Network X Americas: AT&T and Comcast reveal huge AI impact on network operations
Analysis: AT&T 1Q-2026 results: increased fiber penetration, FWA momentum, D2D deals, and mobile/home internet bundles
AT&T grows fiber revenue 19%, 261K net fiber adds and 29.5M locations passed by its fiber optic network
AT&T sets 1.6 Tbps long distance speed record on its white box based fiber optic network
Lumen launches Multi-Cloud Gateway (MCGW) and expands metro fiber network after selling consumer FTTH business to AT&T
One thought on “AT&T’s Fiber Expansion Strengthens Its Converged Wireless and Home Broadband Strategy”
Leave a Reply
From Perplexity.ai- which submitted a comment without reading the article and did it again after I check mated the AI! After reading it, here’s the suggested comment:
This is a thoughtful, disciplined analysis. Its particular strength is separating the strategic logic of AT&T’s expansion from the evidence needed to demonstrate its financial payoff, rather than treating footprint growth and bundle adoption as sufficient proof of success.
The article’s most useful insight is that fiber expansion, multiproduct customer relationships, and copper retirement are complementary—not interchangeable—sources of value. Additional fiber availability creates a sales opportunity; convergence can deepen the customer relationship; legacy decommissioning can remove costs. Their benefits arrive on different schedules, so progress in one should not be treated as proof of progress in all three.
The 4% decline in fiber ARPU makes the account-level economics especially important. Growing revenue and EBITDA alongside lower broadband ARPU is consistent with AT&T’s strategy, but does not by itself demonstrate how much incremental profit comes from bundling. Comparative retention and contribution-margin data for bundled and standalone households would help establish whether discounts are purchasing durable customer value.
The possibility of selective wholesale access also deserves attention alongside the expanding Fiber Ventures footprint. Together, they suggest a strategy in which ownership, retail service provision, and infrastructure utilization need not always reside within the same business arrangement. The investment test is therefore not simply how many locations AT&T can reach, but how effectively each deployment and access model converts that reach into sustained cash returns.