Fixed Wireless Access (FWA)
Verizon and Ericsson Advance AI-Native RAN Operations with Nationwide EIC Rollout
Executive Summary:
Verizon and Ericsson are expanding their longstanding collaboration to introduce AI-native automation into Radio Access Network (RAN) operations. The companies plan a nationwide deployment of Ericsson Intelligent Controller (EIC) [1.], a software platform for running RAN applications (rApps) co-developed by Ericsson and Verizon.
The initiative is intended to improve mobile network performance, automate network optimization and advance Verizon’s longer-term objective of achieving Level 4 (L4) network autonomy. The companies have demonstrated EIC and associated rApps in a live network environment, using AI-based cell shaping and traffic steering to optimize Massive Multiple-Input Multiple-Output (Massive MIMO) antenna operation.
According to Ericsson and Verizon, field deployment of the Advanced Antenna System (AAS) Cell Shaper rApp produced throughput gains of up to 8.9% in downlink data radio bearer (DRB) throughput and up to 8% in uplink user equipment (UE) throughput.
The collaboration has three principal objectives:
- RAN autonomy: Building on open, programmable interfaces to automate network operations and optimization.
- AI-based optimization: Deploying rApps to improve radio performance, traffic distribution and operational efficiency.
- Operator-controlled innovation: Enabling Verizon to develop and deploy its own rApps alongside Ericsson applications rather than relying exclusively on vendor-developed network optimization software.
Note 1. “Ericsson Intelligent Controller (EIC) is a new product part of the Ericsson Intelligent Automation Platform (EIAP) which is Ericsson’s Open RAN aligned service management and orchestration (SMO) solution. EIAP provides multivendor RAN automation, management, and orchestration of Cloud and Open Radio access networks. Ericsson differentiator is the extended support to purpose-built radio access networks.” SOURCE: Ericsson
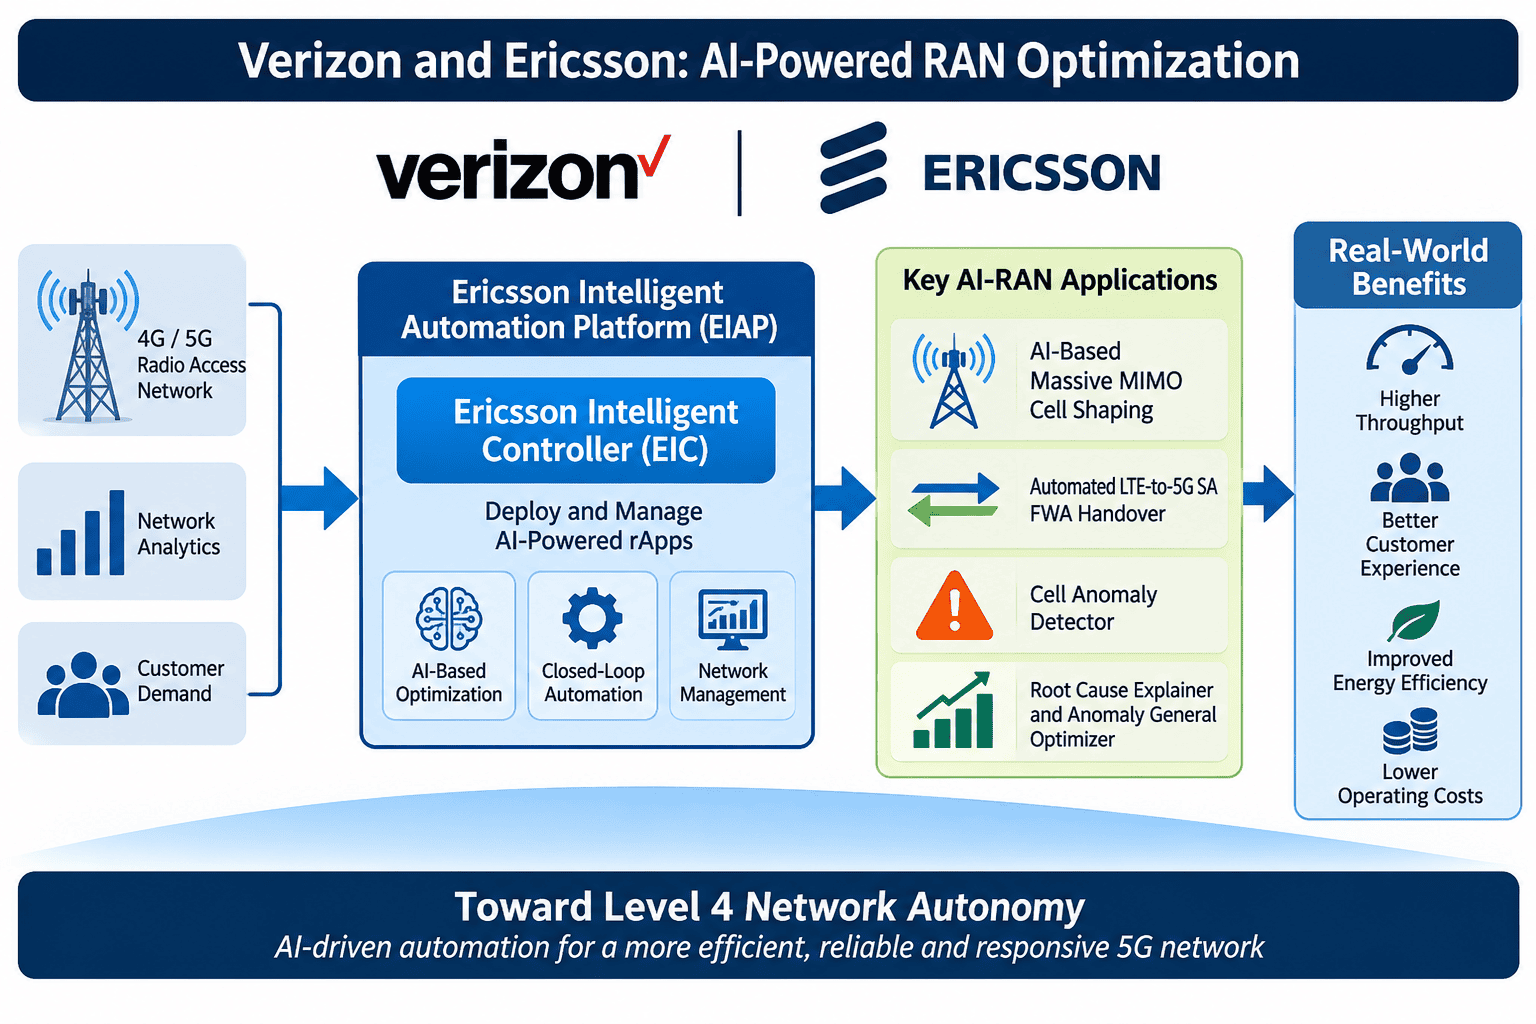
Image generated by ChatGPT which was also used for research and writing this article.
………………………………………………………………………………………………………………………………………………………………………………………………………….
AI-Native RAN Automation and Massive MIMO Optimization:
A central component of the collaboration is the application of AI to Massive MIMO antenna systems. Massive MIMO uses large antenna arrays at 5G base stations to transmit and receive multiple spatially separated data streams. Through beamforming, the radio system can concentrate transmitted energy toward individual users or groups of users rather than radiating power uniformly in all directions. Combined with spatial multiplexing, this can improve spectral efficiency, increase network capacity and extend coverage.
However, optimizing Massive MIMO performance across a large mobile network is complex. Radio propagation conditions, user locations, traffic demand, interference, antenna configuration and mobility patterns change continuously. A configuration that improves performance in one cell or at a particular time of day may not be optimal under different network conditions.
Ericsson’s Advanced Antenna System (AAS) Cell Shaper rApp applies AI-based optimization to antenna operation and cell coverage. Its purpose is to adjust radio coverage characteristics and traffic distribution to better match changing network conditions.
Cell shaping and traffic steering are particularly important in densely populated areas where neighboring cells may experience significantly different traffic loads. Intelligent adjustment of antenna coverage and traffic distribution can help balance demand, reduce congestion and improve utilization of available radio resources.
These reported throughput improvements demonstrate the potential to improve the utilization of existing radio infrastructure through software-based optimization. However, the companies have not disclosed the geographic scope, test duration, baseline conditions, radio configurations or measurement methodology underlying the maximum reported gains. Consequently, the results should not be interpreted as nationwide average improvements or as evidence that equivalent gains will be achieved throughout Verizon’s network.
Automating Fixed Wireless Access Mobility:
Another application demonstrated by Verizon addresses mobility problems affecting Fixed Wireless Access (FWA) devices transitioning between LTE and 5G Standalone (SA) networks.
Verizon implemented a Connected Mode Inter-Radio Access Technology (Inter-RAT) handover methodology to address failed transitions from LTE to 5G SA for FWA devices. According to the companies, the automated methodology eliminates the need for manual intervention when these handover failures occur.
In this scenario, Inter-RAT mobility involves transitioning a device between different radio access technologies: 4G LTE and 5G NR.
Conventional 5G Non-Standalone (NSA) deployments use an LTE anchor, with 5G NR added as a secondary radio access technology (5G NSA is essentially 4G LTE with a 5GNR RAN interface). It relies on the LTE/Evolved Packet Core (EPC) architecture. By contrast, 5G SA uses a 5G NR radio access network connected directly to a 5G Core (5GC), without requiring an LTE anchor. Only 5G SA can realize the 5G features and functions defined by 3GPP’s 5G Architecture specs.
–>A successful 5G NSA to 5G SA transition therefore requires appropriate mobility procedures, network configuration and coordination between the LTE and 5G SA environments.
This application illustrates how programmable RAN automation can address specific operational problems through targeted software applications rather than relying exclusively on conventional network-management procedures and manual troubleshooting. It also demonstrates that RAN automation can address mobility management, network reliability and operational efficiency beyond radio-throughput optimization
Expanding the rApp Ecosystem and Network Autonomy:
Verizon plans to deploy EIC nationally during 2026 and introduce additional rApps developed both internally and by Ericsson. Planned applications include:
- Cell Anomaly Detector: Identifies abnormal cell behavior that may affect network performance.
- Root Cause Explainer: Helps identify potential causes of network problems, supporting more efficient troubleshooting and service restoration.
- Anomaly General Optimizer: Supports network optimization in response to detected anomalies.
The names of these applications suggest different stages of the network assurance and optimization lifecycle. Anomaly detection identifies departures from expected network behavior; root-cause analysis helps determine potential underlying problems; and optimization applications can initiate corrective actions.
When integrated into a coordinated automation framework, these functions can form a closed-loop operational process:
- Monitor: Collect network performance measurements, alarms, configuration data and other operational information.
- Detect: Identify abnormal conditions or performance degradation using analytics and AI/ML models.
- Diagnose: Analyze network data to identify potential root causes.
- Optimize: Determine appropriate corrective actions based on network policies and operating constraints.
- Actuate: Apply approved changes to network configuration or operating parameters.
- Verify: Monitor subsequent network performance to determine whether the corrective action achieved the intended result.
This feedback process is fundamental to autonomous network operations. It allows network optimization to continue without requiring human intervention for every individual adjustment, while retaining appropriate operator oversight and control.
The companies have not provided detailed technical specifications for the three planned applications, so their precise functions, interfaces and degrees of automation remain to be established.
Ericsson Intelligent Automation Platform and Open Interfaces:
The Ericsson Intelligent Controller is a component of the Ericsson Intelligent Automation Platform (EIAP), Ericsson’s open network management and automation environment designed for multivendor, multi-technology networks.
Key platform capabilities include:
- Support for 4G and 5G Radio Access Networks and Ericsson core networks.
- A Non-RT RIC execution environment for rApps.
- Standardized interfaces, including the O-RAN R1 interface.
- Application lifecycle management and deployment.
- Network data collection, analytics and AI/ML workflow capabilities.
- Policy management and coordination of network optimization activities.
- Controlled application execution and network actuation.
Ericsson reports that EIAP’s ecosystem includes more than 100 available rApps from over 100 ecosystem members, supporting different stages of the network automation lifecycle.
The ability for Verizon to develop its own rApps is particularly important. It gives the operator an opportunity to create network-specific optimization functions based on its traffic patterns, spectrum holdings, radio configurations and operational requirements, while also drawing on Ericsson’s broader rApp ecosystem.
An open application environment can reduce dependence on proprietary, vendor-specific optimization functions and encourage third-party application development.
However, the availability of open interfaces and a broad rApp ecosystem should not be confused with a fully interoperable multivendor RAN deployment. Ericsson describes EIAP as supporting multivendor networks, including purpose-built radio access networks. This means that deploying EIC and using O-RAN-aligned interfaces does not, by itself, establish that Verizon is replacing its existing RAN equipment with Open RAN equipment.
The distinction is important: Open RAN automation interfaces and an open application ecosystem can be deployed alongside conventional, purpose-built radio infrastructure.
The Road to Level 4 Network Autonomy:
The nationwide EIC deployment represents another step toward more autonomous RAN operations. Verizon’s longer-term objective is Level 4 (L4) network autonomy, in which network functions can perform increasingly complex operational and optimization tasks with minimal human intervention.
The TM Forum’s Autonomous Networks framework defines L4 as a highly autonomous network capability involving predictive decision-making and active closed-loop management of service-driven and customer-experience-driven networks, supported by AI modeling and continuous learning.
Achieving L4 autonomy requires considerably more than deploying AI applications. It requires:
- Reliable, continuous monitoring of network conditions and performance.
- Accurate AI/ML models that can operate under changing radio and traffic conditions.
- Closed-loop optimization with measurable performance verification.
- Coordination among multiple applications and network domains.
- Policy enforcement, security controls and safeguards against unintended network changes.
- Appropriate human oversight and the ability to intervene when automated actions produce unexpected results.
The distinction between automating individual network functions and achieving end-to-end autonomous network operations is important. An operator may successfully deploy several autonomous rApps without having achieved L4 autonomy across its entire RAN.
Furthermore, the TM Forum autonomy levels are assessed against specific network scenarios and operational domains. Achieving L4 in one function or network domain does not necessarily mean that the entire nationwide network has reached that level.
Verizon’s collaboration with Ericsson provides a programmable software platform and an expanding application ecosystem to support that transition. Whether it ultimately delivers L4 autonomy will depend on the scope of automation, the reliability of closed-loop operations and the integration of these capabilities across Verizon’s network.
Conclusions:
The Verizon-Ericsson initiative illustrates how AI-based software applications, open interfaces and closed-loop control can improve the operation of existing 4G and 5G radio access networks. The reported Massive MIMO throughput improvements and automated LTE-to-5G SA FWA handover demonstrate practical applications beyond AI experimentation. The EIC deployment also provides Verizon with a platform for developing proprietary rApps while leveraging Ericsson’s broader application ecosystem.
The larger challenge will be scaling these capabilities across a nationwide network while maintaining interoperability, reliability, security and measurable improvements in customer experience and network economics. Ultimately, the success of AI-native RAN automation should be judged by sustained improvements in network performance, spectral efficiency, energy consumption and operating costs—not simply by the number of AI applications deployed.
……………………………………………………………………………………………
References:
Verizon and Ericsson Partner to Transform AI-Native Autonomous Networks — November 3, 2026
https://www.ericsson.com/en/portfolio/cross-portfolio/rapp-directory
Autonomous Networks Mission and Levels Taxonomy — TM Forum
About Ericsson Intelligent Controller
About Ericsson Intelligent Automation Platform
AI-RAN and Agentic AI get real: Ericsson, Nokia, Verizon & other operators enter into a new network automation era
Private 5G’s Business Model Shifts: Ericsson’s Move Signals a Market Reset
Ericsson signs MoU’s with Murata and Sumitomo to progress next-gen mobile network infrastructure
4.8 GHz to 4.9 GHz frequency band uses & Verizon Wireless experimental license for testing ISAC with Ericsson
Ericsson leads SK Telecom AI RAN vs. NVIDIA’s GPU centric AI RAN Alliance
Dell’Oro: Private Wireless Revenue Growth Prospects and Challenges
What Might Qualify as an Equivalent Replacement for a Copper Based Telephone Landline?
Introduction:
Retiring a copper telephone network is not simply a change of transmission medium. A migration can change where power is supplied, how calls are established, how connected equipment communicates, and which components must remain operational during an emergency. The objective is equivalence of required service outcomes—not replication of every characteristic of the old network. This article proposes a framework for evaluating those outcomes; it does not describe an existing regulatory certification.
The issue is becoming concrete for California customers. In its May 20, 2026 announcement, AT&T committed $19 billion through 2030 to fiber and wireless investment and described plans to discontinue specified copper-based services in parts of California on or after June 1, 2027. The company also committed to continued access to voice and 911 service. These are announced plans and commitments, not evidence of completed migration outcomes (more below).
The engineering question is more demanding than whether a replacement produces dial tone. A meaningful assessment should examine the functions customers depend on: conversational performance, emergency calling, power resilience, connected-device compatibility, and recovery after failure.
Separate the Access Connection From the Telephone Service:
“Fiber,” “wireless,” and “digital voice” describe different aspects of a communications system. A migration assessment should identify both the connection serving the premises and the voice service operating over it. Ofcom describes the UK’s digital-landline transition as a move to Voice over Internet Protocol, or VoIP. Its guidance also explains that customers do not necessarily need to purchase a high-speed broadband package to retain telephone service. The service requirement and the broadband product offered to a customer are therefore not interchangeable.
For evaluation purposes, three questions should remain separate:
-
Is the access connection operational?
-
Can the telephone service establish and receive calls?
-
Does the complete installation deliver the functions the customer requires?
An answer to the first question does not settle the other two. The proposed assessment should follow the entire service path, rather than treating the access technology as a proxy for telephone-service performance.
Power Resilience Requires a Complete Installation Test:
Traditional exchange-powered telephone service could keep a basic corded telephone working during a household power failure. Broadband-based voice introduces a different dependency: equipment at the customer’s premises needs electricity. Ofcom warns that digital landlines require a resilience solution if they are to remain usable during a power cut.
That distinction should not become a claim that copper service was immune to failure. It identifies a particular capability that a migration may need to preserve: telephone access when household mains power is unavailable.
The proposed acceptance procedure should identify every premises component required for calling and establish which backup arrangement powers each one. The test should then disconnect household mains power and verify the installed service—not merely inspect a battery indicator.
The resulting record should state:
-
Which equipment receives backup power.
-
Whether incoming and outgoing calls remain possible.
-
The tested standby duration and calling duty cycle.
-
The battery condition and replacement responsibility.
-
What happens when mains power returns.
A premises test also has a boundary: it cannot establish how long the provider’s external network will remain available during a regional outage. Installation-level results and provider-level resilience evidence should be documented separately.
Evaluate Conversation, Not Just Call Establishment:
The framework should distinguish successful call setup from an acceptable conversation.
A practical test program would evaluate incoming and outgoing calls under representative conditions, including simultaneous household broadband use where applicable. It should record call completion, audible interruptions, conversational delay, unexpected disconnections, and performance during relevant busy periods.
Rather than prescribing one universal numerical threshold, the migration plan should identify the applicable performance objectives and their basis. The acceptance record should make clear what was measured, under which conditions, and what constituted a passing result.
This approach avoids declaring one technology inherently superior. It asks whether the deployed service meets an explicit requirement.
Wireless Replacements Need Site-Specific Evidence:
AT&T’s California announcement identifies AT&T Phone – Advanced and AT&T Business Voice among its replacement offerings. The company states that these products provide battery backup and support existing telephones and various connected devices. Those statements should be presented as provider claims, not independent compatibility findings for every installation.about.att
The assessment should identify the product’s actual access arrangement rather than grouping every wireless-enabled voice product under one technical description.
For a wireless installation, the proposed checks include:
-
Reception at the equipment’s installed location.
-
Call completion and conversational performance at relevant busy periods.
-
Operation with household mains power disconnected.
-
Recovery after a loss of connectivity.
-
Successful operation of identified connected devices.
-
Any alternative communications path included in the service design.
A coverage statement and an installation acceptance result answer different questions. The proposed framework requires evidence about the installed service.
A Telephone Socket Does Not Establish Device Compatibility:
Some telephone connections support applications beyond conversation. Ofcom specifically advises customers to check equipment such as telecare devices and burglar alarms before switching to digital landlines.
The technical distinction is important: a signal that remains intelligible to a person may not be reproduced accurately enough for a machine. RFC 4733 explains that low-bit-rate speech codecs cannot be assumed to reproduce signaling tones reliably for automatic recognition. It defines mechanisms for transporting telephone events, including keypad digits, separately from ordinary encoded speech.
IETF RFC 4733 also discusses distinct approaches for fax, voice-band data, and modem communications, including T.38, V.152, and V.150.1. These mechanisms address different signal types; their existence is not a universal compatibility guarantee. Acceptance should therefore test the application’s complete transaction. For an alarm, that would mean verifying that the event reaches the monitoring center, identifies the correct account or location, and receives the expected acknowledgment. If migration requires replacing the connected device, the replacement should be evaluated as a new end-to-end system, including fault reporting and recovery—not simply described as preservation of the old telephone interface.
Emergency Access Needs Its Own Acceptance Plan:
The proposed framework should treat emergency access as a separate service requirement, with documented arrangements for:
-
Call origination and routing.
-
Service-location information.
-
Callback capability.
-
Operation during a premises power failure.
-
Recovery after equipment restart or access failure.
Verification should use provider-supported procedures and an agreed process with the relevant emergency organization. The framework does not call for unsolicited test calls to emergency numbers.
Any live emergency-calling validation must follow an agreed procedure with the provider and relevant emergency organization—not an unsolicited test call.
Network-side resilience also deserves attention. U.S. rules for covered 911 service providers address physical diversity, operational integrity, and monitoring. These obligations concern specified emergency-network facilities; they should not be confused with a blanket guarantee that every residential connection survives a prolonged outage. Evidence should also be matched to its scope. A successful installation test does not demonstrate regional emergency-network availability, just as a provider’s network-resilience statement does not demonstrate that a particular household has functioning backup power.
Fiber-based voice: access capacity is not the same as voice assurance:
ITU-T Recommendation G.9807.1 specifies XGS-PON, a 10-Gigabit-capable symmetric passive optical network. It is an access-network specification—not a certification that a particular retail telephone service reproduces every function of an analog line.
The voice service has additional layers. IETF RFC 3261 defines the Session Initiation Protocol, or SIP, used to establish, modify, and terminate sessions. Voice quality also depends on the media path and signal processing, not merely successful session establishment.rfc-editor+1
This creates an important distinction between three tests:
-
The access connection is operational.
-
A telephone call can be established.
-
The resulting conversation meets an acceptable quality and reliability target.
ITU-T G.114 addresses the effect of one-way transmission delay. G.107’s E-model provides a planning framework for considering transmission impairments, including delay and codec-related effects. ITU technical guidance also explains the jitter-buffer trade-off: buffering can accommodate variations in packet arrival time, but adds delay.itu+1
A proposed migration test should therefore measure conversational performance under realistic simultaneous broadband use—not only with an otherwise idle connection. The relevant evidence would include delay, packet loss, conversational interruptions, call completion, and performance at busy periods.
The objective is not to declare IP voice inherently inferior or superior. It is to establish whether the deployed service meets its stated performance objectives.
Fixed wireless (FWA): validate the installation, not just the coverage map:
Fixed-wireless voice is another migration option. AT&T’s May 2026 California announcement describes a transition toward fiber and wireless services, including AT&T Phone – Advanced and AT&T Business Voice. The company states that these products include battery backup and support existing telephones and various connected devices. Those are provider claims, not independent compatibility results for every installation.
For a fixed-wireless replacement, a useful acceptance procedure would examine:
-
Reception at the actual installed equipment location.
-
Call completion and audio quality during busy periods.
-
Battery operation with household electricity disconnected.
-
Recovery after loss of radio connectivity.
-
The behavior of connected alarms and monitoring equipment.
-
Whether an alternative communication path is available when the primary service fails.
These are proposed engineering checks, not assertions that a particular wireless product fails them.
“Wireless coverage exists” and “this installation provides an adequate replacement” are different propositions. The second requires site-specific evidence.
Legacy devices: intelligible speech does not prove compatibility:
An analog telephone line may carry more than conversation. Ofcom specifically warns customers to check equipment such as telecare devices and burglar alarms before migration.
The technical difficulty is that a signal understandable to a person is not necessarily reproduced accurately enough for a machine.
RFC 4733 explains why separate transport of telephone events is useful: low-bit-rate speech codecs cannot be assumed to reproduce signaling tones accurately enough for automatic recognition. The RFC defines RTP payload formats for DTMF digits and other telephone events and tones.
Relevant standards address different aspects of the problem:
| Standard | Relevance to migration |
|---|---|
| IETF RFC 4733 | Transport of DTMF digits and other telephone events and tones in RTP. |
| ITU-T T.38 | Specialized transport for Group 3 fax over IP networks. |
| ITU-T V.152 | Procedures for supporting voice-band data over IP networks. |
| ITU-T V.150.1 | Procedures for modem relay across IP networks. |
These mechanisms are distinct; they are not a universal compatibility guarantee. RFC 4733 identifies T.38, V.152, and V.150.1 as alternative approaches for particular signal types. ITU guidance further explains that voice-band data may require changes such as disabling voice-activity detection and comfort-noise generation during data transfer.itu+1
Consequently, an adapter with a familiar telephone socket should not be treated as proof that every attached application will work.
A stronger migration procedure would test the complete transaction: an alarm reaches its monitoring center, receives the expected acknowledgment, and reports the correct account or location. Where replacement equipment is needed, the installation should be evaluated as a new end-to-end system rather than as transparent preservation of the old interface.
Backup-power requirements: distinguish a minimum from a guarantee:
Ofcom’s guidance calls for a solution enabling access to emergency organizations for at least one hour during a premises power cut. Providers should offer the solution free to customers dependent on their landline for emergency calling. Ofcom’s consumer guidance recognizes that a mobile solution is appropriate only where there is usable mobile coverage.
The United States requires particular care when discussing historical rules. The retrieved text of 47 CFR §9.20 describes requirements to offer eight-hour and twenty-four-hour standby backup options for covered residential services that are not line-powered. However, that same text contains an explicit September 1, 2025 sunset provision. It should not be cited without qualification as an ongoing October 2026 requirement. Even as an engineering benchmark, standby duration is not identical to continuous talk time, network availability, or guaranteed operation throughout a regional emergency. A replacement-service specification should state the assumed duty cycle, battery condition, maintenance responsibility, and equipment included in the backup arrangement.
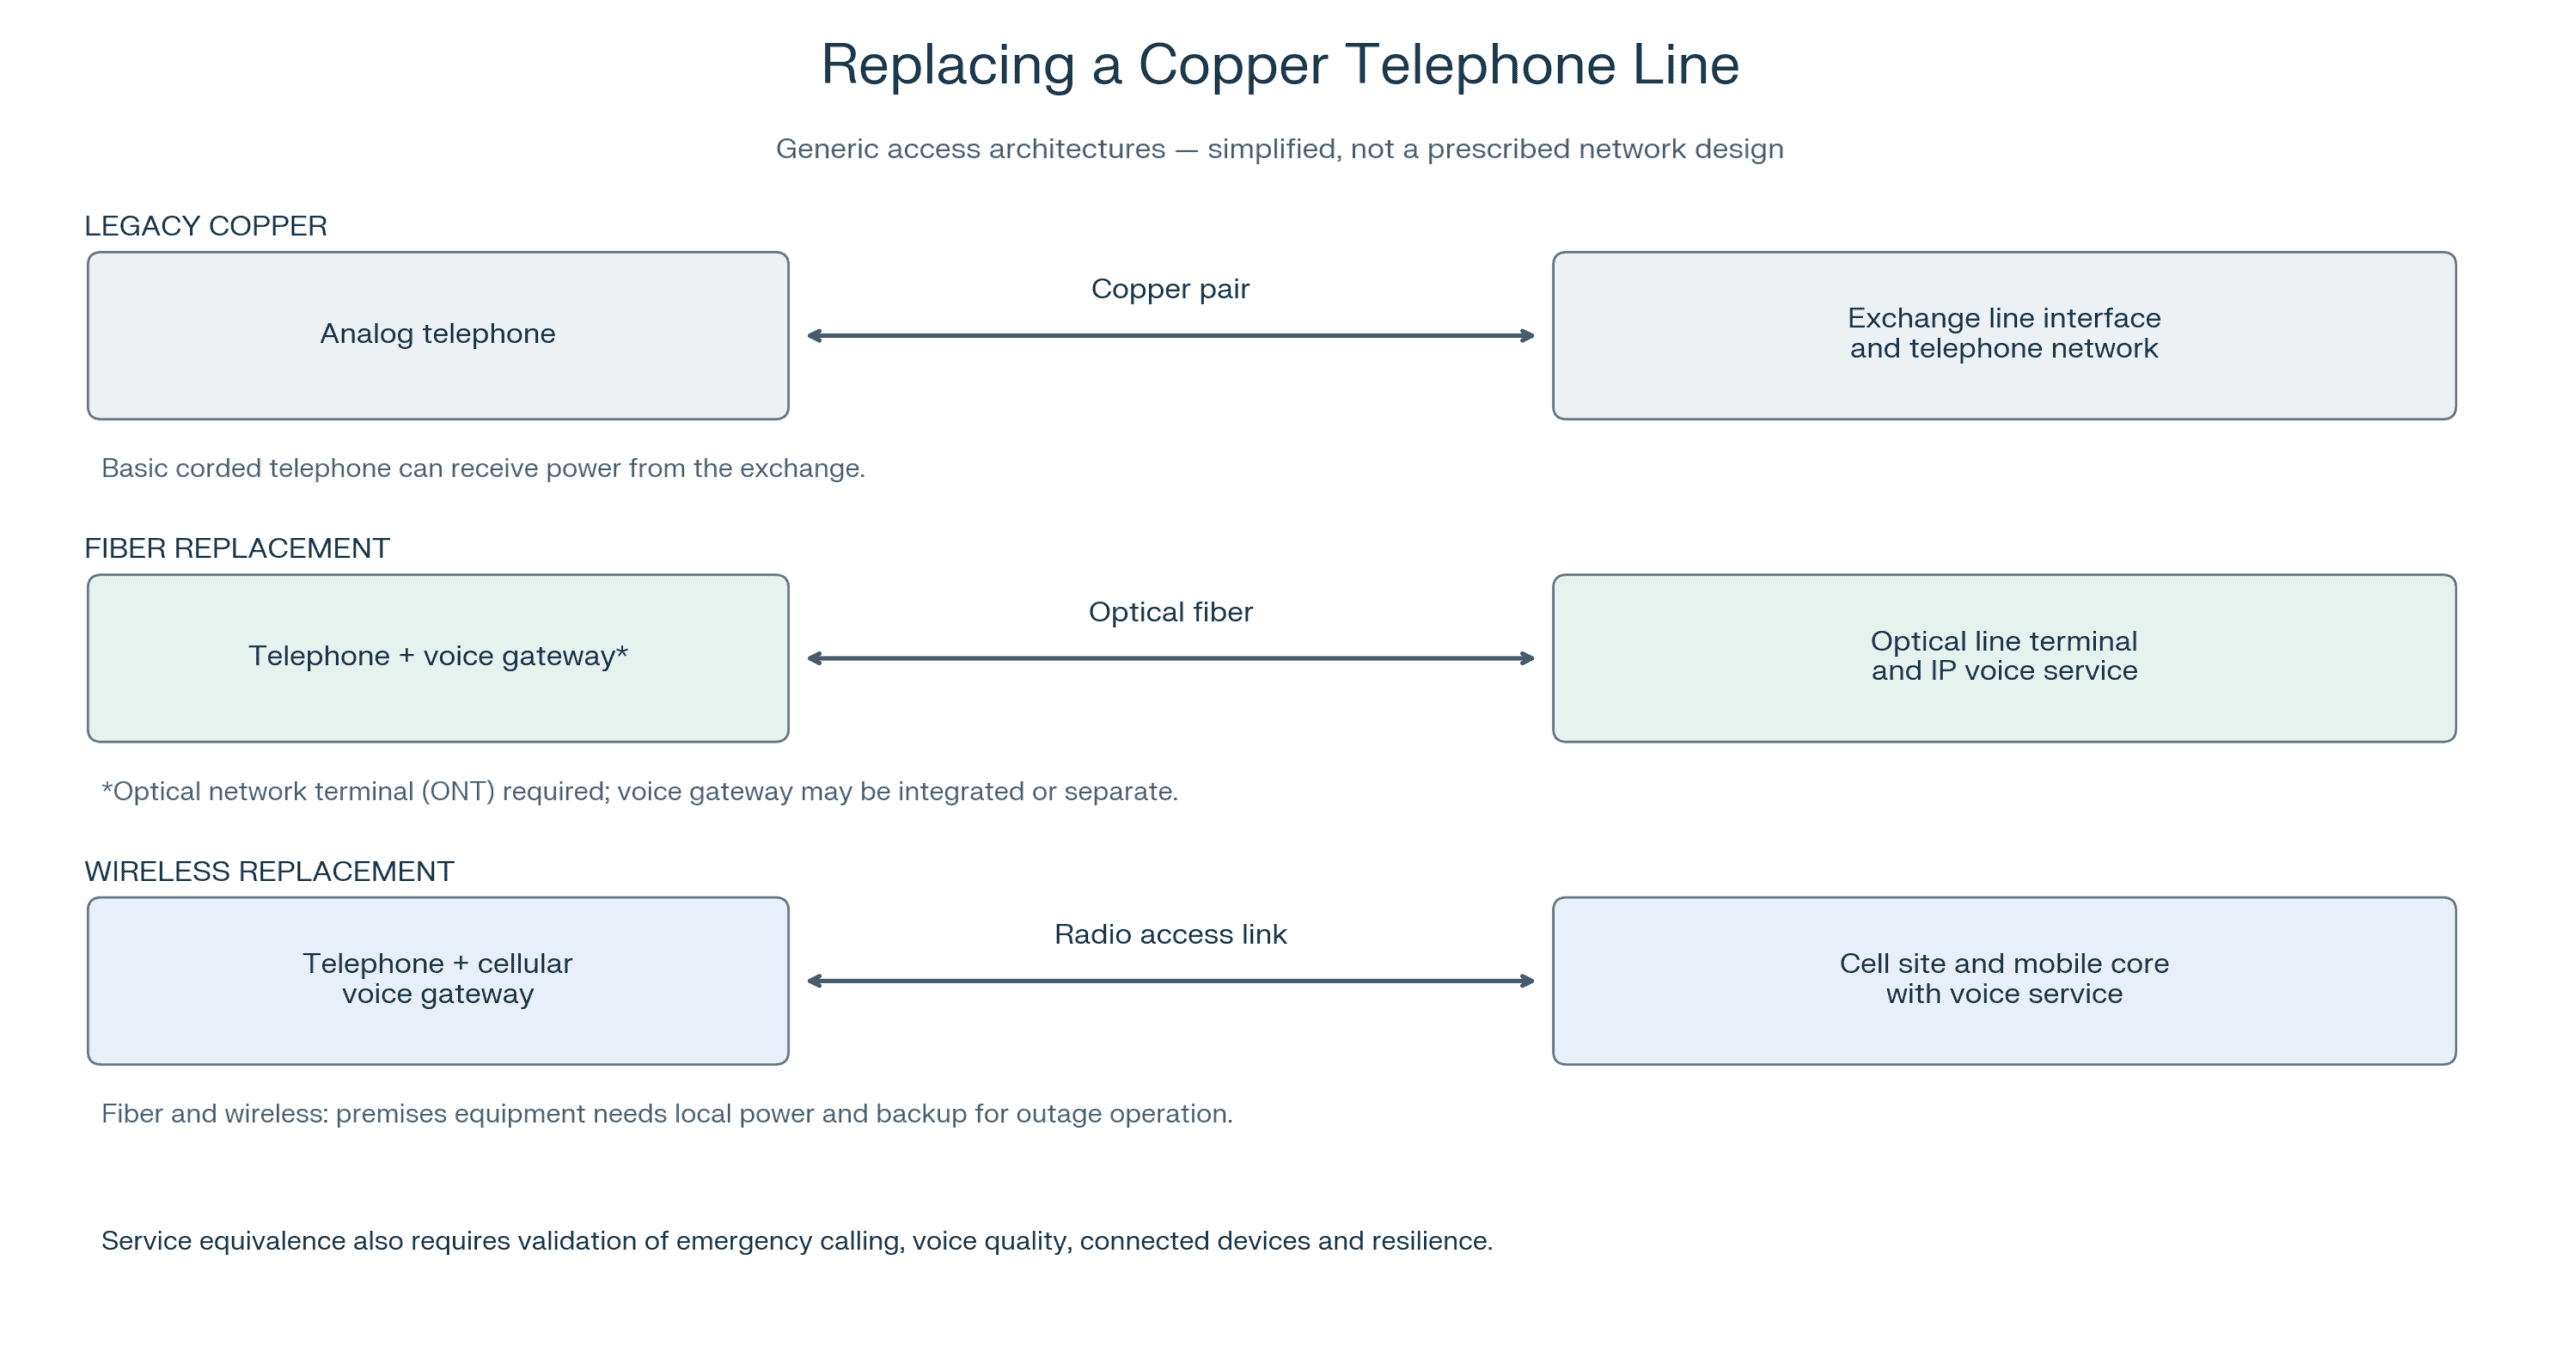
Image Generated by Perplexity.ai which was also used for research contained in this article.
……………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………
Industry activity makes this a high priority issue:
AT&T’s May 20, 2026 California announcement commits $19 billion through 2030 to fiber and wireless investment. It also describes plans to discontinue specified copper-based services in parts of California on or after June 1, 2027, while committing that customers will retain access to voice and 911 service.
“Californians depend on and expect fast, reliable connectivity every day and AT&T is committed to delivering it,” said Susan Santana, state president of AT&T California. “With recent, forward-looking federal network modernization policies, we’re able to make our largest-ever California investment commitment ($19 billion) as we transition away from copper networks. As the largest fiber builder in the state, this expands future-ready fiber and wireless services at affordable prices and modernizes copper networks. By investing in newer, more reliable technology, we can deliver better service, reach more customers, improve our communities, and support California’s economy for years to come.”
–>These are AT&T announced plans and commitments, not completed migration outcomes.
In the UK, Ofcom’s digital-landline guidance places particular emphasis on customers dependent on telephone service and on equipment connected to the line. The transition is therefore not solely an infrastructure replacement program; it also requires identifying customer needs and resolving application-level dependencies.ofcom+1
The common challenge is translating broad continuity commitments into installation-level evidence.
A proposed replacement-service acceptance framework:
No single standard cited above defines a universal substitute for every telephone landline. A practical assessment could instead use a documented service profile:
| Dimension | Proposed acceptance evidence |
|---|---|
| Basic calling | Successful incoming and outgoing calls, ringing, required calling features, and number retention where applicable. |
| Conversational performance | Results against stated objectives under representative operating conditions. |
| Premises power resilience | Demonstrated operation of all necessary equipment for an agreed duration and calling duty cycle. |
| Emergency access | Documented verification of routing, location handling, and callback arrangements through an approved procedure. |
| Connected applications | Successful end-to-end transactions for identified alarms, monitoring systems, fax devices, or other required equipment. |
| Recovery and restoration | Observed restart and reconnection behavior, plus documented fault-reporting and repair arrangements. |
| Costs and responsibilities | Clear allocation of equipment, battery replacement, maintenance, compatibility remediation, and support obligations. |
https://www.ecfr.gov/current/title-47/chapter-I/subchapter-A/part-9/subpart-H/section-9.20
https://www.ecfr.gov/current/title-47/chapter-I/subchapter-A/part-9/subpart-H
https://www.itu.int/dms_pubrec/itu-t/rec/g/T-REC-G.9807.1-202010-S!Amd2!TOC-HTM-E.htm
https://www.rfc-editor.org/info/rfc4733/
https://about.att.com/story/2026/att-makes-ca-commitment.html
AT&T’s Fiber Expansion Strengthens Its Converged Wireless and Home Broadband Strategy
S&P Global Market Intelligence Surveys: Fiber Deployments in U.S. and Europe + AI Infrastructure Causes Market Shift
T-Mobile expands FTTH footprint via 50-50 JVs with Oak Hill Capital and Wren House
2026 Fiber Connect Keynote: “The Future of Fiber Optics: AI and the Quantum”
More KPN customers use fiber vs copper for broadband services in Nederlands
U.S. fiber rollouts now pass ~52% of homes and businesses but are still far behind HFC
Ookla: U.S. Fixed Wireless Access Crosses 17 Million Connections as Adoption Shifts from Rural to Urban
According to Ookla, Fixed Wireless Access (FWA) has solidified its position as a structural component of the U.S. residential broadband market. In Q1 2026, combined FWA connections across Verizon, T-Mobile, and AT&T surpassed 17 million, representing 13.74% of the nation’s 123.75 million home broadband subscriptions, per the U.S. Census Bureau’s January 2026 American Community Survey.
Initially positioned as a cost-efficient mechanism for addressing rural connectivity gaps, FWA is now demonstrating meaningful traction in urban and suburban markets. Analysis of Ookla Speedtest Intelligence® data, segmented according to the Census Bureau’s urban-rural classifications, indicates that approximately 70% of Q2 2026 FWA test samples originated from urban users, versus 30% from rural areas. While Speedtest sample volume is not a direct proxy for subscriber counts, it offers a useful directional indicator of the geographic distribution of FWA demand.
Performance characterization across the first half of 2026 reveals steady improvements in both throughput and latency. Notably, this analysis marks the first examination of FWA at the state level: the share of FWA Speedtest users achieving the Federal Communications Commission’s (FCC) minimum broadband threshold of 100 Mbps downstream / 20 Mbps upstream fell below 40% in 48 states — underscoring the gap between marketed capacity and realized user experience.
Key takeaways:
- T-Mobile dominated Q2 2026 with a median download speed of 222.7 Mbps, (outpacing AT&T Internet Air by 38.8% and Verizon 5G Home by 76%). T-Mobile’s Q2 2026 median upload speed (18.1 Mbps) also beat AT&T by 79.2% and Verizon by 48.5%.
- All three providers experienced a performance drop in download and upload speeds between Q1 2026 to Q2 2026. This is likely a seasonal impact, as dense leaves on trees can weaken FWA signals.
- AT&T’s median download speed surged nearly 60%—from 104.61 Mbps in Q3 2025 to 167.34 Mbps in Q1 2026. This is likely the result of deploying the additional 50 MHz of spectrum purchased from EchoStar.
- Rural FWA users across all three providers nationwide have lower median download speeds and higher multi-server latency. Urban users benefit from a multi-server latency that is 7 to 13 ms lower than their rural counterparts.
- In only two states (Hawaii and New York) and the District of Columbia 40% or more of FWA Speedtest samples met the FCC’s minimum standard for broadband speed (100 Mbps download/20 Mbps upload).

AT&T’s additional spectrum holdings also translated into measurable gains on the uplink, with median upload throughput rising from 9.23 Mbps in Q3 2025 to 12.55 Mbps in Q1 2026. Despite this improvement, T-Mobile retains the highest median upload performance among the three national carriers. In Q2 2026, T-Mobile’s median upload speed of 18.12 Mbps was 48.5% above Verizon’s 12.2 Mbps and 80.1% above AT&T’s 10.06 Mbps.
All three providers recorded a quarter-over-quarter decline in both download and upload speeds from Q1 to Q2 2026, with Verizon FWA users experiencing the most pronounced degradation — a drop in median download throughput from 143.64 Mbps in Q1 2026 to 126.53 Mbps in Q2 2026.
It should be noted that the Verizon FWA figures in this report exclude Starry, the FWA operator acquired by Verizon in March 2026, whose service continues to be operated and marketed as a separate offering.
Median Download Speed Decline Q1 2026 to Q2 2026
| Provider | Q1 2026 (Mbps) | Q2 2026 (Mbps) | Speed Dip (Mbps) | Percentage Dip |
| T-Mobile Home Internet | 239.50 | 222.72 | -16.78 | -7.0% |
| Verizon 5G Home Internet | 143.64 | 126.53 | -17.11 | -11.9% |
| AT&T Internet Air | 167.34 | 160.43 | -6.91 | -4.1% |
Median upload speeds saw an even larger decline with T-Mobile FWA users experiencing a 21.5% decline in upload speeds from Q1 2026 to Q2 2026. AT&T users experienced a nearly 20% decline from Q1 2026 speeds of 12.55 Mbps to 10.06 Mbps speeds in Q2 2026.
Median Upload Speed Declines Q1 2026 to Q2 2026
| Provider | Q1 2026 (Mbps) | Q2 2026 (Mbps) | Speed Dip (Mbps) | Percentage Dip |
| T-Mobile Home Internet | 23.07 | 18.12 | -4.95 | -21.5% |
| Verizon 5G Home Internet | 14.35 | 12.20 | -2.15 | -14% |
| AT&T Internet Air | 12.55 | 10.06 | -2.49 | -19.8% |
Median multi-server latency also increased slightly from Q1 2026 to Q2 2026, which represents a slightly higher delay for FWA users. However, T-Mobile still maintained the lowest median multi-server latency at 46 ms in Q2 2026.
Median Multi-Server Latency Increases Q1 2026 to Q2 2026
| Provider | Q1 2026 (ms) | Q2 2026 (ms) | Latency Increase (ms) | Percentage Increase |
| T-Mobile Home Internet | 45 | 46 | +1 ms | +2.2% |
| Verizon 5G Home Internet | 52 | 53 | +1 ms | +1.9% |
| AT&T Internet Air | 67 | 69 | +2 ms | +3% |
………………………………………………………………………………………………………………………………………………………………………………………….
While FWA was initially conceived as a means of delivering broadband to rural communities where providers held excess network capacity, the service has since matured into a credible alternative to traditional fixed broadband. However, the latest Speedtest data indicates that, notwithstanding this intended role, rural users continue to face trade-offs in the form of lower median download throughput and elevated latency.
Operators across the board also contend with seasonal and temporal factors that degrade performance — most notably foliage interference during the spring and summer months, compounded by peak-hour network congestion on a daily basis.
T-Mobile maintains a clear performance lead across both overall throughput and latency, while AT&T’s recent spectrum acquisitions have yielded measurable performance gains.
References:
https://www.ookla.com/articles/u-s-fwa-rural-urban-1h-2026
Highlights from Ookla’s U.S. Speedtest Connectivity Report-Mobile & Fixed Networks
Ookla: U.S. dominates global WiFi 7 while adoption grew 4X to 7.2% by Q1-2026
Ookla: AI workloads will force changes in 5G mobile network infrastructure
Ookla: AI platform reliability decreases as outages surge
Ookla on the Global D2D Market
Ookla: Starlink a viable competitor for hybrid 5G/NTN services due to network performance improvements and larger coverage area
Ookla: D2D satellite connectivity surged 24.5% during last 9 months; Starlink’s footprint expansion leads the way
Starlink Mobile: NTN–Terrestrial Convergence, Network Capacity, and the Limits of Disruption
Executive Summary:
Elon Musk’s strategic objective for Starlink extends beyond satellite broadband connectivity for remote, maritime, aviation, and enterprise users. SpaceX is positioning Starlink for a broader role in mobile communications through an integrated non-terrestrial network (NTN) and terrestrial-network architecture. That strategy could combine direct-to-device (D2D) satellite connectivity, satellite backhaul, selected terrestrial access infrastructure, and potentially a retail mobile service.
Financial markets have treated that prospect seriously. Shares of U.S. wireless network operators have been under pressure since SpaceX President Gwynne Shotwell described the opportunity for “Starlink Mobile” as “huge,” in a CNBC interview on June 12th. On SpaceX’s recent earnings call, Shotwell characterized the U.S. wireless market as generating $600 billion in annual revenue and stated, “and I anticipate us to be able to acquire quite a few of their customers because I think our service will be better.”
Editor’s Note: The combined annual revenue of AT&T, Verizon, and T-Mobile is closer to $360 billion, depending on the reporting period and whether total revenue or service revenue is used.
The timing, service architecture, spectrum strategy, device ecosystem, and go-to-market model for a SpaceX mobile offering remain unresolved. A central distinction is needed: direct-to-device NTN service, satellite backhaul, a terrestrial radio access network (RAN), and a consumer mobile service are related but technically and commercially distinct propositions.
The most plausible medium-term outcome is not wholesale replacement of U.S. mobile network operators (MNOs), but deeper NTN–terrestrial integration. LEO satellite systems can extend coverage, improve resilience, support mobility, and connect underserved areas. Dense terrestrial networks retain structural advantages for high-traffic urban service, indoor coverage, and busy-hour mobile capacity.
“The perceived risk of Starlink Mobile disrupting the U.S. wireless industry is greater than the actual risk in the next one to two years,” says Morgan Stanley analyst Sean Diffley.
Starlink’s satellite-broadband business serves 12 million subscribers and reportedly generates profit margins above 60%. Musk’s ambitions, however, extend beyond connectivity for aircraft, ships, and remote fixed locations. SpaceX plans a large third-generation Starlink constellation, supported by the anticipated launch economics of its fully reusable Starship system. Starlink V3 satellites are expected to materially increase satellite capacity relative to earlier generations.
However, aggregate constellation capacity should not be equated with mobile-network capacity in dense urban markets. The relevant question is how much spectrum, beam capacity, spatial reuse, and backhaul capacity can be delivered to a given area during the busy hour.

Image Source: Facebook
…………………………………………………………………………………………………………………………………………………
Starlink Mobile could develop along four, potentially overlapping, paths:
The proposed Starlink Mobile service should therefore be assessed as an integrated network proposition, not as a simple satellite replacement for a nationwide cellular network.
Why Terrestrial Networks Retain an Advantage:
The central technical constraint is spatial/spectrum reuse. Terrestrial mobile networks deliver high area capacity by repeatedly reusing licensed spectrum across dense grids of macro cells, small cells, and indoor systems. Capacity is further increased through sectorization, advanced antenna systems, massive MIMO, carrier aggregation, and high-capacity fiber or microwave backhaul.
A LEO satellite system has different strengths. It can provide wide-area reach, support mobility, offer resilience during terrestrial outages, and extend coverage to regions where conventional network deployment is uneconomic. Yet its radio resources are shared across comparatively large beam footprints. This creates more demanding link-budget, capacity, and spectral-efficiency constraints in high-density areas, particularly for indoor service and busy-hour traffic.
Terrestrial-cell coverage areas vary considerably with spectrum band, terrain, urban morphology, antenna configuration, and load. Nevertheless, the architectural distinction remains: terrestrial networks achieve high capacity by spatially reusing spectrum over relatively small geographic areas, whereas satellite systems must manage shared capacity over much broader footprints.
For this reason, Starlink V3 satellites may substantially improve overall system capability without eliminating the terrestrial RAN advantage in dense urban and suburban markets. The strongest near-term use cases for NTN are likely to include coverage extension, emergency communications, maritime and aviation connectivity, mobility, IoT, selected backhaul, and service in remote or underserved locations.
3GPP’s NTN work is specifically directed toward integration with terrestrial cellular and wireline networks, reinforcing the view that NTN will develop as part of a broader communications architecture rather than wholly separate from it. Analyss opinions:
- Daiwa Capital Markets analyst Jonathan Kees similarly argues that Starlink is “only a complement, not a substitute” for existing wireless infrastructure.
- BofA Securities analyst Michael Funk reaches a comparable conclusion: “Existing direct-to-device satellite technology [is] underdeveloped and largely complementary to terrestrial mobile networks,” Funk says.
Spectrum, Capital, and AI:
SpaceX has acquired valuable spectrum assets through its EchoStar transactions. The FCC approved the transfer of approximately 65 MHz of spectrum to SpaceX for next-generation direct-to-device use. This is strategically important, but spectrum ownership alone does not establish a nationwide facilities-based mobile network.
A fourth nationwide MNO would require much more than spectrum. It would require:
-
Radio-access infrastructure, including macro sites, small cells, antennas, radios, and power.
-
High-capacity backhaul and transport networks.
-
Mobile core-network functions, service assurance, cybersecurity, and operational-support systems.
-
Device testing and certification, distribution, retail channels, billing, customer care, and subscriber-acquisition spending.
-
Sustained capital investment to expand coverage and capacity as traffic grows.
SpaceX must also finance Starlink V3 production, launches, constellation replenishment, gateways, ground infrastructure, and continuing development of D2D and NTN capabilities. At the same time, the company is investing heavily in AI infrastructure and Starship. Reported second-quarter capex exceeded $18 billion, including approximately $15.83 billion associated with AI infrastructure.
This does not establish that SpaceX lacks the financial capability to enter mobile communications. It does establish a major capital-allocation challenge. AI infrastructure requires rapid, front-loaded investment; terrestrial mobile networks require multi-year and geographically distributed deployment; and satellite systems require recurring capital expenditure for replenishment and capacity expansion.
—->Please see detailed discussion of this issue in Addendum below Conclusions subhead.
The key strategic risk is therefore prioritization. If AI, Starship, and satellite-constellation investment continue to absorb the majority of incremental capital, Starlink Mobile may progress more slowly as an independent terrestrial build. It may instead favor targeted terrestrial deployment, satellite-enabled backhaul, wholesale arrangements, or an MVNO model.
Starlink Coverage Issues as per Iain Morris of Light Reading:
Starlink is estimated to have between 3 and 4 million subscribers in the U.S., mostly in rural areas where there is no fixed or mobile alternative. That is, after all, why someone would opt for satellite broadband. But a small cell network built on the rooftops of these 3 to 4 million customers – or several times that amount – is not going to provide the mobile coverage demanded by anyone who even occasionally travels a few miles from home. And inside the building, what advantage would a Starlink cellular service have over Starlink-supported Wi-Fi?
SpaceX cannot possibly hope to address this coverage problem without some kind of physics-defying technological breakthrough. According to figures shared by an authoritative source on the telco side, a small cell might get you coverage about half a kilometer from the basestation, while a rural macro site would take you up to 20 kilometers from it. In urban areas where higher-frequency spectrum comes into play, this radius would probably fall to about 2 kilometers, making small cells look more competitive. The trouble there is Starlink’s lack of subscribers in cities.
Other estimates do not improve the outlook. William Webb, an academic and analyst who previously worked for UK telecom regulator Ofcom, thinks Starlink might be able to achieve a coverage radius of 1 to 2 kilometers with roof-mounted antennas, “assuming a reasonably high gain cellular antenna is integrated into the Starlink terminal and oriented correctly,” as he wrote in a LinkedIn update. But mounting below roof level would reduce the figure to less than 1 kilometer, according to Webb.
“The biggest issue will likely be that overall coverage will be patchy, concentrated in areas where there are the most Starlink broadband subscribers,” he said. “These are likely to be rural areas where fixed broadband provision is poor. As a result, coverage will likely be overlapping in rural communities but sparse outside of these areas.”
Commercial Models and Possible Partnerships:
SpaceX may determine that a fully independent nationwide mobile network is not the most efficient near-term approach. An MVNO arrangement would allow SpaceX to purchase terrestrial capacity at wholesale rates while offering a consumer service incorporating Starlink capabilities. Such a model could provide near-national coverage more rapidly, though it would reduce SpaceX’s control over network economics, service differentiation, and quality-of-service management.
Several Starlink Mobile outcomes are plausible:
Why would AT&T, Verizon, or T-Mobile enter an MVNO or deeper partnership with a prospective competitor? The answer may be competitive strategy. The first MNO to secure a commercially favorable relationship with SpaceX could gain a relative advantage in coverage, satellite integration, customer acquisition, or enterprise services.
SpaceX is “going to have to partner with one of the mobile network operators like a Verizon or T-Mobile,” says RBC Capital Markets analyst Ken Herbert. “They’re going to have to find ways to work with other companies.”
T-Mobile already has a direct-to-cell/device (D2D) relationship with SpaceX. Verizon’s FWA business is more directly exposed to fixed-broadband competition from Starlink, while AT&T, Verizon, and T-Mobile each possess extensive spectrum, RAN, transport, and customer-service assets that would be difficult and costly for a new nationwide entrant to replicate.
Evaluating Starlink/Spacex Deployment Plans:
Starlink’s satellite-broadband business serves 12 million subscribers and reportedly generates profit margins above 60%. Musk’s ambition, however, is substantially broader than providing internet access to aircraft and oceangoing vessels. SpaceX plans to deploy as many as 100,000 third-generation Starlink satellites, supported by the anticipated economics of its fully reusable Starship launch system. Starship remains in the test phase, but SpaceX has stated that it is designed to place up to 150 metric tons in orbit per launch at approximately one-tenth the per-kilogram cost of Falcon 9. Starlink V3 satellites are expected to provide roughly 10 times the capacity of earlier-generation spacecraft.
SpaceX is advancing these plans at a time when the U.S. communications market is already experiencing cross-sector competitive convergence. Fifth-generation mobile technology enabled MNOs to expand fixed wireless access (FWA) offerings and compete more directly with cable operators for residential broadband customers. The resulting service bundles combine mobile subscriptions, home broadband, and, in some cases, video and value-added services. Cable operators, in turn, have expanded mobile offerings, generally using Wi-Fi offload, their extensive wireline footprints, and mobile virtual network operator (MVNO) arrangements with incumbent wireless carriers for wide-area cellular coverage.
This competitive equilibrium has modestly favored wireless operators, although neither sector has emerged unambiguously dominant. AT&T, for example, is expected to generate sales and earnings growth over the next several years, albeit below broader market growth rates. Comcast faces a more constrained outlook, with relatively flat expected revenue and earnings performance. The valuation gap reflects both differing growth expectations and the capital intensity of maintaining and upgrading nationwide communications infrastructure.
Wall Street has amplified concerns about SpaceX’s competitive impact. Early research coverage has broadly characterized the launch, satellite-connectivity, and artificial-intelligence company as a disruptive force. The average analyst price target for SpaceX stock is approximately $227, implying a valuation near $3 trillion—roughly five times the combined market capitalization of AT&T, Verizon, and T-Mobile.
The major U.S. MNOs also operate with substantial debt burdens. AT&T, Verizon, and T-Mobile collectively carry approximately $420 billion in net debt, against about $140 billion in expected 2026 EBITDA. “I would not for a second sleep easily if I had the investments that [wireless telecom providers] have, and the debt that they have, and Elon Musk working on a superweapon as it pertains to my business,” says Drew Cupps of Polen Capital.
Nevertheless, Starlink faces significant capital, engineering, and deployment challenges before it can offer a broadly substitutable mobile service. Daiwa Capital Markets analyst Jonathan Kees argues that the investment required to build a V3-based Starlink constellation capable of materially disrupting terrestrial operators is underestimated. He estimates that constellation deployment could require more than $100 billion, excluding investment associated with SpaceX’s AI initiatives. Starlink is “only a complement, not a substitute” for existing wireless infrastructure, says Kees.
The fundamental constraint is spatial reuse and capacity density. A terrestrial cell site can concentrate spectrum resources over a coverage area measured in a few square miles, while a LEO satellite beam may serve a much broader footprint. Satellite systems therefore face more difficult link-budget, capacity, and spectral-efficiency challenges in dense urban environments, particularly for indoor service and high-traffic applications. V3 satellites may substantially improve system capacity, but they do not eliminate the capacity advantage of dense terrestrial RAN deployments.
For that reason, BofA Securities analyst Michael Funk does not view SpaceX as an immediate, large-scale competitive threat to incumbent MNOs. While some projections assign LEO-based mobile services 15% to 35% of the U.S. telecommunications market, Funk regards those estimates as overly optimistic. “Existing direct-to-device satellite technology [is] underdeveloped and largely complementary to terrestrial mobile networks,” Funk says. That assessment is consistent with Starlink’s present international model, which emphasizes partnerships with mobile operators rather than wholesale replacement of their networks.
Conclusions:
Starlink Mobile is an important strategic development in the evolution of NTN–terrestrial convergence. It should not, however, be evaluated as a satellite-only replacement for nationwide cellular networks.
LEO systems can provide broad-area reach, coverage extension, resilience, mobility, selected backhaul, and direct-to-device services. Dense terrestrial RAN infrastructure retains decisive advantages in spatial reuse, indoor coverage, spectrum utilization, and busy-hour capacity. Starlink’s most credible competitive impact in the near and medium term is therefore likely to occur in selected coverage, mobility, resilience, backhaul, and fixed-broadband segments—not through immediate replacement of nationwide terrestrial mobile networks.
The central uncertainty is which architecture and commercial model SpaceX will adopt. Its concurrent commitments to AI infrastructure, Starship, satellite replenishment, and spectrum assets may favor a hybrid or partnership-led approach over a fully independent nationwide MNO build.
In that outcome, incumbent operators’ spectrum, terrestrial RAN, fiber backhaul, tower infrastructure, customer relationships, and regulatory authorizations remain strategically important. Rather than becoming obsolete, those assets may increase in value as NTN and terrestrial networks become more tightly integrated.
If satellite and terrestrial systems become increasingly interdependent, incumbent operators’ assets may become more valuable rather than less. Spectrum, fiber backhaul, tower infrastructure, distributed RAN assets, customer relationships, billing systems, and regulatory authorizations remain essential elements of an integrated non-terrestrial network (NTN) and terrestrial-network ecosystem. EchoStar’s share-price appreciation over the past year illustrates the strategic value that spectrum holdings can command, particularly as SpaceX and AT&T acquire additional spectrum assets.
The three national U.S. wireless operators collectively hold spectrum assets estimated to be worth more than $400 billion based on recent transaction benchmarks. That figure is approximately 80% of their combined market capitalization and is broadly comparable to their aggregate debt burden. Spectrum holdings alone do not establish an investment thesis, but they provide a meaningful asset-value foundation as satellite, terrestrial, and hybrid connectivity models continue to evolve. They aren’t going to sell their spectrum. They have businesses to run, and those businesses are reasonably valued and growing.
Addendum: AI Capex is a Significant Risk for Starlink Mobile:
AI-data-center investment is a significant capital-allocation risk to Starlink Mobile, but it is not, by itself, evidence that SpaceX lacks the financial capacity to enter mobile communications. The more credible concern is that AI, Starship, constellation replenishment, and terrestrial mobile deployment will compete for capital simultaneously—potentially slowing Starlink Mobile’s rollout, limiting network densification, or increasing reliance on an MVNO partnership.
SpaceX’s capital spending has risen sharply: reported second-quarter capex exceeded $18 billion, including approximately $15.83 billion directed to AI infrastructure. Management indicated that similarly elevated capex could continue over subsequent quarters. Meanwhile, Starlink profitability and connectivity operations remain an important source of funding for the broader AI strategy.
A facilities-based mobile network would add another exceptionally capital-intensive program:
-
SpaceX has already committed approximately $19.6 billion through its EchoStar spectrum transactions for up to 65 MHz of spectrum, including associated debt obligations. Thus, the issue is not whether it can acquire any spectrum; it has already done so. The issue is whether that spectrum portfolio is sufficient for a competitive nationwide terrestrial-mobile network, particularly in high-density markets.reuters
-
A fourth nationwide MNO requires far more than spectrum: site acquisition, radios, antennas, power, backhaul, core-network functions, device certification, retail/distribution, customer care, and sustained subscriber-acquisition spending.
-
Starlink must also fund V3 satellite production, launch capacity, gateway infrastructure, constellation replenishment, and the evolution of direct-to-device/non-terrestrial-network capabilities.
These programs have distinctly different investment horizons. AI infrastructure requires rapid, front-loaded spending to secure compute capacity; terrestrial mobile networks require multi-year, geographically distributed capex; and satellite systems require continuous capital expenditure to maintain and upgrade orbital capacity.
The likely consequence is not cancellation of Starlink Mobile, but a more capital-disciplined architecture than a conventional nationwide greenfield MNO build. SpaceX has said it intends to build terrestrial mobile services but has not disclosed projected mobile capex or a site-count plan; analysts have warned that a competitive direct-to-consumer national offering would be very difficult without an MVNO agreement providing broad baseline coverage. This produces three plausible outcomes:
Satellite connectivity can reduce backhaul requirements at selected sites and enhance rural, maritime, aviation, emergency, and resilience use cases. It cannot economically substitute for dense terrestrial spectral reuse in the highest-traffic urban areas. Therefore, AI-related capex pressure is particularly relevant because Starlink Mobile needs substantial investment precisely where the satellite component provides the least complete replacement for terrestrial infrastructure.
A key additional risk is strategic prioritization, not immediate insolvency. If SpaceX continues allocating the overwhelming share of incremental capital to AI data centers and Starship, Starlink Mobile may emerge as a hybrid service, wholesale platform, or MVNO-enabled offering rather than a fully independent fourth nationwide carrier. That outcome would reduce the near- to medium-term disruption risk to AT&T, T-Mobile, and Verizon. It would also reinforce the more technically credible view that Starlink is likely to be complementary to terrestrial mobile networks for years, even if it becomes a powerful competitor in selected coverage, backhaul, and mobility segments.
……………………………………………………………………………………………………………………………………………………………..
References:
https://www.barrons.com/articles/spacex-wont-destroy-telecomit-will-just-reinvent-it-79b88d1a
https://www.lightreading.com/satellite/spacex-small-cell-plan-serves-up-more-musk-madness
FT: SpaceX considering Starlink Direct-to-Consumer mobile service & terrestrial cellular network infrastructure in the U.S. (See Comments below the article)
Ookla: Starlink a viable competitor for hybrid 5G/NTN services due to network performance improvements and larger coverage area
Ookla: D2D satellite connectivity surged 24.5% during last 9 months; Starlink’s footprint expansion leads the way
US Mobile’s new bundle combines its multi-network mobile service with Starlink residential internet
Direct-to-Device (D2D) satellite network comparison: Starlink V2 (Starlink Mobile) vs “Satellite Connect Europe”
Blue Origin announces TeraWave – satellite internet rival for Starlink and Amazon Leo
Broadcom with Samsung Electronics: Integrated 5G and Wi-Fi 8 FWA Platform
Broadcom has announced a collaboration with Samsung Electronics Co., Ltd. to develop a reference platform for fixed wireless access (FWA) deployments, combining Broadcom’s BCM6776 Wi-Fi system-on-chip (SoC) with Samsung’s B1320 5G modem. The platform is designed to integrate 3GPP Release 17 5G connectivity with emerging IEEE 802.11bn (Wi-Fi 8) capabilities, supporting convergence between wide-area and local-area broadband technologies.
The reference design targets global FWA use cases, where operators seek to deliver high-throughput broadband services using 5G radio access in conjunction with advanced in-home wireless distribution. By aligning 5G and Wi-Fi 8 performance characteristics, the platform addresses requirements for sustained throughput, low latency, and reliability under variable radio conditions. The design also emphasizes scalability for high-volume deployments, with integration intended to reduce system complexity and cost.
The Broadcom BCM6776 is a tri-band Wi-Fi 8 SoC designed for residential and small enterprise access points. It integrates a quad-core Arm-based network processor with Wi-Fi 8 radio functionality in a single device. The SoC supports 2-stream operation with 40 MHz channels in the 2.4 GHz band, and 4-stream operation with up to 160 MHz channels in the 5 GHz and 6 GHz bands. This configuration enables multi-gigabit aggregate throughput while maintaining compatibility with evolving IEEE 802.11bn features.
Integration of compute and radio subsystems within a single SoC reduces bill of materials (BOM) requirements and simplifies hardware design. Power efficiency is also improved relative to prior architectures that relied on discrete components, supporting deployment in thermally constrained residential environments.

Image Credit: Broadcom
…………………………………………………………………………………………………………………………………………………
The Samsung B1320 modem is a 5 nm-class integrated 5G chipset compliant with 3GPP Release 17. It supports peak downlink throughput of up to 3.43 Gbps and uplink throughput of up to 1.17 Gbps, depending on deployment configuration. The modem incorporates a quad-core Arm CPU, RF transceiver, power management functions, and a global navigation satellite system (GNSS) receiver.
The platform further supports non-terrestrial network (NTN) operation, including both NR-NTN and NB-NTN modes, enabling compatibility with satellite-based extensions of 5G coverage.
The combined architecture is designed to sustain end-to-end throughput between the 5G access link and the in-home Wi-Fi network, minimizing bottlenecks between the wide-area and local domains. This is particularly relevant for FWA deployments, where performance is constrained by both radio access conditions and in-premises distribution efficiency.
By providing a pre-integrated reference design, the platform enables original equipment manufacturers (OEMs) and operators to accelerate development cycles and standardize system performance across deployments. This approach supports broader adoption of FWA as a complement to fixed broadband infrastructure, particularly in scenarios where fiber deployment is limited or economically constrained.
“At Computex 2026, we are highlighting that the future of home internet can be both accessible and affordable,” said Joonsuk Kim, Executive Vice President and Head of CP Development at Samsung Electronics. “This platform is designed to deliver reliable performance across a wide range of environments, helping operators bring high-quality connectivity experiences to subscribers.”
“Broadcom is proud to lead the Wi-Fi 8 transition alongside Samsung and our valued ODM partners,” said Vijay Nagarajan, Vice President of Marketing, Wireless and Broadband Communications Division at Broadcom. “This partnership is a game-changer for the FWA market. The combination of Wi-Fi 8 and 5G prioritizes coordinated reliability, giving operators a tool that delivers a consistent experience to every corner of the home.”
Product Features:
The Samsung B1320 is a broadband-optimized 5G platform with the following features:
- 3GPP Release 17
- 4Rx/2Tx radio chain support
- Power Class 1.5 support (TDD bands)
- LPDDR4x / LPDDR5x support
- 1.6 GHz quad-core ARM Cortex-A55 CPU
- 5 Gbps USXGMII, PCIe Gen 3, USB 2.0
- GNSS
- NR-NTN and NB-NTN support for n255 and n256 (L- and S-bands)
The Broadcom BCM6776 is a single-chip Wi-Fi SoC and multi-band radio supporting the following:
- High performance quad-core CPU complex
- Dedicated network processing engine freeing the CPU complex for operator-specific applications and utilities
- Integrated 2×2 2.4 GHz and 4×4 5 GHz and 6 GHz Wi-Fi 8 MAC/PHY/Radio functionality, simplifying system design and lowering cost
- On-chip 2.4 GHz power amplifiers (PAs) and support for third-generation digital pre-distortion for reduced external components and improved RF efficiency
- Versatile memory controller supporting DDR4, LPDDR4, DDR5, and LPDDR5
- Dual PCIe Gen3 controllers to enable simultaneous tri-band applications with a single additional chip
- Integrated multi-gig PHY
A Global Ecosystem of Support:
The launch is supported by the world’s leading original equipment manufacturers (OEMs), who are already integrating the B1320 / BCM6776 platform into their next-generation gateway portfolios.
“HUMAX Networks is delighted to pioneer the next-generation 5G CPE market alongside global technology leaders Broadcom and Samsung. At the recent MWC 2026, we successfully showcased the industry’s first Wi-Fi 8 solution, which integrates Samsung’s cutting-edge 5G technology with Broadcom’s next-generation silicon. Through our ongoing partnership, we remain committed to driving market innovation and consistently delivering top-tier experiences and innovative devices to our global customers,” said Jerry Lee, CEO of Humax Networks.
“We are delighted to collaborate with Broadcom and Samsung to develop our next generation Wi-Fi 8 gateway addressing MSO CBU/FWA market. This solution is capable of delivering a smarter, more secure, and future-ready network optimized solution to meet MSO/FWA customers’ increasing demands of cost competitive 5G NR connectivity,” said Johnson Hsu, SVP & GM of WNC’s Connectivity & Solutions BG.
Availability:
Global carrier trials and OEM sampling of the Samsung B1320 / Broadcom BCM6776 FWA platform are underway.
About Broadcom:
Broadcom Inc. (NASDAQ: AVGO) is a technology leader that designs, develops, and supplies semiconductors and infrastructure software for global organizations’ complex, mission-critical needs. Broadcom combines long-term R&D investment with superb execution to deliver the best technology, at scale. Broadcom is a Delaware corporation headquartered in Palo Alto, CA. For more information, visit www.broadcom.com.
Broadcom, the pulse logo, and Connecting everything are among the trademarks of Broadcom. The term “Broadcom” refers to Broadcom Inc., and/or its subsidiaries. Other trademarks are the property of their respective owners.
…………………………………………………………………………………………………………………..
References:
Extreme Networks deploys Wi‑Fi 7 (IEEE 802.11be) at University of Florida’s “Swamp”
Ookla: FWA Speed Test Results for big 3 U.S. Carriers & Wireless Connectivity Performance at Busy Airports
Aviat Networks and Intracom Telecom partner to deliver 5G mmWave FWA in North America
T-Mobile’s growth trajectory increases: 5G FWA, Metronet acquisition and MVNO deals with Charter & Comcast
Analysis: AT&T 1Q-2026 results: increased fiber penetration, FWA momentum, D2D deals, and mobile/home internet bundles
Latest Ericsson Mobility Report talks up 5G SA networks and FWA
Analysis: Broadcom’s end-to-end 50G PON Edge AI portfolio with WiFi 8 support
Broadcom has announced the BCM68850, a 50G ITU-T PON home gateway system-on-chip (SoC) that integrates a neural processing unit (NPU) and provides native support for emerging Wi-Fi 8 (IEEE 802.11bn) capabilities. The device extends the evolution of broadband access silicon toward higher-capacity passive optical network (PON) standards while maintaining alignment with next-generation in-home wireless technologies. Broadcom is currently sampling the BCM68850 and BCM55050 to its early access customers and partners. Please contact your local Broadcom sales representative for samples and pricing.
The integration of NPU functionality within the gateway reflects an architectural trend toward distributing compute resources closer to the network edge. This enables localized processing of AI-driven workloads within customer premises equipment (CPE), which can reduce upstream bandwidth demand and improve responsiveness for latency-sensitive applications.
Migration to 50G PON, as defined within ongoing ITU-T standardization efforts (e.g., Higher Speed PON), provides increased access capacity and improved latency characteristics relative to earlier generations such as XGS-PON. These enhancements support more deterministic service delivery, particularly in environments where traffic patterns are becoming increasingly burst-oriented and driven by compute-intensive applications.
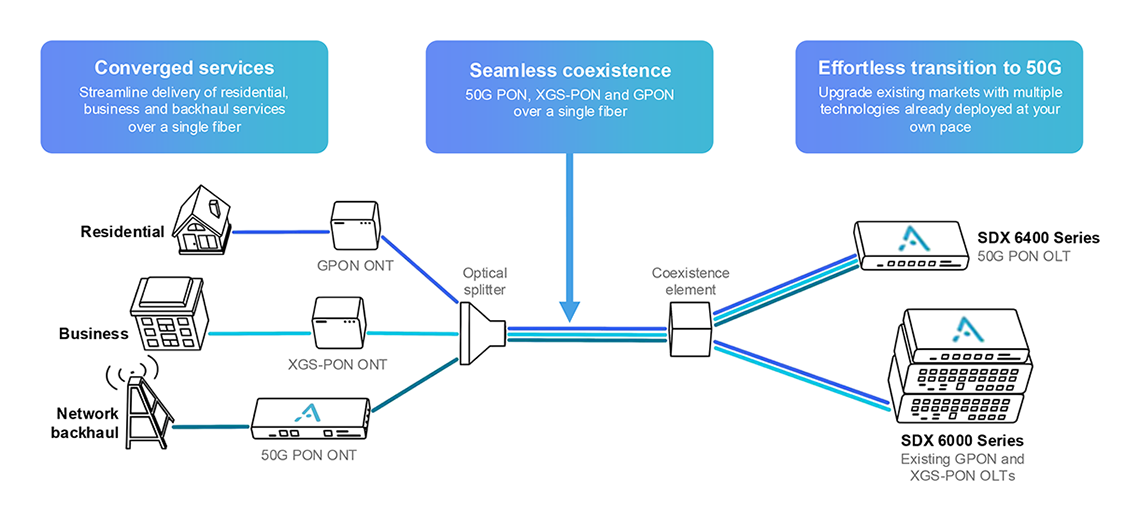
Image Credit: ADTRAN
…………………………………………………………………………………………………………………………………………………………………………………………………………………………..
In residential networks, traffic is expected to increasingly consist of short-duration, high-throughput bursts associated with edge processing, real-time analytics, and interactive services. A 50G PON gateway can accommodate these patterns by transmitting high-density payloads over sub-millisecond intervals, after which shared channel resources are rapidly released for other users. This behavior contributes to improved utilization efficiency on shared fiber infrastructure.
Low-latency and low-jitter performance are important for emerging application classes, including distributed AI inference, synchronized edge workloads, and multi-stream ultra-high-definition media. These requirements extend across both the access network and the in-home wireless domain, reinforcing the need for coordinated evolution of PON and Wi-Fi technologies.
From a deployment perspective, introduction of 50G-capable CPE provides operators with additional capacity headroom and supports alignment with future service requirements. Coupled with advancements in IEEE 802.11bn, this approach enables continued scaling of residential broadband performance while maintaining consistency across access and local network segments.
BCM68850 – 50G PON Edge AI Gateway SoC:
The BCM68850 is a standalone 50G PON Gateway SoC that provides an industry-standard ITU-T path for operators to future-proof their networks. The device features:
- High-Performance Application Engine: A dedicated CPU for third-party and operator applications leveraging industry available middleware.
- Integrated Neural Engine: A dedicated NPU that accelerates Edge AI inference, reducing cloud latency and enhancing data privacy by keeping sensitive information on premises.
- Symmetric 50G Performance: Delivers full 50G throughput to meet the insatiable appetite for reliable, multi-gigabit bandwidth.
- Wi-Fi 8 Ready: Native compatibility with Wi-Fi 8 standards to ensure the highest reliability and real-world consistency at the broadband edge.
- Intelligent Self-Healing: Enables operators to implement real-time anomaly detection and predictive bandwidth optimization, reducing OpEx and improving ARPU.
- Advanced Security: Incorporates enhanced security algorithms, including Post-Quantum Cryptography (PQC).
“The BCM68850 is a defining milestone for global fiber networks; we are reshaping the broadband edge as the central intelligence hub of the home,” said Philip Radtke, vice president of product marketing for Broadcom’s Wireless and Broadband Communications Division. “This flagship SoC joins our established lineup of NPU-accelerated fiber, cable, set-top box, and Wi-Fi solutions, ensuring operators can efficiently deploy edge-intelligent broadband regardless of the access medium and extend that intelligence all the way to the edge.”
“With ever increasing consumer and enterprise demand for bandwidth and ultra-reliable connectivity, operators are upgrading the Central Office and End Points with 50G PON capability. Next-generation solutions such as Broadcom’s BCM68850 SoC are critical to unlocking the value of this investment by future-proofing the network edge and ensuring high service levels at every node and premise,” said Jaimie Lenderman, practice leader for Optical, IP, and Broadband Infrastructure market research at Omdia.”By establishing a true end-to-end 50G pipe, operators can deliver the massive capacity and deterministic low latency required to support the rigors of the imminent Wi-Fi 8 deployment cycle.”
This end-to-end 50G offering completes the path from Broadcom’s BCM68660 OLT to the edge, providing a seamless and technically robust ecosystem comprising the BCM55050 ONT or the BCM68850 CPE gateway. This architecture introduces a new level of efficiency by optimizing CPU and memory resources for the AI era, ensuring that the home gateway can handle the massive data pipes required for the next decade of digital innovation.
About Broadcom:
Broadcom Inc. (NASDAQ: AVGO) is a technology leader that designs, develops, and supplies semiconductors and infrastructure software for global organizations’ complex, mission-critical needs. Broadcom combines long-term R&D investment with superb execution to deliver the best technology, at scale. Broadcom is a Delaware corporation headquartered in Palo Alto, CA. For more information, visit www.broadcom.com.
Broadcom, the pulse logo, and Connecting Everything are among the trademarks of Broadcom. The term “Broadcom” refers to Broadcom Inc., and/or its subsidiaries. Other trademarks are the property of their respective owners.
References:
https://www.broadcom.com/company/news/product-releases/64341
2026 Fiber Connect Keynote: “The Future of Fiber Optics: AI and the Quantum”
Nokia and Google Fiber trial 50G PON – first in the U.S.
HKT is first to deploy 50G PON technology in Hong Kong
Türk Telekom and ZTE trial 50G PON, but commercial deployment is not imminent
Ooredoo Qatar is first operator in the world to deploy 50G PON
Highlights of FiberConnect 2024: PON-related products dominate
Fiber Connect 2023: Telcos vs Cablecos; fiber symmetric speeds vs. DOCSIS 4.0?
Analysis: AT&T 1Q-2026 results: increased fiber penetration, FWA momentum, D2D deals, and mobile/home internet bundles
AT&T reported first-quarter results today, achieving its fastest-ever year-over-year organic growth in its advanced connectivity convergence rate, with nearly 45% of advanced home internet subscribers also choosing AT&T wireless. Customers are increasingly purchasing their internet and wireless together from AT&T, highlighting the strength of the company’s differentiated, investment-led strategy to drive converged advanced connectivity at scale.
“We saw our best first quarter ever for Advanced Connectivity internet customer net additions, demonstrating the solid foundation of assets we have built,” said John Stankey, AT&T Chairman and CEO. “We’re uniquely positioned to deliver more of what customers want — fiber and 5G all from one provider on the nation’s largest advanced converged network, backed by the AT&T Guarantee. The actions we’ve taken this quarter are evidence of how we are improving the customer value proposition, scaling faster, and accelerating growth.”
AT&T reported $31.5 billion in consolidated operating revenues, representing a 2.9% year-over-year (YoY) increase and outperforming Street estimates of $31.22 billion. This growth was largely driven by the Advanced Connectivity segment, which generated $22.15 billion in consumer revenues, up from $20.97 billion in the prior-year period.
- Wireless Performance: Mobility services posted mostly flat $16.94 billion in revenue, compared to $16.65 billion in Q1 2025.
- Legacy Decommissioning: Legacy revenues fell 25.3% YoY to $1.8 billion. The aggressive copper-to-fiber migration continues, with 85% of wire centers now approved for legacy service cessation.
- Strategic Sunsetting: 30% of these wire centers are slated for total decommissioning by late 2026, coinciding with the loss of 270,000 DSL subscribers this quarter.
The shift toward high-speed, durable connectivity is evidenced by the growth of AT&T’s Fiber and Fixed Wireless Access (FWA) portfolios.
- Fiber Penetration: AT&T recorded 292,000 fiber net additions, bringing the total subscriber base to 12.5 million. The current passings stand at 37.5 million locations, with 32.7 million owned/operated and 4.8 million via joint ventures (JVs).
- FWA Momentum: AT&T Internet Air added 239,000 customers in the quarter (up from 181,000 in Q1 2025), reaching a total of 1.73 million subscribers.
- Roadmap to 60 Million: AT&T remains on track to reach 60 million fiber locations by 2030 through organic expansion, the Gigapower JV, and open-access agreements.
AT&T is evolving its “NetworkCo” model to optimize capital intensity and market reach.
- Lumen Asset Integration: Recently acquired fiber assets from Lumen will be transferred into a JV structure. CFO Pascal Desroches expects to finalize an agreement with an equity partner for these assets in 2H 2026.
- Convergence and “One Connect”: The “One Connect” platform is the cornerstone of AT&T’s converged strategy.
- Bundle Adoption: 42% of advanced home internet customers (5.68 million) also subscribe to mobile services.
- Fiber-Mobile Synergy: Among fiber-specific customers, the mobility bundle penetration rate is 40.2% (4.74 million).
- The “One Connect” Roadmap: CEO John Stankey views the platform as an iterative engine, beginning with BYOD (Bring Your Own Device) and eventually expanding into tailored family plans.
“We made further progress at positioning AT&T as the preferred provider for connecting consumers and businesses to the internet. We closed our transaction with Lumen, ahead of schedule, adding 1.1 million fiber customers, and over 4 million fiber locations. We’re pleased with the progress we’re making as we integrate these assets in several major metro areas and position the business for faster growth. Early indicators are positive. We now offer fiber services throughout our distribution channels in these areas, which has driven sales activity well above pre-transaction trends. We’re executing the steps to scale engineering, construction and service delivery in the acquired geographies, expected as we move into the back half of the year, will achieve steady improvement in fiber and wireless customer growth in these areas. When we focus on customers needs and invest in the experience and products they want, we find success, and in the first quarter, we gave customers more reasons to choose AT&T. We expanded the AT&T guarantee to cover internet Air and launched a new flagship app to deliver a simple digital-first experience to customers.
We also launched AT&T OneConnect, which enables customers to easily connect all their eligible devices at home and on the go, and eliminates the need to buy internet access twice. We refreshed our Unlimited Your Way plans to deliver more value. All these moves are based on a consistent set of principles that drive our approach to serving customers the way they want to be served, with offers that deliver simplicity, value and choice and converged connectivity.
After years of industry-leading investments in our fiber and wireless network, we believe that we have now established a structural advantage that others will not catch. We reached more than 90 million customer locations across the country with our advanced internet services, over either fiber or 5G. We believe this provides us with more scalable reach and converged connectivity than any of our peers, including a meaningful scale and performance advantage in fiber. This is an advantage we’re growing as we ramp our deployment at a faster pace than anyone else. Today, we reach over 37 million customer locations with fiber, and we’re on track to reach 60 million plus locations by the end of the decade.”
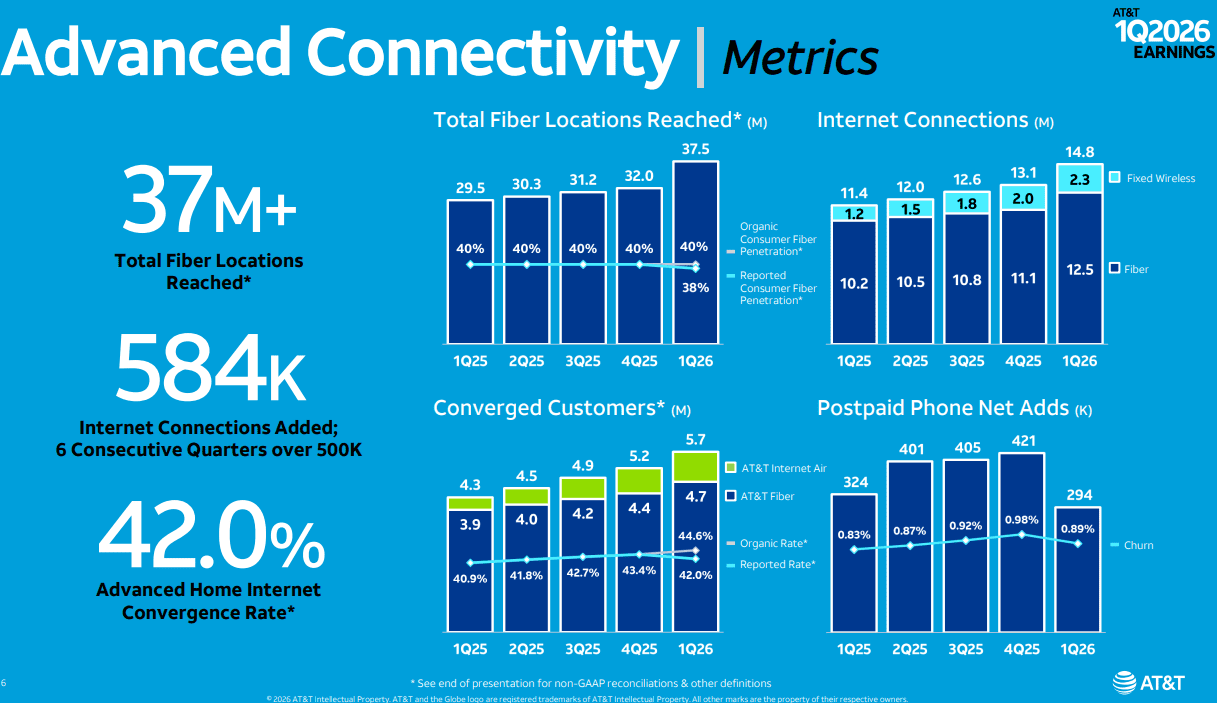
NTNs and D2D:
Regarding its choice of AST SpaceMobile for direct-to-device (D2D) connectivity for its smartphones, Stankey said, “I think it’s natural that we work with LEO partners that have the capabilities to solve that problem, to integrate those offerings into our services,” Stankey said Tuesday on AT&T’s Q1 2026 earnings call. “My goal would be that I have a good, strong wholesale relationship, and it may not just be with one of them. It may be with more than one of them.”
Besides AST SpaceMobile, Stankey said he expects SpaceX/Starlink to have a “robust direct-to-device capability,” as well as Amazon Leo and potentially a fourth NTN satellite internet company. SpaceX is developing a next-generation D2D offering with spectrum it’s acquiring from EchoStar, and Amazon plans to introduce a new D2D offering in 2028 amid its recent deal to acquire Globalstar. AT&T has a deal with Amazon Leo to connect business customers that are out of reach of terrestrial wireless and wireline networks, but it has not yet signed a D2D-specific deal with Amazon’s satellite and services unit.
Market Analysis – The Fiber Coverage Gap:
Despite strong growth, analysts remain cautious regarding AT&T’s convergence ceiling. With fiber currently available in only about 20% of the U.S., the primary concern is whether AT&T can maintain competitive parity in non-fiber regions.
- Potential Underperformance Risk: In markets where AT&T relies on legacy copper or wholesale third-party access, it may struggle to match the churn reduction and ARPU (Average Revenue Per User) lift seen in its “Fiber + Wireless” footprint.
- Mitigation Strategy: The success of the “60-million-locations fiber by 2030” roadmap which is the primary driver of AT&Ts increased spending. Also, the scaling of Internet Air as a “bridge” technology will be critical in preventing regional underperformance.
- 2026 Milestone: AT&T expects to exceed 40 million total fiber locations by the end of 2026.
- Build Cadence: The company is targeting an organic deployment pace of 4 million new locations per year by the end of 2026. After 2026, this rate is projected to increase to approximately 5 million additional spots annually.
- Funding Mechanism: To support this acceleration, AT&T plans to reinvest $3.5 billion in cost savings specifically into the fiber build-out over the 2026–2027 period.
- “There’s no path for AT&T to have a fiber footprint that will cover more than a third of the country. Will AT&T be consigned to losing share in the other two thirds?” MoffettNathanson analyst Craig Moffett asked in a research note to clients posted after AT&T’s earnings call.
Despite the high CapEx, AT&T CFO Pascal Desroches reaffirmed that the company remains on track to deliver $18 billion+ in free cash flow (FCF) for 2026.
………………………………………………………………………………………………………………………………………………………………………
References:
https://www.lightreading.com/satellite/at-t-might-look-beyond-ast-spacemobile-for-d2d
Analysis: AT&T’s $250B network investment to advance U.S. connectivity
AT&T and AWS to deliver last mile connectivity for AI workloads; AT&T Geo Modeler™ AI simulation tool
AT&T and Ericsson boost Cloud RAN performance with AI-native software running on Intel Xeon 6 SoC
AT&T’s convergence strategy is working as per its 3Q 2025 earnings report
AT&T deploys nationwide 5G SA while Verizon lags and T-Mobile leads
AT&T to buy spectrum licenses from EchoStar for $23 billion
AT&T grows fiber revenue 19%, 261K net fiber adds and 29.5M locations passed by its fiber optic network
Dell’Oro: Fixed Wireless Access revenues +10% in 2025 & will continue to grow 10% annually through 2029
Additional highlights from the Fixed Wireless Access Infrastructure and CPE Advanced Research Report:
- Total FWA subscriptions, which include residential, SMB, and large enterprises, are expected to grow steadily, surpassing 191 million by 2029.
- 5G Sub-6GHz and mmWave units will dominate the global residential CPE market.
The Dell’Oro Group Fixed Wireless Access Infrastructure and CPE Report includes 5-year market forecasts for FWA CPE (Residential and Enterprise) and RAN infrastructure, segmented by technology, including 802.11/Other, 4G LTE, CBRS, 5G sub-6GHz, 5G mmWave, and 60GHz technologies. The report also includes regional forecasts for FWA subscriptions, including for both residential and enterprise markets, with the enterprise subscriptions segmented by SMB and Large Enterprise. To purchase this report, please contact us by email at [email protected].
………………………………………………………………………………………………………………………………………………………………………
Independent Analysis via Perplexity.ai:

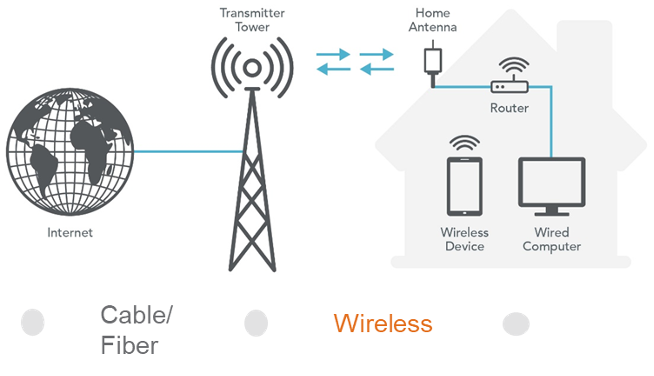
Fixed Wireless Access Schematic Diagrams
……………………………………………………………………………………………………………………………………………………………
Demand-side drivers:
-
Rising demand for high‑speed home and enterprise broadband, including video streaming, gaming, and cloud/SaaS, in areas poorly served by DSL or legacy cable.
-
Customer appetite for quick‑install, no‑truck‑roll broadband that can be activated using wireless CPE instead of waiting for fiber construction.
-
Growing need for reliable connectivity for remote work, distance learning, and SME digitization, especially in suburban and rural regions.
Supply-side / operator economics:
-
Ability to leverage existing 4G LTE macro grids and sub‑6 GHz spectrum, with incremental capex mainly in CPE and software rather than full new access builds.
-
Refarming of LTE spectrum and overlay of 5G NR on the same bands allows operators to run both mobile broadband and FWA on a common RAN/core.
-
Attractive ROI relative to fiber in low‑density areas, since one macro site at sub‑6 GHz can cover large rural or ex‑urban footprints.
Technology and spectrum factors (4G & sub‑6 GHz 5G):
-
4G LTE coverage ubiquity: years of investment mean LTE already reaches most urban, suburban, and many rural markets, making LTE‑FWA immediately deployable.
-
Sub‑6 GHz 5G propagation: better penetration through buildings and walls than higher bands, enabling more reliable indoor FWA without extensive outdoor CPE alignment.
-
Massive MIMO and beamforming on sub‑6 GHz bands increase sector capacity and improve non‑line‑of‑sight performance, which is critical for FWA quality at cell edge.
Competitive and regulatory drivers:
-
Mobile operators using FWA to attack cable and DSL bases; in several markets FWA contributes a high share of net broadband additions, pressuring incumbents on price and speed.
-
Government rural‑broadband programs and subsidies (e.g., U.S. RDOF‑type initiatives) encourage use of FWA as a cost‑effective tool to close the digital divide.
-
Regulatory allocation of additional mid‑band and sub‑6 GHz spectrum (e.g., 3–4 GHz bands) increases usable capacity and supports scaling FWA to millions of homes.
Market growth indicators:
-
FWA market value is growing at double‑digit CAGRs, with 4G still a large share today but 5G FWA projected to dominate new subscriptions by the late 2020s.
-
Sub‑6 GHz FWA gateways and CPE are a rapidly expanding device segment, driven by operator deployments targeting residential and SME broadband.
…………………………………………………………………………………………………………………………………………………………………….
References:
https://www.delloro.com/news/fwa-infrastructure-and-cpe-spending-will-remain-above-10-billion-annually-through-2029/
Fiber and Fixed Wireless Access are the fastest growing fixed broadband technologies in the OECD
Ookla: FWA Speed Test Results for big 3 U.S. Carriers & Wireless Connectivity Performance at Busy Airports
Point Topic: Global Broadband Subscribers in Q2 2025: 5G FWA, DSL, satellite and FTTP
Aviat Networks and Intracom Telecom partner to deliver 5G mmWave FWA in North America
T-Mobile’s growth trajectory increases: 5G FWA, Metronet acquisition and MVNO deals with Charter & Comcast
Dell’Oro: 4G and 5G FWA revenue grew 7% in 2024; MRFR: FWA worth $182.27B by 2032
Latest Ericsson Mobility Report talks up 5G SA networks and FWA
Highlights of Qualcomm 5G Fixed Wireless Access Platform Gen 3; FWA and Cisco converged mobile core network
Ericsson: Over 300 million Fixed Wireless Access (FWA) connections by 2028
New Street Research study: Cable broadband will continue its decline, but total broadband access subscribers will increase
A recent New Street Research broadband trends study suggests that U.S. cablecos (previously called MSOs) aren’t likely to increase the net number of broadband internet subscribers during this decade, but their broadband losses are expected to decrease. The financial market research firm doesn’t anticipate cable broadband subscriber growth to be positive for at least another four to five years. Under New Street’s “base case,” cable broadband net adds will remain negative each year until 2030. Cable broadband is facing fierce competition on the high end from fiber to the premises (e.g. AT&T, Frontier/Verizon) and on the lower end from 5G FWA (e.g. T-MobileUS, Verizon).
Cable “is the new copper,” New Street Research analysts David Barden and Vikash Harlalka wrote, implying declining subscribers for xDSL based broadband will also happen to cablecos. Obviously, cablecos won’t like that characterization given that their hybrid fiber/coax (HFC) networks are mostly comprised of fiber. However, declining subscriber trends is not a commentary about the cable industry’s underlying broadband access network technology.
“While we expect cable losses to improve over time, we never have cable adds in aggregate turning positive,” New Street analysts David Barden and Vikash Harlalka wrote in a Tuesday report. “We think most investors agree with us and are not modeling positive subscriber growth for any of the large cable operators over the next 5 years.”
“With industry growth remaining below pre-pandemic levels and FWA adds remaining strong, we don’t expect Cable to grow subscribers this decade. Cable needs industry growth to improve and FWA adds to slow down to return to growth,” New Street’s analysts write in their 140-page report (subscribers only).
New Street outlines potential scenarios for how cable’s share of the broadband market will look by 2030:
-
Best case scenario – cable has 42% of the market as 84% of the market is divvied up between cable and fiber, while FWA gets 16%.
-
Plausible scenario – cable retains 32% share of the broadband market, with 80% of it being shared with fiber, and FWA capturing 20%.
-
Optimistic scenario – cable captures 50% of the broadband market, fueled by “superior marketing and cheaper mobile bundles,” compared to fiber (41%) and FWA (10%).
New Street expects cable’s “steady state terminal market share” to be just a bit higher than 40% across its footprint, down from 62% today.
The report also takes a look at how cable will fare in markets that overlap with fiber. New Street estimates that 75% of cable markets will have a fiber competitor in the years to come. When combining non-fiber and fiber markets, cable is expected to capture about 41% of the share in their footprints. That compares to fiber (34%), FWA (20%), DSL (2%) and satellite broadband (3%).
It only gets worse for cablecos, as their customer net promoter scores (NPS) [1.] are lower than their competitors (mostly telcos). Using data from Recon Analytics’ weekly survey of about 10,000 respondents, New Street’s study notes there’s a pronounced customer NPS gap for cable against its primary broadband rivals. Customer NPS scores from Comcast (2) and Charter (1) are just above water compared to Cox Communications (-1) and Optimum Communications (-8). Fiber providers are doing much better: AT&T Fiber (25), Verizon Fios (21), Frontier (17) and Lumen Fiber (1). FWA also holds a sizable customer NPS advantage: T-Mobile (31) and Verizon FWA (29).
Note 1. NPS is a customer loyalty metric that measures the likelihood of customers recommending a company to a friend or colleague, using a scale of \(0\)-\(10\). The score is calculated by subtracting the percentage of “detractors” (those who score \(0\)-\(6\)) from the percentage of “promoters” (those who score \(9\)-\(10\)), with “passives” (those who score \(7\)-\(8\)) not being factored into the final score. NPS is a single, easy-to-understand number that ranges from \(-100\) to \(+100\) and is used to gauge customer satisfaction and predict business growth. Customers are asked, “On a scale of \(0\)-\(10\), how likely are you to recommend [company] to a friend or colleague?”
…………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………..
Considering all types of broadband access, New Street expects total net U.S. broadband net adds of 1.6 million, up from the 1.2 million from an earlier estimate. Fueled by fiber and FWA, net broadband subscriber adds are expected to continue above that level through 2030.
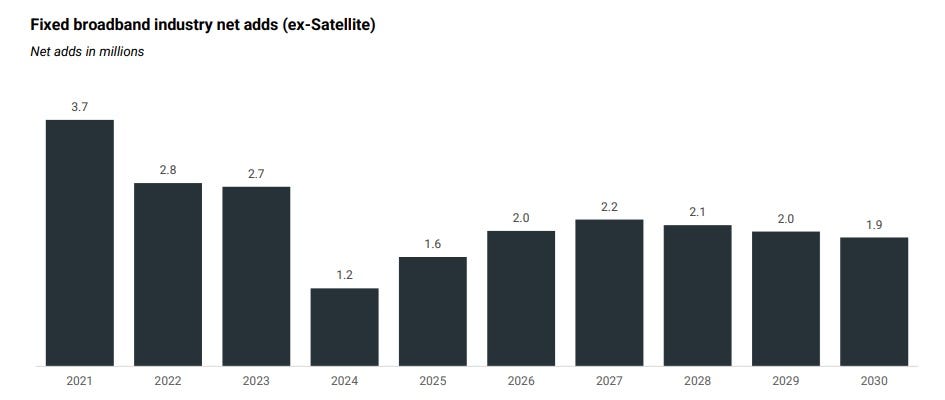
That growth will continue even as the market becomes increasingly saturated. New Street forecasts 139 million Internet households in 2030, up from 133 million at the end of 2025. Broadband penetration is expected to reach 93% by 2030, up from 87.7% at the end of 2025.
New Street expects U.S. network service providers to have 32 million to 36 million FWA subscribers in the coming years. However, the forecast expects a slight slowdown in FWA sub adds in 2026, coming in just below the range of 3.7 million to 3.8 million seen over the past three years. Next year, New Street expects FWA subscriber adds of 3.6 million (1.7 million for T-Mobile, 1 million for Verizon and 900,000 for AT&T). The analysts estimate that the carriers currently have enough capacity to support about 32 million FWA subs, estimating that carriers have already consumed about 55% of total capacity with new subs. That estimate does not include potential capacity coming from the upcoming auction of upper C-Band spectrum. That auction could provide capacity for another 4 million or so additional FWA subs, New Street said.
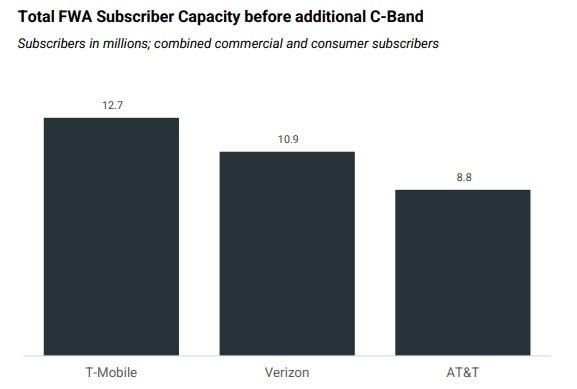
- Intense Competition: Cable operators are losing subscribers to FTTH, which offers faster speeds and higher reliability, and FWA services, which often appeal to customers seeking lower-priced or easily installed options.
- Market Saturation and Demographics: The broadband market is becoming increasingly saturated, and a slowdown in new household formation and people moving is curbing a key driver of new broadband connections.
- End of Government Subsidies: The expiration of government programs like the Affordable Connectivity Program (ACP) is impacting subscriber numbers, with major cable operators losing customers who relied on the subsidy.
- Network Upgrades: Cable companies are investing in network upgrades, such as DOCSIS 4.0, to improve speeds and performance, but it is not yet clear if these upgrades will significantly boost subscriber numbers.
Other Analyst Opinions:
- MoffettNathanson sees flattish cable broadband subscriber growth for the next couple of years, with a small gain in 2028. The firm projects subscriber losses in legacy markets will be eventually offset by gains from rural expansions and edge-out builds. “The conclusion for the two [Comcast and Charter] is about the same: even a near worst-case scenario yields roughly flat subscribership over the next five years or so,” Moffett wrote. “That’s a far cry from the doomsday scenarios we typically hear for the bear case.”
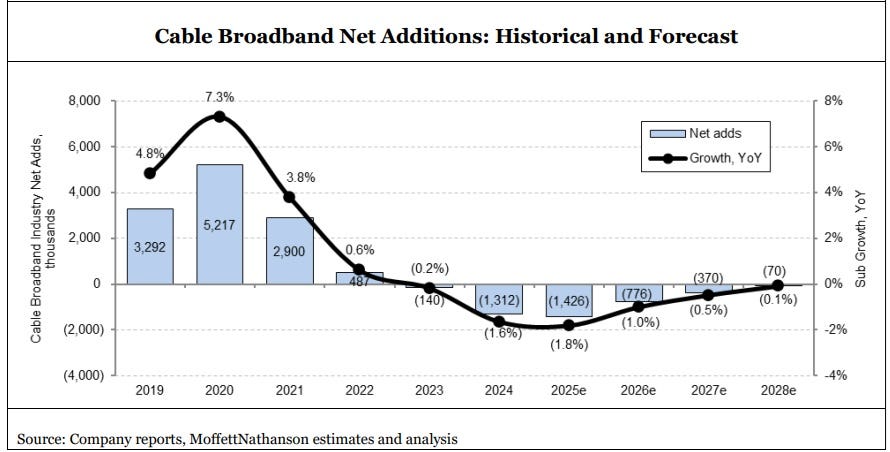
- In February 2025, Wolfe Research estimated that total industry net broadband additions for 2025 would be under 2 million, with cable providers bearing much of the slowdown.
- Grand View Research forecasts the global broadband services market (all connection types) to reach ~ US$ 875 billion by 2030, growing ~ 9.8% per year from 2025. In North America, broadband services revenue is expected to grow at ~ 8.3% CAGR from 2025 to 2030.
- Mordor Intelligence forecasts that the global market for hybrid-fiber coaxial (HFC — the backbone for many cable networks) will grow a 7.6% CAGR from $14.96 billion in 2025 to ~ $21.58 billion in 2030.
- An Ericsson analysis noted a projected decline of around 150 million DSL and cable connections globally between 2024 and 2030, with most growth coming from fiber, FWA, and satellite.
References:
https://www.lightreading.com/cable-technology/ouch-broadband-study-casts-cable-as-the-new-copper-
https://www.lightreading.com/cable-technology/cable-broadband-faces-a-flat-future-not-doomsday
https://telcomagazine.com/top10/top-10-global-fxxt-companies-in-telecoms
https://broadbandbreakfast.com/cable-unlikely-to-grow-subscribers-this-decade-new-street/
Highlights of 2025 Broadband Nation Expo: Comcast, T-Mobile keynotes + selected quotes
Dell’Oro: Abysmal revenue results continue: Ethernet Campus Switch and Worldwide Telecom Equipment + Telco Convergence Moves to Counter Cable Broadband
Cable broadband subscriber growth slows while FTTx and FWA gain ground
Aviat Networks and Intracom Telecom partner to deliver 5G mmWave FWA in North America
Aviat Networks, a wireless transport and access company, today announced a partnership with Intracom Telecom, a global technology systems and solutions provider, to deliver Fixed Wireless Access (FWA) technology using high-capacity 28 and 39 GHz millimeter wave (mmWave) bands, conforming to FCC requirements for mmWave bands intended for 5G use.
Aviat will initially focus on select North American service providers to address the growing need for multi-Gigabit consumer and enterprise 5G use cases as an alternative to the high cost, delays and complexity of using fiber, but with fiber-like performance. In addition, Aviat will offer software solutions along with a comprehensive set of design, planning, deployment and support services thanks to its extensive presence in North America.
Intracom Telecom’s WiBAS G5 platform is the only commercially available point-to-multipoint FWA solution operating in the 28 and 39 GHz mmWave bands that can address the growing demand for high-capacity Fixed Wireless Access, cost effectively delivering over 22Gbps from the same base station site, using Multi-User MIMO and Hybrid Massive Beamforming, over distances of up to 5 miles and more.
“We are very excited at this significant opportunity to extend our wireless expertise to provide advanced mmWave FWA solutions,” Pete Smith, CEO of Aviat Networks said, “Wireless can be deployed rapidly and cost effectively, and is perfectly suited to support high speed connectivity combined with excellent reliability.”
“I am very proud of Intracom Telecom’s R&D team for creating a solution that sets a new benchmark for FWA. Through this strategic partnership with Aviat Networks, we’re excited to help U.S. operators accelerate broadband expansion and deliver a true multi-gigabit experience, and more, over wireless,” said Kartlos Edilashvili, CEO of Intracom Telecom.

Image Source: Aviat Networks
In the U.S., Verizon, AT&T, and T-Mobile (including UScellular‘s retail wireless operations) use 28 GHz and 39 GHz millimeter wave (mmWave) bands for 5G services in densely populated areas and venues. mmWave signal propagation characteristics limit range/coverage and have a high susceptibility to blockage by physical objects and weather. These limitations significantly increase deployment costs and constrain coverage to densely populated areas.
About Aviat Networks:
Aviat, based in Austin, TX, is a leading expert in wireless transport and access solutions and works to provide dependable products, services and support to its customers. With more than one million systems sold into 170 countries worldwide, communications service providers and private network operators including state/local government, utility, federal government and defense organizations trust Aviat with their critical applications. Coupled with a long history of microwave innovations, Aviat provides a comprehensive suite of localized professional and support services enabling customers to drastically simplify both their networks and their lives. For more than 70 years, the experts at Aviat have delivered high performance products, simplified operations, and the best overall customer experience. Aviat is headquartered in Austin, Texas. For more information, visit www.aviatnetworks.com or connect with Aviat Networks on LinkedIn and Facebook.
About Intracom Telecom:
Intracom Telecom is a global technology systems and solutions provider operating for over 45 years in the market. The company is the benchmark in fixed wireless access, and it successfully innovates in the wireless access & transmission field. Furthermore, the company offers a comprehensive software solutions portfolio and a complete range of ICT services. Intracom Telecom serves telecom operators, public authorities and large public and private enterprises. The Group maintains its own R&D and production facilities, operates subsidiaries worldwide and has been active in the North American market since 2001, through its subsidiary, Intracom Telecom USA, based in Atlanta, Georgia. The parent company is located in Athens, Greece. For more information, visit www.intracom-telecom.com
References:
T-Mobile’s growth trajectory increases: 5G FWA, Metronet acquisition and MVNO deals with Charter & Comcast
Dell’Oro: 4G and 5G FWA revenue grew 7% in 2024; MRFR: FWA worth $182.27B by 2032
Latest Ericsson Mobility Report talks up 5G SA networks and FWA
Aviat Sells TIP compliant 5G-Ready Disaggregated Transmission Network to Africell