Starlink
U.S. Fixed Broadband Market Outlook: Satellite, FWA, Fiber and Cable Face Changing Competitive Dynamics
Disclaimer: ChatGPT was used extensively to assist with research, technical and market analysis, and drafting of this article. The author independently conducted additional research and incorporated source material and quotations. He reviewed, edited, and fact-checked the final content and is 100% responsible for its accuracy.
Introduction:
The U.S. fixed broadband market is entering a period of significant competitive change as low-Earth-orbit (LEO) satellite broadband expands, cellular fixed wireless access (FWA) growth moderates, fiber-to-the-premises (FTTP) deployment continues, and cable operators face increasing subscriber losses. These developments are changing the competitive relationships among four principal broadband access technologies: satellite, cellular FWA, fiber and hybrid fiber-coaxial (HFC) cable.
A November 19, 2026 report by New Street Research, summarized in Light Reading’s article, Satellite Broadband to Capture Most Market Share from FWA – Report, provides an interesting assessment of these trends. The analysts expect satellite broadband to expand the addressable broadband market while capturing subscribers from existing providers, with cellular FWA experiencing the greatest competitive impact. “Satellite can do things wireline hasn’t been able to, and the take-up demonstrates there is latent demand out there we haven’t incorporated previously,” states the report authored by New Street Research analysts David Barden, Vikash Harlalka and Ryan Smith.
The report also raises a broader question: as fiber’s traditional source of subscriber growth diminishes and satellite capacity expands, will satellite broadband eventually take a meaningful share of the fiber market as well?
Satellite Broadband: Starlink Drives Market Expansion
LEO satellite broadband, led by SpaceX’s Starlink, is becoming an increasingly significant participant in the U.S. residential broadband market. Unlike traditional geostationary satellite systems, LEO constellations operate much closer to Earth, substantially reducing propagation delay and enabling more competitive broadband services.
New Street Research forecasts that Starlink’s U.S. subscriber base will increase from approximately 3 million at year-end 2025 to approximately 10 million by 2030. Its analysis also forecasts that satellite broadband will capture approximately 7% of the existing broadband market in its terminal state. “Satellite net adds have accelerated in recent quarters as Starlink has become a more viable product. We expect Satellite net adds to remain at current levels for the foreseeable future,” the analysts wrote.
The analysts expect satellite net additions to remain around current levels for the foreseeable future. They also believe satellite is expanding the overall addressable market by serving customers whose broadband requirements have not been adequately met by terrestrial providers.
New Street estimates that U.S. residential broadband subscriber growth reached 2.2% year-over-year in Q3 2026. Without satellite broadband additions, growth would have been only 1.6%.
These figures demonstrate that satellite is contributing to overall broadband market expansion, not simply redistributing existing subscribers among competing providers.
Nevertheless, satellite broadband is also a competitive substitute for terrestrial fixed broadband. Starlink can attract customers from cable, cellular FWA and, potentially, fiber providers, depending on local availability, service performance and pricing.
Its competitive position will depend heavily on continued constellation expansion, satellite throughput, spectrum availability, ground infrastructure, terminal costs and the economics of serving increasingly dense geographic markets.
Cellular FWA: Growth Continues but Subscriber Additions May Slow:
Cellular FWA has become an important alternative to wireline broadband, particularly in locations where fiber is unavailable or where customers prefer lower-cost service and simpler installation. T-Mobile, Verizon and AT&T have been the principal U.S. cellular FWA providers. Their services use 4G LTE and 5G radio access networks to deliver broadband connectivity to fixed residential locations.
According to New Street Research, combined FWA net additions have remained in the 3.6–3.9 million range annually over the past four years. However, the analysts report that additions are beginning to slow at T-Mobile and Verizon, with AT&T also believed to have reached peak net additions. New Street expects FWA subscriber growth to decelerate further for all three operators.
“FWA net adds have been in the 3.6-3.9MM range for the past 4 years. Both T-Mobile and Verizon adds have started to slow down with the latter showing this more acutely. AT&T continues to grow but we estimate it has reached peak net adds. We expect FWA net adds to continue slowing down for all 3 carriers from here,” states the report.
The belief that FWA is slowing runs counter to the narrative coming from some executives: “…on FWA, look, we’re seeing continued very strong momentum. So deceleration, et cetera, is not where we are,” T-Mobile CEO Srini Gopalan told analysts on the operator’s Q3 earnings call.
This forecast is significant because cellular FWA has benefited from relatively rapid deployment, attractive introductory pricing and the ability to use existing cellular network infrastructure. However, FWA capacity is constrained by available spectrum, radio resources, cell-site density and competing mobile traffic. As subscriber penetration increases, operators must balance fixed broadband demand against mobile network performance. Additional spectrum, network densification and improved radio efficiency can expand capacity, but they require further investment.
Satellite broadband could therefore become a stronger competitor to cellular FWA, particularly in rural and lower-density markets where terrestrial cellular capacity or coverage is constrained.
It remains important to distinguish subscriber additions from market share. Slower FWA net additions do not necessarily mean that FWA subscribers will migrate directly to satellite; some customers may instead choose fiber or cable, while satellite may also attract previously unserved households.
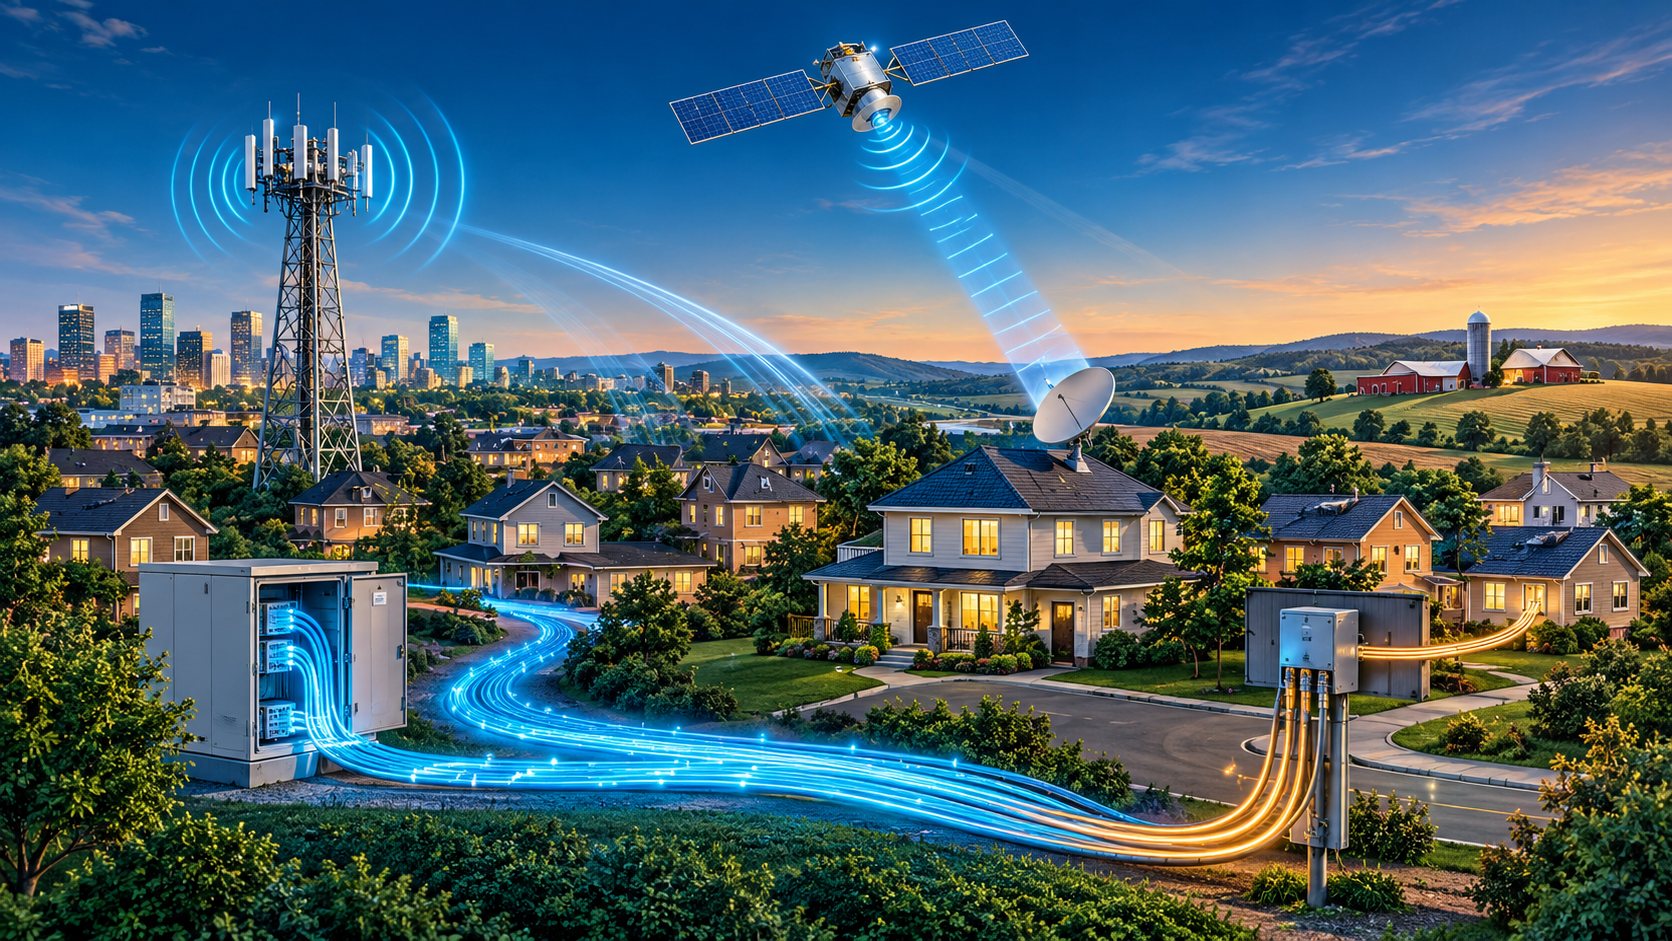
The evolving U.S. fixed broadband landscape: LEO satellite, cellular fixed wireless access (FWA), fiber-to-the-premises (FTTP), and hybrid fiber-coaxial (HFC) networks compete to deliver residential broadband connectivity. Image generated by ChatGPT.
Fiber Broadband: Strong Growth Through 2028, Followed by Deceleration:
Fiber broadband remains the strongest long-term fixed broadband access technology in terms of capacity, scalability, symmetrical bandwidth potential and low latency.
U.S. fiber deployments continue to expand, with telecommunications operators, independent fiber providers and municipal or cooperative networks extending FTTP coverage.
New Street Research expects fiber net additions to reach approximately 3 million in 2026, followed by 2.8–2.9 million annually in 2027 and 2028.
However, the analysts expect fiber net additions to decelerate thereafter as the pool of remaining DSL subscribers available for conversion approaches exhaustion.
They forecast that DSL subscriptions will be nearly zero by 2029. This removes an important source of relatively straightforward fiber subscriber growth: migrating customers from an operator’s legacy copper network to its own fiber infrastructure. As DSL converts to fiber decrease, the analysts also expect fiber net adds to reach a peak of 3 million in 2026 and remain in the 2.8 million-2.9 million range over the next two years “before decelerating thereafter,” according to the report. “We expect a deceleration in fiber net adds because DSL subs will be nearly zero by 2029 and an easy source of fiber net adds will disappear. Fiber operators will need to fight harder to find new subscribers,” the report said.
New Street says its long-term outlook does not expect satellite “to gain any share at the expense of fiber.” Consequently, fiber operators will increasingly need to compete for subscribers already served by cable, cellular FWA and other broadband providers. This represents an important change in the economics of fiber deployment and customer acquisition. Fiber providers will need to demonstrate sufficient advantages in bandwidth, reliability, latency and pricing to persuade customers to switch from existing broadband services.
Will Satellite Broadband Take Market Share From Fiber based Access?
New Street Research does not currently expect satellite broadband to gain market share at fiber’s expense. Instead, its forecast assigns the greatest competitive impact to cellular FWA.
That is a reasonable base-case assumption, particularly because fiber generally provides substantially higher capacity, lower latency, more consistent performance and better economics per delivered bit in densely populated markets.
However, it would be premature to conclude that satellite will not take market share from fiber.
LEO satellite broadband is not limited to customers who lack terrestrial broadband access. Customers in some suburban and exurban locations may consider satellite a viable alternative even when fiber is available, depending on service pricing, performance, installation costs and individual broadband requirements.
Furthermore, improvements in satellite capacity, spectral efficiency and terminal economics could expand the number of locations where satellite can compete effectively.
The geographic distribution of fiber and satellite capacity will be particularly important. Satellite can provide meaningful competition in lower-density markets where fiber deployment and maintenance are expensive, even if its nationwide share of broadband subscribers remains relatively modest.
The distinction is between aggregate market-share forecasts and actual competitive substitution in individual markets. Satellite can take customers from fiber in selected geographic markets without producing a significant change in nationwide fiber market share.
Accordingly, New Street’s forecast that satellite will primarily take share from FWA should be viewed as a projection rather than an established competitive outcome.
Cable Broadband: DOCSIS Upgrades Amid Subscriber Losses:
Cable operators continue to face competitive pressure from fiber, cellular FWA and satellite broadband. New Street Research reports that cable continues to lose market share, reflecting the increasing availability of alternative broadband technologies. Nevertheless, HFC networks remain important broadband infrastructure. Cable operators are investing in DOCSIS upgrades, including DOCSIS 4.0, to increase downstream and upstream capacity and extend the competitive life of their existing coaxial access networks.
DOCSIS 4.0 supports full-duplex and extended-spectrum approaches, with the potential for multi-gigabit downstream and upstream service capabilities. These upgrades allow cable operators to compete more effectively with fiber without replacing their entire HFC access infrastructure. However, technological improvements alone will not necessarily reverse subscriber losses. Cable operators must also address pricing, customer satisfaction, service reliability and the competitive advantages of fiber and wireless alternatives.
Satellite broadband could add another source of competitive pressure, especially in areas where cable is the principal terrestrial broadband alternative.
Technical and Economic Factors Determine the Competitive Outcome:
The four broadband technologies have different performance characteristics, deployment economics and capacity constraints.
| Technology | Principal advantages | Principal constraints |
|---|---|---|
| Fiber (FTTP) | High capacity, symmetrical bandwidth, low latency, scalability and reliability | High initial construction costs, permitting and deployment time |
| Cellular FWA | Rapid deployment, existing cellular infrastructure, flexible service offerings | Spectrum, cell capacity, radio conditions and mobile traffic competition |
| LEO satellite | Broad geographic coverage, rapid availability and service to remote locations | Shared satellite capacity, spectrum, terminal costs, latency and congestion |
| Cable (HFC) | Extensive existing footprint, high downstream capacity and DOCSIS upgrade path | Shared coaxial capacity, upstream limitations and competition from fiber |
An important technical consideration for LEO satellite broadband is that coverage does not necessarily equal unlimited service capacity.
Satellite throughput is shared among users within a service area. Actual performance depends on constellation size, satellite capacity, available spectrum, gateway infrastructure, spot-beam allocation and subscriber density.
Consequently, expanding the number of satellites does not automatically translate into proportional growth in the number of subscribers that can receive consistently high broadband speeds.
A technical assessment of LEO broadband prepared by Cartesian for the Fiber Broadband Association highlights these capacity and performance constraints. Its modeling, based primarily on public information available through November 2024 with minor updates in early 2025, estimates substantial limitations on the number of U.S. locations that Starlink could serve at the FCC’s 100 Mbps download/20 Mbps upload benchmark.
Those estimates should not be treated as current operational measurements or definitive forecasts, particularly given subsequent constellation developments. However, the underlying engineering constraint remains important: satellite capacity must be shared geographically, and concentrated demand can degrade user performance.
Fiber does not face the same last-mile radio spectrum and shared satellite beam constraints. This gives fiber a substantial long-term advantage in high-density markets and locations with significant bandwidth demand.
U.S. Fixed Broadband Market Outlook: 2027–2030:
The competitive outlook can be summarized as follows:
Satellite broadband: Continued expansion, led by Starlink, with increasing competition against terrestrial broadband providers. New Street expects satellite to capture approximately 7% of the existing broadband market in its terminal state, primarily at the expense of cellular FWA.
Cellular FWA: Continued subscriber growth, but with decelerating net additions as operators encounter capacity and market-penetration constraints. Additional spectrum and network investment could extend its growth potential.
Fiber: Strong subscriber additions through 2028, followed by slower growth as DSL conversion opportunities diminish. Fiber operators will increasingly compete for customers already served by other broadband technologies.
Cable/HFC: Continued market-share pressure from fiber, FWA and satellite, despite ongoing DOCSIS upgrades intended to improve network capacity and competitiveness.
The following table summarizes the directional outlook, rather than providing independently verified subscriber forecasts.
| Technology | 2027–2028 outlook | Longer-term direction |
|---|---|---|
| Satellite | Strong growth | Increasing competitive presence |
| Cellular FWA | Growth decelerates | Dependent on spectrum and capacity expansion |
| Fiber | Approximately 2.8–2.9M annual net adds | Deceleration after 2028 |
| Cable/HFC | Continued market-share pressure | DOCSIS upgrades support competitiveness |
| DSL/Copper | Continued subscriber decline | Nearly zero subscribers projected by 2029 |
Conclusions:
The U.S. fixed broadband market is becoming increasingly competitive as satellite, cellular FWA, fiber and cable technologies converge in their ability to deliver residential broadband services.
New Street Research’s forecast that satellite will take most of its market share from cellular FWA is plausible, particularly given the expected slowdown in FWA subscriber additions. However, the assumption that satellite will not take market share from fiber deserves further scrutiny.
Fiber should retain a substantial advantage in densely populated markets because of its capacity, low latency, reliability and scalability. But those advantages do not make it immune to competitive substitution in rural, exurban and selected suburban markets.
At the same time, the approaching exhaustion of DSL-to-fiber conversions will require fiber operators to compete more aggressively for subscribers already served by other broadband providers.
Ultimately, the competitive outcome will depend on the economics of delivering broadband capacity to individual geographic markets, rather than simply comparing nationwide subscriber totals.
The most important question is not whether satellite will replace fiber nationally, but how much of the addressable broadband market satellite can economically serve—and which terrestrial broadband providers will lose subscribers as that capability expands.
……………………………………………………………………………………………………………………………………………………………..
References:
https://fiberbroadband.org/resources/technical-assessment-of-leo-satellite-broadband/
https://www2.itif.org/2025-broadband-convergence.pdf
https://www.sec.gov/Archives/edgar/data/1181412/000162828026052515/earningsreleaseq22608042.htm
New Street Research study: Cable broadband will continue its decline, but total broadband access subscribers will increase
ABI Research joins the chorus: 5G FWA is a competitive alternative to wired broadband access
BroadbandNow Research: Best & Worst States for Broadband Access
U.S. broadband subscriber growth slowed in 1Q-2024 after net adds in 2023
FTTH was ~60% of France fixed broadband market in Q1-2023
Evaluating T-Mobile’s SuperBroadband – Has it Been a Commercial Success?
Disclaimer: Perplexity.ai & Google Gemini were used to research and help write this article.
……………………………………………………………………………………………………………..
Introduction:
What the evidence establishes:
| Commercial indicator | Public evidence | Assessment |
|---|---|---|
| Named customers | Launch coverage identified Aramark Destinations and Columbia Sportswear as customers. | Evidence of initial adoption, but not of deployment scale. |
| Continued customer engagement | October reporting identified Aramark Destinations and Aramark Nexus as customers and discussed their connectivity requirements. | More substantial than launch-day promotion alone, but without quantified contract value or installed-site counts. |
| Customer, site and revenue growth | The public materials reviewed do not establish a SuperBroadband-specific customer total, activated-site total, revenue figure or growth rate. | Insufficient evidence to judge commercial scale. |
| Profitability and retention | Those materials provide no product-specific margins, acquisition costs, renewal rates or churn figures. | Insufficient evidence to judge sustainable commercial success. |

+-----------------------------------------------------------------------+

|                       Distributed Enterprise Site                     |
|                                                                       |
|   +-----------------------+               +-----------------------+   |
|   |  T-Mobile FWA Node    |               |  Starlink LEO Dish    |   |
|   | (Primary Terrestrial) |               |  (Space-Based Backup) |   |
|   +-----------+-----------+               +-----------+-----------+   |
|               |                                       |               |
|               +-------------------+-------------------+               |
|                                   |                                   |
|                                   v                                   |
|                     +---------------------------+                     |
|                     | Ericsson Cradlepoint Edge |                     |
|                     | Router & Outdoor Adapters |                     |
|                     +-------------+-------------+                     |
|                                   |                                   |
|                                   v                                   |
|                     +---------------------------+                     |
|                     |   NetCloud Manager (LAN)  |                     |
|                     +---------------------------+                     |
+-----------------------------------------------------------------------+
- Edge Router Infrastructure:Ericsson serves as the lead infrastructure vendor, deploying enterprise-grade Cradlepoint routers and outdoor adapters. T-Mobile has also integrated Inseego and Cisco hardware platforms to scale deployment configuration choices.
- Satellite Endpoint: Every deployment includes a business-performance Starlink Phased-Array Satellite Kit professionally mounted and calibrated on-site.
- Management Engine: The dual connections terminate directly into the local router, which is monitored and managed via Ericsson Enterprise Wireless Solutions’ NetCloud Manager software platform.
- Traffic Flow Configurations: NetCloud software handles active traffic steering via two primary configurations based on enterprise requirements:
- Failover Mode: The local router treats the 5G Advanced FWA link as the primary data conduit. If the local router detects cell degradation, packet loss, or a link-down event, it reactively transfers active LAN traffic to the Starlink satellite leg.
- Load Balancing: Data streams are distributed across both the cellular and satellite paths simultaneously to manage peak bandwidth constraints and prioritize specific enterprise applications.
- Turnkey Deployment: T-Mobile manages the entire lifecycle, including custom site solution engineering, professional hardware mounting/cabling handled via field service partner Acuative, and automated provisioning.
- Centralized Visibility: Enterprise IT administrators retain full monitoring capabilities across all distributed endpoints using T-Mobile’s consolidated cloud dashboard, the T-Platform portal.
- The 99.99% Uptime Guarantee: SuperBroadband represents T-Mobile’s first wireless-first broadband tier backed by a contractually binding 99.99% uptime Service Level Agreement (SLA). If local link availability drops below this threshold, enterprise accounts receive an automated financial credit equivalent to 20% of the base monthly service cost.
- Commercial Tiers: Standard enterprise pricing structures start at $250 per month per site tied to a 36-month commitment. This base commercial fee includes unlimited primary 5G business data, standard Starlink backup data, all bundled router/satellite hardware kits, and ongoing 24/7 technical operations center monitoring.
Conclusions:
T-Mobile’s SuperBroadband has secured recognizable enterprise customers, but publicly available evidence does not yet establish meaningful deployment scale, revenue contribution or profitability. It is an early commercial foothold—not yet a demonstrated commercial success.
SpaceX Moves to Acquire Nationwide 800 MHz Spectrum for Starlink Mobile D2D Service
Introduction:
SpaceX announced an agreement on Thursday to acquire Grain Management’s nationwide 800 MHz spectrum portfolio, expanding the spectrum resources available for its Starlink Mobile direct satellite-to-device (D2D) service [1.]. The transaction would give SpaceX a low-band complement to its existing global 2 GHz mid-band spectrum holdings and strengthen its position as a potential competitor to established U.S. wireless operators. The agreement covers 100% of Space X’s nationwide 800 MHz spectrum portfolio. Financial terms were not disclosed, and the acquisition remains subject to Federal Communications Commission (FCC) approval.
Note 1. Starlink’s satellite connectivity plans extend beyond cellphones to broader direct-to-device end points. IoT support is explicitly part of its published roadmap; smartwatch support has yet to be confirmed for general capability. Starlink’s “Direct to Cell” branding describes a cellular satellite-access system, not a smartphone-only endpoint strategy. Starlink’s official Direct to Cell page states:
“In addition to expanding mobile coverage, Direct to Cell will enable ubiquitous Internet of Things (IoT) connectivity outside of terrestrial coverage, connecting millions of devices across critical global industries.”
………………………………………………………………………………………………………………………………………………………………
Low-band spectrum complements 2 GHz capacity:
The acquisition would add a coverage layer to Starlink Mobile’s spectrum strategy. While its existing 2 GHz spectrum is intended to support higher-bandwidth services, the 800 MHz portfolio would provide more favorable propagation characteristics, including improved penetration through obstacles such as foliage and building materials.
Those characteristics could help address signal attenuation—a significant constraint for satellite-to-smartphone connectivity. However, favorable low-band propagation should not be equated with assured indoor service; the announcement does not establish the coverage or performance that Starlink Mobile would deliver inside buildings.
The acquisition could expand SpaceX’s ability to provide mobile coverage from orbit, but it does not establish that the company intends to dispense with terrestrial infrastructure.
Regulatory approval and competitive implications:
Separately, the FCC approved Starlink Mobile’s Gen2 constellation application this week, according to the supplied Reuters report. That authorization permits SpaceX to launch 15,000 satellites optimized for operation in the 2 GHz band globally. The constellation authorization and the proposed 800 MHz acquisition are distinct regulatory matters: approval of the former does not constitute approval of the spectrum transaction.
Shares of T-Mobile US, Verizon and AT&T each fell more than 5% in extended trading today. The declines reflected investor concerns that SpaceX’s expansion into mobile connectivity could intensify price competition and pressure incumbent operators’ market share in the mature U.S. wireless market.
The strategic significance is the combination of additional low-band spectrum and an expanded satellite constellation. Whether those assets translate into a competitive alternative to terrestrial mobile networks will depend on regulatory approval and the coverage, capacity and service performance SpaceX ultimately delivers.
Technical implications: propagation, capacity and handset compatibility:
The engineering significance of the acquisition extends beyond improved signal penetration. Satellite-to-smartphone services must accommodate propagation distances far greater than those in terrestrial cellular networks, while maintaining reliable communication with ordinary handsets. Operating frequency, satellite altitude, antenna design and beam geometry therefore jointly determine the achievable coverage and service performance. Lower-frequency spectrum offers a useful propagation advantage, but it does not eliminate those system-level constraints.
Capacity is a separate issue. The description of 800 MHz as a coverage layer and 2 GHz as a capacity layer is a useful shorthand—not an intrinsic division between the two frequency bands. Available bandwidth and the ability to form and reuse satellite spot beams matter alongside propagation. Narrower beams can improve spatial isolation and help manage satellite-link impairments, but they require larger antennas; maintaining coverage with smaller beam footprints can also require more beams or additional satellites. Consequently, nationwide spectrum holdings should not be confused with nationwide terrestrial-equivalent capacity.
Satellite operation requires more than a compatible frequency band:
Direct-to-device systems must compensate for the propagation delay and Doppler shift associated with rapidly moving low-Earth-orbit satellites. In systems serving unmodified LTE smartphones, the network performs that compensation. Residual timing and frequency errors vary across the satellite beam and can disrupt initial access, while longer round-trip delays can reduce the efficiency of retransmission protocols. Low-band spectrum does not remove these protocol constraints.ericsson
Handset compatibility also requires a distinction between two approaches. Satellite systems using a conventional LTE air interface can serve existing smartphones in supported terrestrial cellular bands. By contrast, 3GPP Release 17 NR-NTN introduces satellite-specific capabilities, including handset-based timing and frequency compensation using the device’s location and satellite orbital information. These capabilities require compatible chipsets and devices; support for an 800 MHz cellular band alone does not establish support for NR-NTN. The spectrum acquisition therefore should not be characterized as a 5G NTN deployment without disclosure of the intended air interface and device requirements.ericsson
Nationwide spectrum helps—but does not eliminate interference constraints:
Nationwide exclusive access to terrestrial mobile spectrum can simplify satellite deployment by reducing domestic co-channel coexistence problems. However, satellite beams do not stop at national borders. Operations still require interference controls and coordination to protect terrestrial systems in neighboring countries. Depending on the authorization and deployment model, those controls can include geographic exclusion zones and restrictions on satellite transmission parameters.
Indoor Coverage is Highly Unlikely:
Improved propagation is an engineering advantage; reliable indoor service remains a performance claim that needs supporting specifications or measurements. The technical evidence instead emphasizes the interdependence of frequency, antenna design, satellite geometry and protocol behavior.
………………………………………………………………………………………………………………………………………………
Grain Management Backgrounder:
“For nearly twenty years, we have built Grain to see opportunity where others see complexity,” said David Grain, Founder and Chief Executive Officer of Grain Management. “Our spectrum expertise allows us to connect the strategic value of these assets with the technologies and operators that can realize their potential. This agreement with SpaceX brings that capability to bear at extraordinary scale, with the potential to change where and how Americans connect.”
Grain combines deep sector experience, strategic insight, and capital to unlock spectrum value, advance its productive use, and help operators meet evolving connectivity needs. Grain’s acquisition of the nationwide 800 MHz portfolio from T-Mobile in August 2026 extends that approach – the firm acquired the portfolio in exchange for cash and Grain’s 600MHz spectrum, then pursued multiple use cases that would expand connectivity for American consumers and create value for the industry, Grain’s investors, and the people whose futures they support.
“Spectrum is a finite resource with an expanding role in the economy,” Grain added. “As terrestrial and space-based networks converge, we see a new horizon globally for our spectrum strategy, building on our experience to address larger industry challenges and help shape the next generation of connectivity.”
…………………………………………………………………………………………………………………………………………………………
Separately, Space X today signed a fleet-wide deal with American Airlines to equip over 1,000 mainline aircraft with Starlink internet access. Starlink will bring fast, reliable Wi-Fi to customers throughout their journey, making it easier to stay connected from gate to gate. Whether responding to emails, catching up on messages, streaming favorite shows, browsing the web or keeping the family entertained, customers can enjoy a seamless online experience in the air.
“Our customers have told us that dependable connectivity can make a meaningful difference in how they spend their time in the air,” said American’s Chief Customer Officer Heather Garboden. “Whether they are livestreaming a favorite show, gaming, collaborating in real time on an important work deal, scrolling social media or online shopping, Starlink will give our customers countless options to make the most of their time while traveling. Just as importantly, it provides the foundation for future innovations that will further enhance the customer experience.”
“We’re thrilled to bring Starlink across American’s mainline fleet,” said Lauren Dreyer, Vice President of Starlink Business Operations at SpaceX. “Customers will have fast, reliable internet from gate to gate, whether they are streaming, working, or staying connected to family and friends throughout their travel.”
……………………………………………………………………………………………………………………………………………….
References:
Starlink Mobile: NTN–Terrestrial Convergence, Network Capacity, and the Limits of Disruption
FT: SpaceX considering Starlink Direct-to-Consumer mobile service & terrestrial cellular network infrastructure in the U.S.
Ookla: Starlink a viable competitor for hybrid 5G/NTN services due to network performance improvements and larger coverage area
Ookla: D2D satellite connectivity surged 24.5% during last 9 months; Starlink’s footprint expansion leads the way
US Mobile’s new bundle combines its multi-network mobile service with Starlink residential internet
Direct-to-Device (D2D) satellite network comparison: Starlink V2 (Starlink Mobile) vs “Satellite Connect Europe”
Blue Origin announces TeraWave – satellite internet rival for Starlink and Amazon Leo
China ITU filing to put ~200K satellites in low earth orbit while FCC authorizes 7.5K additional Starlink LEO satellites
Starlink doubles subscriber base; expands to to 42 new countries, territories & markets
Amazon Leo (formerly Project Kuiper) unveils satellite broadband for enterprises; Competitive analysis with Starlink
Starlink Mobile: NTN–Terrestrial Convergence, Network Capacity, and the Limits of Disruption
Executive Summary:
Elon Musk’s strategic objective for Starlink extends beyond satellite broadband connectivity for remote, maritime, aviation, and enterprise users. SpaceX is positioning Starlink for a broader role in mobile communications through an integrated non-terrestrial network (NTN) and terrestrial-network architecture. That strategy could combine direct-to-device (D2D) satellite connectivity, satellite backhaul, selected terrestrial access infrastructure, and potentially a retail mobile service.
Financial markets have treated that prospect seriously. Shares of U.S. wireless network operators have been under pressure since SpaceX President Gwynne Shotwell described the opportunity for “Starlink Mobile” as “huge,” in a CNBC interview on June 12th. On SpaceX’s recent earnings call, Shotwell characterized the U.S. wireless market as generating $600 billion in annual revenue and stated, “and I anticipate us to be able to acquire quite a few of their customers because I think our service will be better.”
Editor’s Note: The combined annual revenue of AT&T, Verizon, and T-Mobile is closer to $360 billion, depending on the reporting period and whether total revenue or service revenue is used.
The timing, service architecture, spectrum strategy, device ecosystem, and go-to-market model for a SpaceX mobile offering remain unresolved. A central distinction is needed: direct-to-device NTN service, satellite backhaul, a terrestrial radio access network (RAN), and a consumer mobile service are related but technically and commercially distinct propositions.
The most plausible medium-term outcome is not wholesale replacement of U.S. mobile network operators (MNOs), but deeper NTN–terrestrial integration. LEO satellite systems can extend coverage, improve resilience, support mobility, and connect underserved areas. Dense terrestrial networks retain structural advantages for high-traffic urban service, indoor coverage, and busy-hour mobile capacity.
“The perceived risk of Starlink Mobile disrupting the U.S. wireless industry is greater than the actual risk in the next one to two years,” says Morgan Stanley analyst Sean Diffley.
Starlink’s satellite-broadband business serves 12 million subscribers and reportedly generates profit margins above 60%. Musk’s ambitions, however, extend beyond connectivity for aircraft, ships, and remote fixed locations. SpaceX plans a large third-generation Starlink constellation, supported by the anticipated launch economics of its fully reusable Starship system. Starlink V3 satellites are expected to materially increase satellite capacity relative to earlier generations.
However, aggregate constellation capacity should not be equated with mobile-network capacity in dense urban markets. The relevant question is how much spectrum, beam capacity, spatial reuse, and backhaul capacity can be delivered to a given area during the busy hour.

Image Source: Facebook
…………………………………………………………………………………………………………………………………………………
Starlink Mobile could develop along four, potentially overlapping, paths:
The proposed Starlink Mobile service should therefore be assessed as an integrated network proposition, not as a simple satellite replacement for a nationwide cellular network.
Why Terrestrial Networks Retain an Advantage:
The central technical constraint is spatial/spectrum reuse. Terrestrial mobile networks deliver high area capacity by repeatedly reusing licensed spectrum across dense grids of macro cells, small cells, and indoor systems. Capacity is further increased through sectorization, advanced antenna systems, massive MIMO, carrier aggregation, and high-capacity fiber or microwave backhaul.
A LEO satellite system has different strengths. It can provide wide-area reach, support mobility, offer resilience during terrestrial outages, and extend coverage to regions where conventional network deployment is uneconomic. Yet its radio resources are shared across comparatively large beam footprints. This creates more demanding link-budget, capacity, and spectral-efficiency constraints in high-density areas, particularly for indoor service and busy-hour traffic.
Terrestrial-cell coverage areas vary considerably with spectrum band, terrain, urban morphology, antenna configuration, and load. Nevertheless, the architectural distinction remains: terrestrial networks achieve high capacity by spatially reusing spectrum over relatively small geographic areas, whereas satellite systems must manage shared capacity over much broader footprints.
For this reason, Starlink V3 satellites may substantially improve overall system capability without eliminating the terrestrial RAN advantage in dense urban and suburban markets. The strongest near-term use cases for NTN are likely to include coverage extension, emergency communications, maritime and aviation connectivity, mobility, IoT, selected backhaul, and service in remote or underserved locations.
3GPP’s NTN work is specifically directed toward integration with terrestrial cellular and wireline networks, reinforcing the view that NTN will develop as part of a broader communications architecture rather than wholly separate from it. Analyss opinions:
- Daiwa Capital Markets analyst Jonathan Kees similarly argues that Starlink is “only a complement, not a substitute” for existing wireless infrastructure.
- BofA Securities analyst Michael Funk reaches a comparable conclusion: “Existing direct-to-device satellite technology [is] underdeveloped and largely complementary to terrestrial mobile networks,” Funk says.
Spectrum, Capital, and AI:
SpaceX has acquired valuable spectrum assets through its EchoStar transactions. The FCC approved the transfer of approximately 65 MHz of spectrum to SpaceX for next-generation direct-to-device use. This is strategically important, but spectrum ownership alone does not establish a nationwide facilities-based mobile network.
A fourth nationwide MNO would require much more than spectrum. It would require:
-
Radio-access infrastructure, including macro sites, small cells, antennas, radios, and power.
-
High-capacity backhaul and transport networks.
-
Mobile core-network functions, service assurance, cybersecurity, and operational-support systems.
-
Device testing and certification, distribution, retail channels, billing, customer care, and subscriber-acquisition spending.
-
Sustained capital investment to expand coverage and capacity as traffic grows.
SpaceX must also finance Starlink V3 production, launches, constellation replenishment, gateways, ground infrastructure, and continuing development of D2D and NTN capabilities. At the same time, the company is investing heavily in AI infrastructure and Starship. Reported second-quarter capex exceeded $18 billion, including approximately $15.83 billion associated with AI infrastructure.
This does not establish that SpaceX lacks the financial capability to enter mobile communications. It does establish a major capital-allocation challenge. AI infrastructure requires rapid, front-loaded investment; terrestrial mobile networks require multi-year and geographically distributed deployment; and satellite systems require recurring capital expenditure for replenishment and capacity expansion.
—->Please see detailed discussion of this issue in Addendum below Conclusions subhead.
The key strategic risk is therefore prioritization. If AI, Starship, and satellite-constellation investment continue to absorb the majority of incremental capital, Starlink Mobile may progress more slowly as an independent terrestrial build. It may instead favor targeted terrestrial deployment, satellite-enabled backhaul, wholesale arrangements, or an MVNO model.
Starlink Coverage Issues as per Iain Morris of Light Reading:
Starlink is estimated to have between 3 and 4 million subscribers in the U.S., mostly in rural areas where there is no fixed or mobile alternative. That is, after all, why someone would opt for satellite broadband. But a small cell network built on the rooftops of these 3 to 4 million customers – or several times that amount – is not going to provide the mobile coverage demanded by anyone who even occasionally travels a few miles from home. And inside the building, what advantage would a Starlink cellular service have over Starlink-supported Wi-Fi?
SpaceX cannot possibly hope to address this coverage problem without some kind of physics-defying technological breakthrough. According to figures shared by an authoritative source on the telco side, a small cell might get you coverage about half a kilometer from the basestation, while a rural macro site would take you up to 20 kilometers from it. In urban areas where higher-frequency spectrum comes into play, this radius would probably fall to about 2 kilometers, making small cells look more competitive. The trouble there is Starlink’s lack of subscribers in cities.
Other estimates do not improve the outlook. William Webb, an academic and analyst who previously worked for UK telecom regulator Ofcom, thinks Starlink might be able to achieve a coverage radius of 1 to 2 kilometers with roof-mounted antennas, “assuming a reasonably high gain cellular antenna is integrated into the Starlink terminal and oriented correctly,” as he wrote in a LinkedIn update. But mounting below roof level would reduce the figure to less than 1 kilometer, according to Webb.
“The biggest issue will likely be that overall coverage will be patchy, concentrated in areas where there are the most Starlink broadband subscribers,” he said. “These are likely to be rural areas where fixed broadband provision is poor. As a result, coverage will likely be overlapping in rural communities but sparse outside of these areas.”
Commercial Models and Possible Partnerships:
SpaceX may determine that a fully independent nationwide mobile network is not the most efficient near-term approach. An MVNO arrangement would allow SpaceX to purchase terrestrial capacity at wholesale rates while offering a consumer service incorporating Starlink capabilities. Such a model could provide near-national coverage more rapidly, though it would reduce SpaceX’s control over network economics, service differentiation, and quality-of-service management.
Several Starlink Mobile outcomes are plausible:
Why would AT&T, Verizon, or T-Mobile enter an MVNO or deeper partnership with a prospective competitor? The answer may be competitive strategy. The first MNO to secure a commercially favorable relationship with SpaceX could gain a relative advantage in coverage, satellite integration, customer acquisition, or enterprise services.
SpaceX is “going to have to partner with one of the mobile network operators like a Verizon or T-Mobile,” says RBC Capital Markets analyst Ken Herbert. “They’re going to have to find ways to work with other companies.”
T-Mobile already has a direct-to-cell/device (D2D) relationship with SpaceX. Verizon’s FWA business is more directly exposed to fixed-broadband competition from Starlink, while AT&T, Verizon, and T-Mobile each possess extensive spectrum, RAN, transport, and customer-service assets that would be difficult and costly for a new nationwide entrant to replicate.
Evaluating Starlink/Spacex Deployment Plans:
Starlink’s satellite-broadband business serves 12 million subscribers and reportedly generates profit margins above 60%. Musk’s ambition, however, is substantially broader than providing internet access to aircraft and oceangoing vessels. SpaceX plans to deploy as many as 100,000 third-generation Starlink satellites, supported by the anticipated economics of its fully reusable Starship launch system. Starship remains in the test phase, but SpaceX has stated that it is designed to place up to 150 metric tons in orbit per launch at approximately one-tenth the per-kilogram cost of Falcon 9. Starlink V3 satellites are expected to provide roughly 10 times the capacity of earlier-generation spacecraft.
SpaceX is advancing these plans at a time when the U.S. communications market is already experiencing cross-sector competitive convergence. Fifth-generation mobile technology enabled MNOs to expand fixed wireless access (FWA) offerings and compete more directly with cable operators for residential broadband customers. The resulting service bundles combine mobile subscriptions, home broadband, and, in some cases, video and value-added services. Cable operators, in turn, have expanded mobile offerings, generally using Wi-Fi offload, their extensive wireline footprints, and mobile virtual network operator (MVNO) arrangements with incumbent wireless carriers for wide-area cellular coverage.
This competitive equilibrium has modestly favored wireless operators, although neither sector has emerged unambiguously dominant. AT&T, for example, is expected to generate sales and earnings growth over the next several years, albeit below broader market growth rates. Comcast faces a more constrained outlook, with relatively flat expected revenue and earnings performance. The valuation gap reflects both differing growth expectations and the capital intensity of maintaining and upgrading nationwide communications infrastructure.
Wall Street has amplified concerns about SpaceX’s competitive impact. Early research coverage has broadly characterized the launch, satellite-connectivity, and artificial-intelligence company as a disruptive force. The average analyst price target for SpaceX stock is approximately $227, implying a valuation near $3 trillion—roughly five times the combined market capitalization of AT&T, Verizon, and T-Mobile.
The major U.S. MNOs also operate with substantial debt burdens. AT&T, Verizon, and T-Mobile collectively carry approximately $420 billion in net debt, against about $140 billion in expected 2026 EBITDA. “I would not for a second sleep easily if I had the investments that [wireless telecom providers] have, and the debt that they have, and Elon Musk working on a superweapon as it pertains to my business,” says Drew Cupps of Polen Capital.
Nevertheless, Starlink faces significant capital, engineering, and deployment challenges before it can offer a broadly substitutable mobile service. Daiwa Capital Markets analyst Jonathan Kees argues that the investment required to build a V3-based Starlink constellation capable of materially disrupting terrestrial operators is underestimated. He estimates that constellation deployment could require more than $100 billion, excluding investment associated with SpaceX’s AI initiatives. Starlink is “only a complement, not a substitute” for existing wireless infrastructure, says Kees.
The fundamental constraint is spatial reuse and capacity density. A terrestrial cell site can concentrate spectrum resources over a coverage area measured in a few square miles, while a LEO satellite beam may serve a much broader footprint. Satellite systems therefore face more difficult link-budget, capacity, and spectral-efficiency challenges in dense urban environments, particularly for indoor service and high-traffic applications. V3 satellites may substantially improve system capacity, but they do not eliminate the capacity advantage of dense terrestrial RAN deployments.
For that reason, BofA Securities analyst Michael Funk does not view SpaceX as an immediate, large-scale competitive threat to incumbent MNOs. While some projections assign LEO-based mobile services 15% to 35% of the U.S. telecommunications market, Funk regards those estimates as overly optimistic. “Existing direct-to-device satellite technology [is] underdeveloped and largely complementary to terrestrial mobile networks,” Funk says. That assessment is consistent with Starlink’s present international model, which emphasizes partnerships with mobile operators rather than wholesale replacement of their networks.
Conclusions:
Starlink Mobile is an important strategic development in the evolution of NTN–terrestrial convergence. It should not, however, be evaluated as a satellite-only replacement for nationwide cellular networks.
LEO systems can provide broad-area reach, coverage extension, resilience, mobility, selected backhaul, and direct-to-device services. Dense terrestrial RAN infrastructure retains decisive advantages in spatial reuse, indoor coverage, spectrum utilization, and busy-hour capacity. Starlink’s most credible competitive impact in the near and medium term is therefore likely to occur in selected coverage, mobility, resilience, backhaul, and fixed-broadband segments—not through immediate replacement of nationwide terrestrial mobile networks.
The central uncertainty is which architecture and commercial model SpaceX will adopt. Its concurrent commitments to AI infrastructure, Starship, satellite replenishment, and spectrum assets may favor a hybrid or partnership-led approach over a fully independent nationwide MNO build.
In that outcome, incumbent operators’ spectrum, terrestrial RAN, fiber backhaul, tower infrastructure, customer relationships, and regulatory authorizations remain strategically important. Rather than becoming obsolete, those assets may increase in value as NTN and terrestrial networks become more tightly integrated.
If satellite and terrestrial systems become increasingly interdependent, incumbent operators’ assets may become more valuable rather than less. Spectrum, fiber backhaul, tower infrastructure, distributed RAN assets, customer relationships, billing systems, and regulatory authorizations remain essential elements of an integrated non-terrestrial network (NTN) and terrestrial-network ecosystem. EchoStar’s share-price appreciation over the past year illustrates the strategic value that spectrum holdings can command, particularly as SpaceX and AT&T acquire additional spectrum assets.
The three national U.S. wireless operators collectively hold spectrum assets estimated to be worth more than $400 billion based on recent transaction benchmarks. That figure is approximately 80% of their combined market capitalization and is broadly comparable to their aggregate debt burden. Spectrum holdings alone do not establish an investment thesis, but they provide a meaningful asset-value foundation as satellite, terrestrial, and hybrid connectivity models continue to evolve. They aren’t going to sell their spectrum. They have businesses to run, and those businesses are reasonably valued and growing.
Addendum: AI Capex is a Significant Risk for Starlink Mobile:
AI-data-center investment is a significant capital-allocation risk to Starlink Mobile, but it is not, by itself, evidence that SpaceX lacks the financial capacity to enter mobile communications. The more credible concern is that AI, Starship, constellation replenishment, and terrestrial mobile deployment will compete for capital simultaneously—potentially slowing Starlink Mobile’s rollout, limiting network densification, or increasing reliance on an MVNO partnership.
SpaceX’s capital spending has risen sharply: reported second-quarter capex exceeded $18 billion, including approximately $15.83 billion directed to AI infrastructure. Management indicated that similarly elevated capex could continue over subsequent quarters. Meanwhile, Starlink profitability and connectivity operations remain an important source of funding for the broader AI strategy.
A facilities-based mobile network would add another exceptionally capital-intensive program:
-
SpaceX has already committed approximately $19.6 billion through its EchoStar spectrum transactions for up to 65 MHz of spectrum, including associated debt obligations. Thus, the issue is not whether it can acquire any spectrum; it has already done so. The issue is whether that spectrum portfolio is sufficient for a competitive nationwide terrestrial-mobile network, particularly in high-density markets.reuters
-
A fourth nationwide MNO requires far more than spectrum: site acquisition, radios, antennas, power, backhaul, core-network functions, device certification, retail/distribution, customer care, and sustained subscriber-acquisition spending.
-
Starlink must also fund V3 satellite production, launch capacity, gateway infrastructure, constellation replenishment, and the evolution of direct-to-device/non-terrestrial-network capabilities.
These programs have distinctly different investment horizons. AI infrastructure requires rapid, front-loaded spending to secure compute capacity; terrestrial mobile networks require multi-year, geographically distributed capex; and satellite systems require continuous capital expenditure to maintain and upgrade orbital capacity.
The likely consequence is not cancellation of Starlink Mobile, but a more capital-disciplined architecture than a conventional nationwide greenfield MNO build. SpaceX has said it intends to build terrestrial mobile services but has not disclosed projected mobile capex or a site-count plan; analysts have warned that a competitive direct-to-consumer national offering would be very difficult without an MVNO agreement providing broad baseline coverage. This produces three plausible outcomes:
Satellite connectivity can reduce backhaul requirements at selected sites and enhance rural, maritime, aviation, emergency, and resilience use cases. It cannot economically substitute for dense terrestrial spectral reuse in the highest-traffic urban areas. Therefore, AI-related capex pressure is particularly relevant because Starlink Mobile needs substantial investment precisely where the satellite component provides the least complete replacement for terrestrial infrastructure.
A key additional risk is strategic prioritization, not immediate insolvency. If SpaceX continues allocating the overwhelming share of incremental capital to AI data centers and Starship, Starlink Mobile may emerge as a hybrid service, wholesale platform, or MVNO-enabled offering rather than a fully independent fourth nationwide carrier. That outcome would reduce the near- to medium-term disruption risk to AT&T, T-Mobile, and Verizon. It would also reinforce the more technically credible view that Starlink is likely to be complementary to terrestrial mobile networks for years, even if it becomes a powerful competitor in selected coverage, backhaul, and mobility segments.
……………………………………………………………………………………………………………………………………………………………..
References:
https://www.barrons.com/articles/spacex-wont-destroy-telecomit-will-just-reinvent-it-79b88d1a
https://www.lightreading.com/satellite/spacex-small-cell-plan-serves-up-more-musk-madness
FT: SpaceX considering Starlink Direct-to-Consumer mobile service & terrestrial cellular network infrastructure in the U.S. (See Comments below the article)
Ookla: Starlink a viable competitor for hybrid 5G/NTN services due to network performance improvements and larger coverage area
Ookla: D2D satellite connectivity surged 24.5% during last 9 months; Starlink’s footprint expansion leads the way
US Mobile’s new bundle combines its multi-network mobile service with Starlink residential internet
Direct-to-Device (D2D) satellite network comparison: Starlink V2 (Starlink Mobile) vs “Satellite Connect Europe”
Blue Origin announces TeraWave – satellite internet rival for Starlink and Amazon Leo
Eutelsat hails EC’s IRIS-2 project to take on U.S. NTN providers
Executive Summary:
The European Commission (EC) has announced the next steps for the IRIS2 [1.] project after reaching an implementation agreement with the prime contractors, one of which is Eutelsat. The EC agreed terms with the SpaceRISE consortium – comprising Eutelsat, Hispasat and SES – for deploying the satellite system, which includes adding 66 more low-Earth orbit (LEO) satellites dedicated to defense, security and emergency services, and launching services from 2029.
Note 1. IRIS² Backgrounder:
IRIS² is the European Union’s secure-connectivity LEO satellite program: Infrastructure for Resilience, Interconnectivity and Security by Satellite. It is intended to provide sovereign, resilient communications for EU governmental users while also supporting commercial broadband and connectivity in underserved areas. IRIS² is planned as a multi-orbit constellation of 290 satellites, principally in low-Earth orbit (LEO) and medium-Earth orbit (MEO). Combining LEO’s lower latency with MEO’s wider coverage is meant to support secure, high-availability communications across Europe and beyond.
IRIS² was established under Regulation (EU) 2023/588, the Union Secure Connectivity Programme for 2023–2027. The Commission awarded a 12-year concession in December 2024 to the SpaceRISE consortium—SES, Eutelsat, and Hispasat—with major European aerospace, satellite, and telecom companies participating as subcontractors.
The current planning cited by ESA anticipates first satellite launches in 2029, initial services in 2030, and full operations targeted for 2031. In the interim, initial governmental capability is to draw on pooled national satellite resources through GOVSATCOM.
IRIS² is commonly described as the EU’s third flagship space program after Galileo and Copernicus. Its strategic rationale is European digital and communications sovereignty: reducing reliance on non-European satellite systems, improving resilience against cyber and physical disruptions, and sustaining a European space/telecom industrial base. It is not simply a European retail satellite-internet competitor to Starlink; secure governmental connectivity and strategic autonomy are central design objectives.
A good part of the motivation to build the IRIS2 satellite system is to reduce reliance on U.S. satellites internet providers (e.g. Starlink, Amazon LEO), especially for sensitive military and government communications.
Principal uses of IRIS2 include:
-
Secure communications for EU institutions, Member States, defence/security users, embassies, and critical infrastructure.
-
Crisis management, disaster/humanitarian response, border or surveillance-related applications.
-
Broadband, transport connectivity, satellite trunking, and service in terrestrial coverage gaps.
-
Integration with 5G/non-terrestrial-network technology; the Commission’s 2026 terminal-industrialization call explicitly includes 5G NR NTN-compliant modem/baseband capabilities.
……………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………
Eutelsat CEO Jean-François Fallacher said this is “a very important milestone” that moves the project on from design and preparation to an “operational phase” and confirms Eutelsat’s role as the program’s “LEO lead.” Fallacher shared a high-level view of some of the system’s new technology that is hoped to give it an advantage over larger U.S. rivals. He said the multi-orbit MEO-LEO constellation is “very advanced,” and will have “much more” capacity than satellite internet provider OneWeb has today.
He also confirmed it will be based on 5G non-terrestrial network (NTN) standards, which is “important.”
“We use 5G NTN technology. For IRIS2, we want to normalize the technology … This is also a way to fight against the American giants because today each of the technology used by ourselves on OneWeb (now owned by Eutelsat), by Amazon or by Starlink are full proprietary technologies,” he said. “Going to normalized technologies such as 5G NTN will also help [in] bringing the cost down [and] having antennas which will be cheaper and of a smaller size.”
Eutelsat, which also operates 31 geostationary orbit (GEO) satellites, gained its LEO constellation with the acquisition of OneWeb in 2023. It is a distant second LEO operator with around 650 satellites, compared to Starlink’s more than 10,000. They both operate LEO constellations, but Eutelsat has a “fundamentally different constellation with different target customers, business models and scale.” LEO connectivity accounted for 25% of Eutelsat’s total revenue of €1.23 billion (US$1.41 billion) for the fiscal year ending June 30, and LEO revenue grew 70% year-over-year.
Photo Credit: HJBC/Alamy Stock Photo
………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………..
For IRIS2, Eutelsat will design and operate 264 dual Mil-Ka/Ku band and 66 Mil-Ka band satellites. The company said it will invest €2.23 billion ($2.57 billion) in the shared infrastructure and €1.16 billion ($1.34 billion) in the commercial infrastructure (which includes Ku payload and commercial ground equipment), with spending phased from 2027 to 2034. According to its concession agreement with the EC, the company said it expects revenue from IRIS2 activity to be more than €10 billion ($11.6 billion) from 2032 to 2040. The Ka-only satellites are planned to start launching in 2029, while the commercial Ku LEO system is expected to be operational by mid-2032. Eutelsat also said it plans to add 229 satellites to OneWeb through 2034 in addition to 440 new first-generation satellites for an investment of €1 billion ($1.2 billion).
https://www.lightreading.com/satellite/eutelsat-hails-5g-ntn-to-take-on-american-giants
European Consortium 5G NTN transmission paves the way for standards based direct to device (D2D) connectivity
Non-Terrestrial Networks (NTN) Tutorial: Architecture, Spectrum, and Technical Foundations
Non-Terrestrial Networks (NTNs): market, specifications & standards in 3GPP and ITU-R
ITU-R recommendation IMT-2020-SAT.SPECS from ITU-R WP 4B to be based on 3GPP 5G NR-NTN and IoT-NTN (from Release 17 & 18)
From LPWAN to Hybrid Networks: Satellite and NTN as Enablers of Enterprise IoT – Part 2
Telecoms.com’s survey: 5G NTNs to highlight service reliability and network redundancy
InterSAT extends Pan-African satellite services via Ku-band on Eutelsat 70B satellite
Orange France satellite Internet based on Eutelsat Konnect VHTS satellite
France’s Eutelsat nears deal to buy UK satellite internet company OneWeb
Analysis & Opinion: SpaceX to build, lease or buy a hybrid/terrestrial satellite network?
Should SpaceX’s Starlink build, lease/rent or buy a hybrid terrestrial/satellite mobile network or perhaps do it through a mix of these alternatives. Several industry watchers see an MVNO deal as the most likely path (we agree- see Analysis & Opinion below). That way SpaceX/Starlink can deliver reliable service indoors and out because it will have access to necessary low band and mid band spectrum, plus access to its own direct-to-device (D2D) service to cover areas out of reach of the terrestrial cellular network. Some analysts suggest that SpaceX might try to exchange some of its spectrum for an MVNO agreement, or perhaps come up with some other means to achieve that goal.
“Starlink is playing the long game. It will continue to negotiate, cajole, and, if necessary, coerce, in an effort to secure an MVNO agreement with one of the Big Three,” MoffettNathanson analyst Craig Moffett said in a recent report (subscribers only) that sized up SpaceX’s options. “It is clear, however, that the Big Three (AT&T, Verizon, T-Mobile) fully understand the clear and present danger that would be posed by Starlink’s market entry as another Cable-like hybrid MNO/MVNO.”
Image Credit: Stephen Searle/Alamy Stock Photos
……………………………………………………………………………………………………………………………………………………………………………………………….
A recent a Semafor report suggests the build and buy options are both being consdiered at SpaceX, kicking it off with a lead proclaiming that “Elon Musk is coming for your cell phone networks.” The report said SpaceX is seeking spectrum that can deliver service in “cities and dense areas,” and is exploring some options to get there that include acquiring companies that already own spectrum or obtaining spectrum at auction.
“In the most recent sign that Musk’s Starlink plans to compete directly with AT&T, Verizon, and T-Mobile. Musk’s SpaceX has taken other steps into the conventional telecommunications business. President Gwynne Shotwell demonstrated a prototype mobile handset to some investors earlier this year, the Wall Street Journal reported. The Financial Times also reported that Shotwell had expressed interest in building their own terrestrial networks.”
“SpaceX wants to grow its Starlink mobile business, which analysts expect to hit $15 billion in revenue this year and which SpaceX, in its IPO pitch to investors, pegged at a $740 billion market. SpaceX is working on new technologies to improve Starlink’s coverage in tree-covered areas and inside buildings, and Musk has also said he’s considered building a hybrid satellite-terrestrial network to bolster the service.”
Elon Musk has kept the door open for SpaceX to attempt a takeover of an MNO in the future. Whether any would be willing to sell is a completely different discussion.
- Roger Entner, analyst and founder at Recon Analytics, suggested that SpaceX’s fight over the upper C-band buildout rules indicates that it’s not shopping to acquire a wireless carrier. He said it shows that SpaceX “is a company that means to win spectrum at auction and build a satellite and terrestrial hybrid network on it from the ground up, the same way it built its own dish and its own router rather than buying either off a shelf.”
- “The key thing to look at is where SpaceX can exert pressure on the MNOs at minimal cost to itself. I expect we’ll see more rumors of a Starlink phone & cable partnership. Perhaps even a CBRS purchase from EchoStar. But strict buildout timetable now makes upper C-band unappealing,” Tim Farrar, principal at TMF Associates, explained on X.
The Semafor report notes that SpaceX’s plans are fluid, and the company could ultimately choose not to follow through. Building a network is capital intensive, requiring continuous, steady investment in both towers and spectrum —- drawing capital away from businesses that investors more richly reward, chiefly AI.
………………………………………………………………………………………………………………………………………………………………………………………..
Analysis and Opinion (aided by Perplexity.ai):
SpaceX is most likely to buy spectrum and selectively acquire/lease assets, rather then build a lean, satellite‑centric terrestrial layer — not buy a legacy carrier, and not build a Dish‑scale greenfield MNO.
This is a hybrid “buy‑then‑build” playbook: buy the airwaves (and maybe some small operators or tower portfolios) to secure optionality, then build only the terrestrial pieces that are economically justified, letting Starlink Direct‑to‑Device do the heavy lifting for coverage.
Why a pure “build” MNO is unlikely:
-
Capital allocation: SpaceX’s 2025 capex was already dominated by AI (~$18B in AI spend, with total near‑term IG funding needs around $300B before FCF turns positive). A full terrestrial MNO build would compete directly with that priority.
-
Strategic fit: SpaceX’s historical pattern is to design and build its own infrastructure, but only where it unlocks a new market or margin (rockets, satellites, user terminals). A retail MNO with dense tower grids and low ARPU is a different beast.
-
Regulatory reality: FCC rules for the EchoStar spectrum impose strict buildout and performance obligations, but they also allow blending space and ground infrastructure—exactly what a satellite‑first hybrid needs.
Why a pure “buy a carrier” is also unlikely:
-
No willing seller at the right price: Major carriers have rejected MVNO/wholesale overtures, and buying AT&T/T‑Mobile/Verizon is not realistic.
-
Asset mismatch: Legacy carriers come with large, costly tower grids and cost bases that a satellite‑terrestrial hybrid is designed to minimize.
The middle path: buy spectrum, build sparingly:
Evidence points to this as SpaceX’s actual strategy:
-
Spectrum first: The $17B EchoStar deal (AWS‑4, H‑Block, unpaired AWS‑3) gives SpaceX ~65 MHz of nationwide, exclusive, contiguous midband spectrum explicitly for direct‑to‑cell and hybrid services.
-
Auction strategy: SpaceX is expected to bid aggressively in the upcoming upper C‑band auction (3.98–4.14 GHz, 160 MHz) to secure urban capacity for a full‑service mobile offering.
-
Terrestrial as a complement: In dense areas, smartphones would connect to terrestrial base stations SpaceX plans to deploy; outside those zones, devices would switch to Starlink Direct‑to‑Cell. This keeps tower counts and capex manageable.
-
Selective M&A: Rather than buying a Big Three carrier, SpaceX is more likely to acquire spectrum‑rich smaller operators or lease/buy tower capacity where it accelerates coverage without a full build.
Bottom line:
SpaceX will almost certainly enter the U.S. mobile market as a hybrid operator, but the most capital‑efficient and strategically consistent route is:
-
Buy: spectrum (EchoStar + auctions) and possibly small, targeted assets.
-
Build: a lean terrestrial layer only where density and economics justify it, relying on satellites for the rest.
This balances a valid concern about AI’s capital pull with SpaceX’s clear intent to control the customer relationship and avoid being just a wholesale satellite internet operator.
……………………………………………………………………………………………………………………………………………………………………………………………….
References:
https://www.semafor.com/article/07/29/2026/spacex-looks-to-compete-with-the-carriers
FT: SpaceX considering Starlink Direct-to-Consumer mobile service & terrestrial cellular network infrastructure in the U.S.
Elon Musk: Starlink could become a global mobile carrier; 2 year timeframe for new smartphones
US Mobile’s new bundle combines its multi-network mobile service with Starlink residential internet
Direct-to-Device (D2D) satellite network comparison: Starlink V2 (Starlink Mobile) vs “Satellite Connect Europe”
U.S. BEAD overhaul to benefit Starlink/SpaceX at the expense of fiber broadband providers
FT: SpaceX considering Starlink Direct-to-Consumer mobile service & terrestrial cellular network infrastructure in the U.S.
According to the Financial Times (FT), SpaceX is evaluating a strategic expansion of its Starlink satellite Internet service to include a direct-to-consumer mobile service in the United States, a move that could materially disrupt the established U.S. mobile network market. According to sources familiar with recent IPO roadshow discussions, President and COO Gwynne Shotwell indicated that the company is considering both a retail Starlink mobile offering and the potential development of a terrestrial cellular network infrastructure.
Such a shift would represent a transition from SpaceX’s current wholesale and partnership-driven model—where Starlink satellite capacity is integrated with incumbent MNO networks—to a vertically integrated retail service directly competing with Verizon, AT&T, and T-Mobile. To date, Starlink’s U.S. mobility strategy has primarily relied on enabling partner operators, notably T-Mobile, to extend coverage in underserved and rural areas via satellite augmentation.
Although commercial terms remain undisclosed, industry analysts infer that Starlink currently participates in revenue-sharing arrangements tied to satellite-enabled service tiers. A direct retail model would enable SpaceX to capture a larger share of end-user revenue while reducing dependence on intermediary operators.
……………………………………………………………………………………………………………………………………………………………………………………………….
Here are some details, as reported by Reuters:
-
SpaceX already offers direct-to-cell connectivity with T-Mobile in the U.S., providing supplemental coverage from space to extend internet access to remote areas. [1.]
-
SpaceX is now considering launching a Starlink retail product and could build its own terrestrial U.S. mobile network, President Gwynne Shotwell told investors during a recent IPO roadshow, the FT report said, citing sources.
-
Reuters could not immediately verify the report. SpaceX did not immediately respond to a Reuters request for comment outside regular business hours.
-
In September last year, SpaceX bought wireless spectrum licenses from EchoStar for its Starlink satellite network for about $17 billion and then again for $2.6 billion in November, giving it the ability to quickly create a strong and affordable direct-to-cell service by using EchoStar’s wireless airwaves.
-
SpaceX will disrupt the $1.6 trillion U.S. communications industry as its satellite broadband unit Starlink expands, brokerage firm Oppenheimer said in a note earlier this month.
-
SpaceX’s record valuation is grounded in Starlink, which has over 10 million subscribers, and a launch business that analysts and investors say has transformed access to orbit.
Note 1. T-Mobile US D2D service has lower than expected usage:
During T-Mobile US’s recent earnings call, CEO Srini Gopalan admitted that just under a year after its commercial launch, T-Satellite is experiencing lower-than-predicted usage. However, he put a very positive spin on the situation, insisting that the technology is doing exactly what it was designed for.
“Our partnership with SpaceX is very strong. We’ve worked closely with them to really invent an entire category, and that’s been putting an end to dead zones. We’re pleased with that,” Gopalan said.
“Most of the usage we’re seeing is in national parks and if anything, courtesy of the great network Dr Saw has built, we’re seeing a lot less usage than we were originally thinking,” he admitted, referring to Chief Technology Officer John Saw. “But it’s a great complementary product.”
……………………………………………………………………………………………………………………………………………………………………………………………….
SpaceX Satellite Launch using Falcon 9 Rocket. Image Credit: Space Center Houston
This potential expansion follows SpaceX’s recent IPO, which has intensified investor expectations for accelerated revenue growth and diversification. Starlink already operates in more than 150 countries, delivering broadband services via LEO satellite constellations, with approximately 10.3 million global subscribers as of March. A U.S. mobile retail offering would significantly expand its addressable market beyond fixed satellite broadband.
Importantly, SpaceX has not publicly confirmed plans to launch a retail mobile service. However, speculation has increased following its $17 billion acquisition of wireless spectrum licenses from EchoStar in September, widely interpreted as a foundational step toward mobility services. In its bond prospectus, the company noted that while Starlink Mobile is currently expected “to be most impactful for customers in remote areas uncovered by terrestrial mobile networks,” its long-term positioning is more expansive, stating it would “compete to be the preferred connectivity experience to our customers no matter where they are located, whether in rural, suburban or urban areas.”
Despite the strategic rationale, significant technical and economic barriers remain. U.S. MNOs collectively control approximately 1,020 MHz of spectrum, compared to SpaceX’s estimated 65 MHz, according to New Street Research. This disparity highlights the challenges associated with scaling a competitive terrestrial mobile network, particularly in spectrum-constrained and highly saturated markets.
David Barden of New Street Research emphasized the difficulty of such an undertaking, noting that building a “wireless network in saturated markets around the world would be incredibly hard.” However, he added that “[But,] as a starting point for negotiating the best possible revenue-sharing deal with mobile network operator partners? It makes tremendous sense.”
Conclusions:
While a Starlink retail mobile service offering could redefine the company’s role in the telecom value chain, near-term implementation would likely require a hybrid model leveraging both satellite and terrestrial assets, alongside continued strategic partnerships with incumbent operators.
The most useful follow-on question is whether “terrestrial cellular network infrastructure” means acquiring spectrum, building or buying towers, or simply partnering for access and backhaul. If it means an owned network, the economics look very different from satellite direct-to-device: capital spend rises, time-to-scale slows, and the business starts competing head-on with Verizon, AT&T, and T-Mobile instead of complementing them. If it means a hybrid model, then the more plausible path is a bundled satellite-plus-terrestrial offering targeted at coverage gaps, mobility, and emergency connectivity rather than a nationwide full replacement.
The strategic significance of the FT report is not simply another Starlink service tier, but a possible shift from supplemental coverage provider to vertically integrated U.S. mobile operator, with major implications for spectrum policy, carrier competition, and infrastructure investment.
……………………………………………………………………………………………………………………………………….
References:
https://www.ft.com/content/42af0f15-3aa9-49b7-b429-4a39540af03e?syn-25a6b1a6=1 (paywall)
Ookla: Starlink a viable competitor for hybrid 5G/NTN services due to network performance improvements and larger coverage area
Ookla: D2D satellite connectivity surged 24.5% during last 9 months; Starlink’s footprint expansion leads the way
US Mobile’s new bundle combines its multi-network mobile service with Starlink residential internet
Tutorial: LEO Satellite Internet connectivity, D2D, and major providers
Direct-to-Device (D2D) satellite network comparison: Starlink V2 (Starlink Mobile) vs “Satellite Connect Europe”
Starlink doubles subscriber base; expands to to 42 new countries, territories & markets
Elon Musk: Starlink could become a global mobile carrier; 2 year timeframe for new smartphones
GEO satellite internet from HughesNet and Viasat can’t compete with LEO Starlink in speed or latency
U.S. BEAD overhaul to benefit Starlink/SpaceX at the expense of fiber broadband providers
Telstra selects SpaceX’s Starlink to bring Satellite-to-Mobile text messaging to its customers in Australia
SpaceX launches first set of Starlink satellites with direct-to-cell capabilities
Blue Origin announces TeraWave – satellite internet rival for Starlink and Amazon Leo
Tutorial: LEO Satellite Internet connectivity, D2D, and major providers
Satellite Orbits:
Satellite connectivity operates across three orbital tiers:
- Geostationary (GEO) satellites have been the dominant platform for decades, powering telecommunications, TV broadcasting, weather forecasting, military surveillance, rural internet, and satellite phones. Positioned 36,000 kilometres above the equator, a single GEO satellite covers nearly a third of the planet, but the distance creates a 500–700 millisecond signal delay that makes video calls and real-time services impractical. Each satellite is roughly the size of a school bus and requires its own rocket launch.
- Medium Earth Orbit (MEO) satellites sit between 2,000 and 36,000 kilometres above Earth’s surface, with a latency of 70–120 milliseconds. The satellites range from car-sized to van-sized, with a few deployable per launch. MEO satellites are used for GPS and other global navigation systems but have never played a significant role in consumer connectivity.
- Low Earth Orbit (LEO) satellites sit at just 300 to 2,000 kilometres above Earth’s surface, bringing latency down to 20–50 milliseconds — on par with home broadband. Their small, flat-panel design, roughly the size of a dining table, allows dozens to be stacked into a single rocket, significantly lowering the cost per satellite. Modern LEO constellations also link satellites directly via laser, forming a mesh network in space. Instead of every signal bouncing through a fixed ground gateway, data travels between satellites and descends at the nearest point, allowing LEO signals to reach oceans, disaster zones, and remote communities that no ground infrastructure will ever serve.
LEO satellites sit between 300 and 2,000 kilometres above Earth, completing an orbit every 90 to 120 minutes and covering different parts of the globe as they move. They communicate with ground stations or through inter-satellite links that relay data between satellites. Supporting infrastructure includes gateway stations, network operation centers, and data centers that manage satellite movements, route traffic, and maintain service reliability. For users, accessing LEO services requires a small satellite terminal — typically a dish — with power and a subscription plan. As shown in the figure below, users connect to a local Wi-Fi network linked to the dish. Data is transmitted to LEO satellites, relayed to a ground station, and then routed through fiber-optic networks to data centers or cloud platforms. The process is reversed for the return signal, completing the connection in milliseconds.
Importantly, LEO satellites are revolutionizing Direct-to-Device (D2D) communications by acting as cell towers in space, allowing standard, unmodified smartphones and IoT sensors to connect seamlessly without terrestrial infrastructure. By utilizing standard mobile-carrier spectrums or dedicated satellite bands, these fast-moving satellites bypass localized coverage gaps to provide ubiquitous, text, voice, and data services in remote, rural, and maritime areas, as well as critical backup during disasters.
LEO satellite internet functional block diagram:
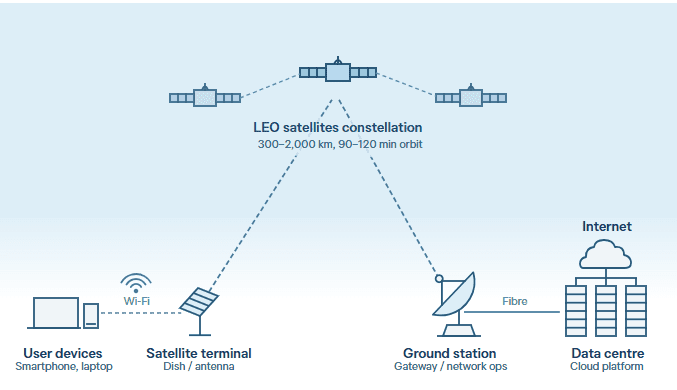
………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………….
Regulatory approval is central to LEO satellite deployment. Providers must typically obtain spectrum licenses, comply with national rules for ground infrastructure, and secure approval for service provision. Requirements vary widely across jurisdictions — from registration to multi-stage authorization processes. Competition from incumbent internet service providers may constrain market entry and expansion. As a result, services may be restricted or delayed even where technical coverage exists.
LEO connectivity also has practical limitations. Terminals require an unobstructed view of the sky, making installation easier in open areas but more difficult in dense urban environments where buildings or trees block the signal. Tropical downpours, heavy rain, or storms can cause signal attenuation and reduce throughput. Compared with terrestrial systems such as fibre-optic or mobile networks, LEO services may deliver less consistent performance, particularly in urban areas, and speeds can drop during peak demand.
Providers of LEO satellite connectivity:
The global space economy is projected to reach US$1.8 trillion by 2035, driven largely by LEO constellations. However, value creation is likely to be concentrated among a small number of providers controlling key parts of the value chain, Financial barriers to entry remain significant, varying depending on mission scope and technical ambition. Amazon Leo (formerly Project Kuiper) will cost more than US$10 billion, while full deployment of SpaceX’s Starlink is estimated at US $20–30 billion.
A mix of private and state-backed operators is developing LEO constellations with different strategies in satellite numbers, coverage, and target markets. Chinese-backed LEO operators GuoWang and Qianfan represent a strategic shift, both advancing rapidly towards full operation with a dual mandate of serving domestic communications and extending broadband connectivity across the Indo-Pacific and beyond. Their emergence could reshape strategic choices for governments in the region.
Where LEO satellite delivers:
LEO satellites are not a universal solution to connectivity gaps, nor a replacement for terrestrial networks. In most countries, fibre-optic and mobile infrastructure will remain the primary source of broadband connectivity. Their value lies in specific contexts: serving remote communities beyond the economic reach of terrestrial investment; providing resilient backup when ground networks fail; and supporting connectivity where no viable alternative exists.
LEO satellites are increasingly used to enhance resilience in countries with extensive fiber-optic networks or high exposure to natural disasters. They can provide automatic failover — near instantaneous transition to a standby system — during submarine cable outages, power failures, or other disruptions, maintaining communications and supporting emergency response. In December 2024, earthquakes in Vanuatu disrupted contact with national disaster authorities until Starlink was activated. In April 2025, a blackout in Spain and Portugal cut power to thousands of mobile towers, halving terrestrial network capacity — Starlink maintained connectivity via ground stations in Italy.
The main advantage is network independence: LEO satellites operate separately from terrestrial infrastructure and continue functioning when ground systems fail. Integrating LEO satellites into national disaster frameworks, rather than relying on ad hoc deployment, would maximize resilience.
………………………………………………………………………………………………………………………………………………………………………………………………………………….
References:
https://www.telecoms.com/satellite/satellite-disruption-how-leo-and-d2d-are-impacting-telecoms
Analyst firms wide forecasts for the LEO satellite direct-to-device (D2D) market
Analysis: SpaceX FCC filing to launch up to 1M LEO satellites for solar powered AI data centers in space
Blue Origin announces TeraWave – satellite internet rival for Starlink and Amazon Leo
Open Cosmos introduces global space-based LEO satellite service for IoT monitoring
China ITU filing to put ~200K satellites in low earth orbit while FCC authorizes 7.5K additional Starlink LEO satellites
Amazon Leo (formerly Project Kuiper) unveils satellite broadband for enterprises; Competitive analysis with Starlink
GEO satellite internet from HughesNet and Viasat can’t compete with LEO Starlink in speed or latency
Ookla: Starlink a viable competitor for hybrid 5G/NTN services due to network performance improvements and larger coverage area
SpaceX’s Starlink low-Earth orbit (LEO) satellite constellation providing high speed internet service is increasingly positioning itself as a scalable broadband access platform within the global telecom ecosystem. It now has growing relevance for both retail and enterprise connectivity use cases.
Network performance improvements (see below) have occurred alongside substantial subscriber growth. Starlink’s global user base expanded from approximately 4.6 million at the end of 2024 to over 10 million by early 2026, underscoring the LEO satellite platform’s ability to scale capacity while maintaining service quality.
This evolution is exemplified by T-Mobile’s “SuperBroadband” offering, which integrates 5G fixed wireless access (FWA) with Starlink satellite connectivity to deliver hybrid terrestrial–non-terrestrial network (NTN) solutions for business customers. The viability of such architectures is directly dependent on sustained improvements in satellite network throughput, latency, and service consistency.
Ookla Speedtest® data for the second half of 2025 indicates significant year-over-year improvements in Starlink’s performance across key network metrics. Median download speeds exceeded 100 Mbps in 49 states, compared to 23 states in 2H 2024, reflecting both increased system capacity and improved spectral efficiency. Performance gains were also observed across the lower quartile of users: 25th percentile download speeds improved in 48 states, with the number of states below 50 Mbps declining from eleven to two (Alaska and Florida). This shift indicates not only higher peak throughput but also improved quality of experience (QoE) consistency across the subscriber base.
Latency performance has also trended positively, driven by both constellation densification and architectural enhancements. While Starlink continues to target ~20 ms median latency, the number of states with median multi-server latency below 40 ms increased from one to ten between 2H 2024 and 1H 2025. By 2H 2025, top-performing regions—including New Jersey, Colorado, Arizona, and Washington, D.C.—achieved median latencies of approximately 37 ms, approaching parity with certain terrestrial broadband deployments and enabling latency-sensitive applications.
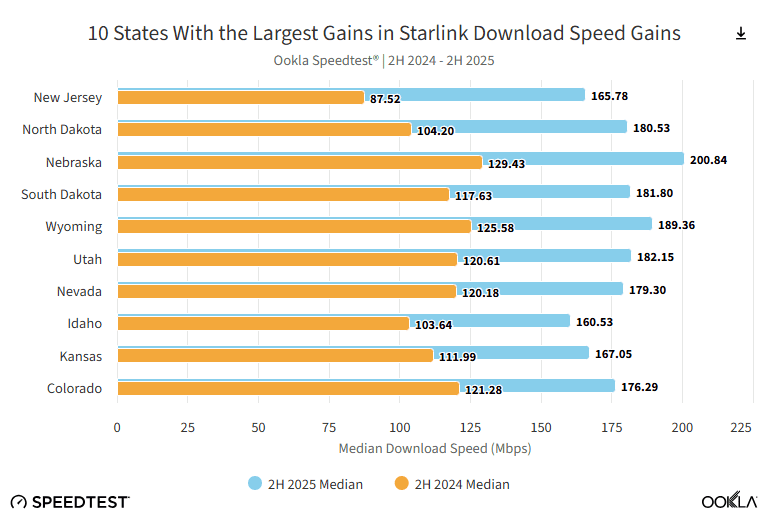
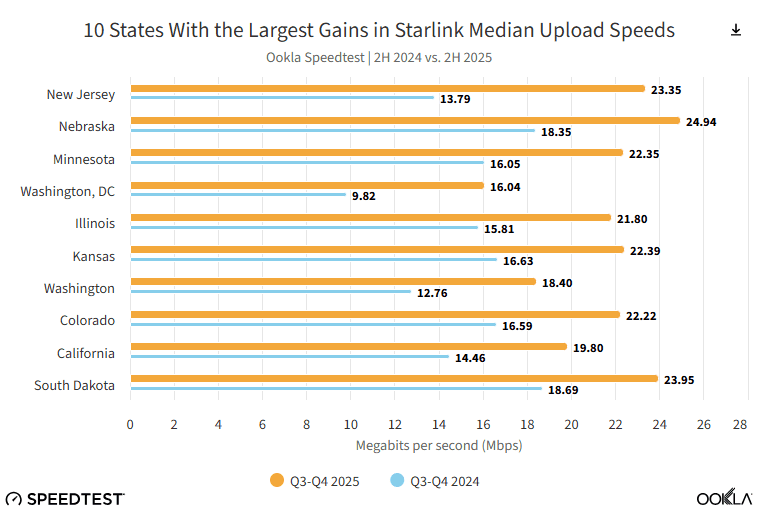
There has been a rapid expansion of the Starlink constellation and ongoing satellite technology upgrades. As of February 2026, the constellation exceeded 10,000 satellites in orbit, materially increasing aggregate network capacity and reducing cell congestion through greater spatial reuse. The deployment of Generation 3 (V3) satellites—featuring an order-of-magnitude increase (~10×) in downlink capacity relative to prior generations—has further enhanced throughput. Concurrently, upgrades to inter-satellite laser links have enabled more efficient space-based routing, reducing dependency on terrestrial gateway infrastructure, minimizing bottlenecks, and improving end-to-end latency performance.
Notably, these network enhancements have coincided with rapid subscriber growth. Starlink’s global user base expanded from approximately 4.6 million at year-end 2024 to over 10 million by early 2026, demonstrating the platform’s ability to scale capacity in line with demand while maintaining or improving key performance indicators.
Uplink performance has also improved materially, with 22 states achieving median upload speeds ≥20 Mbps in 2H 2025, compared to zero states in the prior-year period. This threshold is aligned with the FCC’s current broadband definition, underscoring Starlink’s increasing capability to meet regulatory benchmarks for two-way broadband services. Nebraska, New Jersey, and Minnesota recorded the largest gains, with Nebraska leading overall at 24.94 Mbps median upload throughput.
However, performance gains remain uneven across certain geographies. States including Connecticut, Hawaii, and New Hampshire exhibited relatively modest uplink improvements, suggesting localized constraints related to capacity allocation, gateway distribution, or demand density. These variances highlight the continued importance of targeted constellation scaling and ground segment optimization to ensure uniform service quality.
In Q4, 44.7% of Starlink’s user base achieved the FCC’s 100/20 Mbps broadband benchmark, signaling the provider’s transition from a niche rural solution to a high-performance market disruptor. By scaling its LEO constellation to over 10,000 nodes and deploying higher-throughput payloads, Starlink has successfully optimized spectral efficiency and reduced latency, maintaining QoS even as its global subscriber base scaled to 10 million.
While the U.S. remains Starlink’s primary market, the competitive landscape is shifting. Amazon’s Project Kuiper faces significant deployment headwinds; despite an FCC mandate to orbit 1,618 satellites by July 2026, the company has only deployed roughly 240 units and has petitioned for a two-year extension due to launch capacity constraints. This market penetration places legacy GEO operators like Hughesnet and Viasat at a strategic disadvantage. Although these incumbents are leveraging aggressive pricing and CPE (Customer Premises Equipment) refreshes to stem churn, the inherent latency limitations of GEO architecture continue to pose a significant structural barrier to competing with LEO-based performance.
Overall, the data indicates that Starlink is transitioning from a niche rural broadband solution toward a more robust, high-capacity access network capable of supporting hybrid 5G/NTN architectures and enterprise-grade connectivity services.
…………………………………………………………………………………………………………………………………………………………………………………………………………….
Addendum – LEO vs GEO satellite internet:
The technical architectures of Low Earth Orbit (LEO) and Geostationary Earth Orbit (GEO) systems are fundamentally defined by their orbital altitude, which dictates their latency, link budget, and network complexity.
- Orbital Mechanics and Altitude:
- GEO satellites reside at a fixed altitude of approximately 35,786 km. They orbit at the same speed as the Earth’s rotation, appearing stationary from the ground, which allows for simple, fixed-point antenna installations.
- LEO satellites operate at significantly lower altitudes, typically between 160 km and 2,000 km. Because they are closer to Earth, they must travel at much higher velocities (approx. 28,000 km/h) to maintain orbit, completing a full revolution in about 90–128 minutes.
- Latency and Propagation Delay:
- GEO: The extreme distance results in a high propagation delay, with a typical round-trip time (RTT) of 500–600 ms. This is unsuitable for real-time applications like VoIP, gaming, or high-frequency trading.
- LEO: Proximity to Earth reduces latency to 20–50 ms, making the performance comparable to terrestrial fiber.
- Link Budget and Power Requirements:
- GEO: High path loss over 36,000 km requires high-power Traveling Wave Tube Amplifiers (TWTAs) and large, high-gain satellite antennas to maintain signal integrity. However, the terminal transmit power required for low-bitrate applications can actually be lower than LEO due to the stable, optimized architecture of legacy GEO MSS systems.
- LEO: Lower path loss enables the use of lower-power RF systems. However, the rapid movement requires complex phased array antennas at the user terminal to electronically track satellites and manage seamless handoffs between nodes in the constellation.
- Network Resilience and Capacity:
- GEO: A single satellite can cover up to 42% of the Earth’s surface, but capacity is centralized; a single point of failure can impact an entire region.
- LEO: Resilience is achieved through distributed constellations of thousands of satellites. These systems often utilize Intersatellite Links (ISLs)—optical or RF mesh networks in space—to route data between satellites, reducing the need for local ground gateways.
| Feature | LEO Architecture | GEO Architecture |
|---|---|---|
| Altitude | 160 – 2,000 km | ~35,786 km |
| Latency (RTT) | 20 – 50 ms | 500 – 600 ms |
| Coverage | Regional/Global via large constellation | ~1/3 of Earth per satellite |
| Terminal Type | Advanced tracking/Phased array | Fixed parabolic dish |
| Operational Life | ~5 years (due to atmospheric drag) | ~15 years |
…………………………………………………………………………………………………………………………………………………………………………………………………………….
References:
https://www.ookla.com/articles/starlink-hits-new-us-highs
Ookla: D2D satellite connectivity surged 24.5% during last 9 months; Starlink’s footprint expansion leads the way
US Mobile’s new bundle combines its multi-network mobile service with Starlink residential internet
Starlink doubles subscriber base; expands to to 42 new countries, territories & markets
Elon Musk: Starlink could become a global mobile carrier; 2 year timeframe for new smartphones
Direct-to-Device (D2D) satellite network comparison: Starlink V2 (Starlink Mobile) vs “Satellite Connect Europe”
Blue Origin announces TeraWave – satellite internet rival for Starlink and Amazon Leo
Amazon Leo (formerly Project Kuiper) unveils satellite broadband for enterprises; Competitive analysis with Starlink
China ITU filing to put ~200K satellites in low earth orbit while FCC authorizes 7.5K additional Starlink LEO satellites
GEO satellite internet from HughesNet and Viasat can’t compete with LEO Starlink in speed or latency
Ookla: D2D satellite connectivity surged 24.5% during last 9 months; Starlink’s footprint expansion leads the way
Introduction:
Direct-to-device (D2D) satellite connectivity, primarily driven by Starlink deployments, continues to accelerate despite nascent market maturity. Ookla’s latest analysis reveals that while global D2D connections surged 24.5% from July 2025 to March 2026—spurred by Starlink’s expansion into Chile, Ukraine, Peru, and the UK—penetration among mobile subscribers remains under 1.5% in leading markets.
Starlink dominates D2D traffic, accounting for the bulk of connections alongside contributions from Skylo and Lynk Global. Initial use cases center on non-terrestrial network (NTN) extensions for SMS and geolocation in coverage gaps, with next-gen systems eyeing 5G NR integration via acquired spectrum like EchoStar’s holdings. Regional growth offset US/Canada dips, potentially tied to T-Mobile and Rogers introducing D2D surcharges amid seasonal patterns.

Image Credit: Ookla
Market Share Breakdown:

Adoption Barriers:
Terrestrial networks already blanket 96% of the global population per GSMA Intelligence, curbing urgency for D2D beyond edge cases. Low awareness and constrained throughput—versus 5G benchmarks—further limit uptake, though link budgets and multi-orbit architectures promise evolution.
Future Outlook:
Based on the February GSA (Global mobile Suppliers Association) report, Direct-to-Device (D2D) services have achieved commercial launch in 15 markets, with 61 countries currently in the evaluation, testing, or deployment phases of Non-Terrestrial Network (NTN) partnerships. Starlink dominates the landscape with 59 partnerships, followed by AST SpaceMobile at 28. In China—a market excluded from GSA data—ABI Research indicates that China Unicom and China Telecom are already leveraging the Tiantong GEO system for D2D. China Mobile is utilizing the BeiDou constellation while planning integrations with emerging LEO networks. To evolve from narrowband emergency services to full mobile broadband, all three Tier-1 operators are aligning with state-backed LEO mega-constellations, specifically Project Guowang and G60 Qianfan (Spacesail).
For Mobile Network Operators (MNOs), D2D integration significantly alters CAPEX/OPEX strategies. In rural or remote areas, MNOs must now run a cost-benefit analysis: deploy traditional macro sites or utilize satellite-based coverage to eliminate dead zones. While Starlink argues that D2D allows MNOs to reduce terrestrial investment, the technology is largely limited to outdoor environments. Given that approximately 80% of mobile traffic is generated indoors—where satellite link budgets typically fail—terrestrial densification remains critical.
From a regulatory standpoint, the rise of NTN-D2D complicates Universal Service Fund (USF) allocations. In the U.S., the FCC is currently assessing how the $9 billion 5G Fund for Rural America should account for D2D capabilities. Ultimately, while D2D may solve the “dead zone” problem for outdoor mobility, it serves as a complement to, rather than a replacement for, high-capacity terrestrial infrastructure. Enhanced spectrum harmonization and handset chipsets could pivot D2D from supplemental to resilient 5G NTN layer, challenging capex models for rural densification. Network operators must navigate billing handoffs and QoS parity to unlock scale.
References:
https://www.ookla.com/articles/measuring-the-direct-to-device-d2d-marketplace-2026
US Mobile’s new bundle combines its multi-network mobile service with Starlink residential internet
Analysis: Amazon <- Globalstar – a strategic move for D2D and spectrum parity
GSA: 5G Non Terrestrial Networks, 5G SA and 5G Advanced gain momentum
Direct-to-Device (D2D) satellite network comparison: Starlink V2 (Starlink Mobile) vs “Satellite Connect Europe”
Standards are the key requirement for telco/satellite integration: D2D and satellite-based mobile backhaul
Deutsche Telekom selects Iridium for NB-IoT direct-to-device (D2D) connectivity
MTN Consulting: Satellite network operators to focus on Direct-to-device (D2D), Internet of Things (IoT), and cloud-based services
Blue Origin announces TeraWave – satellite internet rival for Starlink and Amazon Leo
China ITU filing to put ~200K satellites in low earth orbit while FCC authorizes 7.5K additional Starlink LEO satellites
Starlink doubles subscriber base; expands to to 42 new countries, territories & markets
Amazon Leo (formerly Project Kuiper) unveils satellite broadband for enterprises; Competitive analysis with Starlink