5G Advanced
China Mobile and Huawei Turn High-Speed Railway 5G-A into a Premium Service
Introduction:
China Mobile may have found a credible way to monetize 5G which has been one of the most persistent commercial problems for mobile network operators. The China state backed carrier aims to turn a 5G Advanced network into a consumer service Chinese people will pay for. On China’s Beijing–Shanghai high-speed railway, where trains operate at up to 350 km/h, China Mobile and Huawei have deployed a 5G-Advanced (5G-A) [1.] architecture that goes beyond coverage and peak-rate claims. The network is designed to identify passengers travelling aboard the train, differentiate them from users located near the rail corridor, recognize application-level performance requirements, and allocate radio and core-network resources accordingly.
Note 1. 3GPP & ITU-R Standardization Status: 5G-Advanced, incorporating enhancements from 3GPP Release 18 (the initial 5G-Advanced baseline), was included in the latest revision of Recommendation ITU-R M.2150-3 [IMT 2020 RIT/SRITs], which was approved in February 2026 as the latest 5G RAN standard.
3GPP Release 19 carries the official 5G-Advanced logo and introduces a wide array of advanced features and functional enhancements that expand upon Release 18, but it has not yet been contributed to ITU-R WP5D. That’s because ATIS and other 3GPP organizational partners are aligning upcoming submission timelines around the broader IMT-2030 (6G) guidelines. Release 19 functions as a transitional bridge. Elements of Release 19, alongside upcoming Release 20 studies, are being packaged as part of the broader baseline evaluation requirements leading up to the major IMT-2030 tech proposal window
……………………………………………………………………………………………………………………………………………………………………
The commercial proposition is straightforward: China Mobile wants to sell a differentiated connectivity experience rather than simply another nominal speed tier.
China Mobile’s 5G-A High-Speed Rail Premium Package effectively creates a premium service class within the public mobile network. According to China Mobile and Huawei, subscribers can receive data rates two to three times higher than those available through standard packages, particularly for latency-sensitive and bandwidth-intensive services such as video conferencing, livestreaming, and cloud gaming.
That makes the Beijing–Shanghai deployment more than an ambitious coverage project. It is an effort to operationalize contextual, application-aware quality differentiation at consumer scale.
Reliable connectivity aboard a train moving at 350 km/h is inherently difficult. Devices traverse cells rapidly, driving frequent handovers, while large numbers of passengers compete for capacity within a highly challenging RF environment. A train carriage also presents substantial propagation constraints: passengers are concentrated in a metal enclosure, and demand tends to be synchronized around high-bandwidth applications.
China Mobile has deployed dedicated capacity along the route using 2.6-GHz 8T8R and 700-MHz spectrum within a three-carrier 5G-Advanced network. Neither band is inherently unique. U.S. operators, for example, use 700-MHz low-band spectrum and hold substantial spectrum near 2.5 GHz. The distinctive element is China Mobile’s integration of those bands into a dedicated high-speed rail mobility architecture, combined with AI-assisted passenger classification and service prioritization.
China Mobile says that multiband load balancing, carrier aggregation, and Huawei’s train-specific power-adaptation technology improved perceived uplink performance by 38.5% and downlink performance by 9.5%. Those figures are vendor- and operator-reported measurements, rather than independently verified results, but they illustrate the priority placed on uplink and experience consistency as well as headline downlink rates. More important than the additional radio capacity, however, is the control layer built above it.

China Mobile and Huawei use AI on the Beijing–Shanghai high-speed rail line to sell premium 5G service, turning network control into revenue. (Source: Google Gemini)
…………………………………………………………………………………………………………………………………………………………………………..
The network identifies the passenger context:
China Mobile says it has integrated AI inference into the 5G core’s Network Data Analytics Function, or NWDAF. The system evaluates approximately three minutes of user mobility data—including speed, base-station transitions, and network topology—to determine whether a subscriber is travelling aboard the high-speed train or simply using the public network in proximity to the railway.
China Mobile claims that the system identifies high-speed rail passengers with more than 95% accuracy. Once a user has been classified as a railway passenger, the network can modify frequency-selection priorities to retain that subscriber on dedicated rail capacity while moving conventional public-network users to alternative resources.
The operator says that, at typical base stations, as many as 60% of non-rail users can be migrated off the rail-focused network layer.
That changes the network’s role. Rather than simply transporting packets across available capacity, the system interprets user context and uses that inference to make policy decisions about radio and core-network resource allocation.
In practical terms, the network is attempting to distinguish between two users who may be physically close to one another but have very different connectivity requirements:
This is a more sophisticated model than conventional consumer traffic management. The policy is not based solely on a static premium plan or a generic QoS marking. It is informed by mobility context, location, network topology, and application behavior.
From capacity to application experience:
China Mobile says its NWDAF can detect deteriorating application performance and dynamically establish dedicated guaranteed-bit-rate bearers for eligible subscribers and services.
In 2025, the company said the system could accelerate 27 applications across five categories. It now says that capability has expanded to 55 applications in six categories, including multistream acceleration for short-form video and livestreaming services.
Intelligent processing within the radio network adds a further control layer. China Mobile and Huawei describe millisecond-level optimization of rate, latency, power, and carrier selection for specific users and services.
The result begins to resemble an intelligent service-delivery platform rather than a conventional mobile broadband network.
That distinction matters because mobile operators have spent years seeking a viable monetization model for 5G capabilities such as network slicing, deterministic performance, differentiated QoS, and application-aware service delivery. Selling another increment of nominal speed to a subscriber who can already stream video without difficulty is not especially compelling. Selling a reliable, business-grade experience for a video meeting during a high-speed journey between Beijing and Shanghai is easier to understand—and potentially easier to monetize.
One proposition is additional bandwidth. The other is confidence that an important application will work when it matters.
China Mobile’s service branding reinforces that distinction. Premium subscribers receive a dynamic China Mobile HSR VIP logo on their devices, making the service tier visible as well as functional.
Why rail is a useful proving ground:
Railway environments are particularly suitable for testing this model because the value of performance differentiation is immediately apparent. A passenger trying to participate in a video conference, upload files, livestream, or access a cloud application does not particularly care whether the underlying network is branded as 5G, 5G-Advanced, or eventually 6G. The relevant question is whether the service works reliably.
That is why the Beijing–Shanghai deployment may have significance beyond China.
In the United Kingdom, Ofcom reported in June that mobile service was poor in between 58% and 83% of train tests, depending on the operator. Its benchmark for a good connection was modest: 5 Mbit/s downlink, 1.5 Mbit/s uplink, and latency of no more than 50 milliseconds—sufficient for an acceptable video call. Ofcom reported in June that those conditions frequently were not met.
China Mobile is using AI to determine which passenger’s video call should receive priority. Britain is still working to ensure that the connection is available at all.
London provides an instructive counterpoint. The Elizabeth line initially opened without mobile coverage. Transport for London now says that all Elizabeth line stations have 4G coverage and tunnel sections have both 4G and 5G coverage. The lesson is not that advanced, differentiated services are unnecessary. It is that the industry must first solve the basic infrastructure problem before it can credibly commercialize higher-value connectivity tiers.
China Mobile has moved beyond that initial engineering threshold. Its question is: what services become commercially viable once connectivity is reliable enough to manage and differentiate?
A broader 5G monetization model:
A search for comparable deployments did not identify another commercial rail service that combines 5G-Advanced, AI-based passenger identification, application-level performance detection, and premium consumer service differentiation in quite the same way.
Other railway initiatives are progressing, but generally toward a different goal. Germany, for example, is testing 5G standalone for railway communications, with an emphasis on the Future Railway Mobile Communication System, or FRMCS. In 2025, Deutsche Bahn began testing what Fierce Network described as the world’s first 5G-based FRMCS deployment on live outdoor tracks. The trial is focused on establishing next-generation railway communications capabilities.
The contrast is useful as per this table:
Both are valid applications of 5G. They address different buyers, operating models, and value chains.
Mobile operators have historically sold relatively blunt consumer products: minutes, messages, data allowances, and broad speed tiers. Fifth-generation networks promised more precise commercial tools, including slicing, service assurance, policy control, and differentiated quality. Translating those tools into consumer propositions has proved difficult, although the model has been more successful in industrial and enterprise deployments.
I saw one version of that industrial model at the East-West Gate intermodal terminal in Hungary, where Huawei private 5G provides the uplink capacity, reliability, and guaranteed latency required to automate railway logistics. The Beijing–Shanghai deployment applies a related technical proposition to a very different customer: the passenger.
That makes 5G’s consumer value proposition more tangible.
Huawei’s responses to FNTV’s questions on the case study are revealing. Additional spectrum and capacity establish the baseline experience; AI-based profiling and intelligent radio processing then provide the fine-grained resource management that improves it. Put simply: capacity creates the network, while control creates the product.
That distinction will become more important as operators seek to prevent connectivity from becoming a commodity.
Hyperscale cloud providers built highly profitable businesses in part by layering proprietary software, orchestration, and operational control above broadly available infrastructure. Telecom operators own valuable assets—licensed spectrum, radio access networks, transport, core networks, and increasingly distributed compute—but have struggled to translate those assets into differentiated, higher-margin services.
An intelligent mobile network provides a potential route forward.
T-Mobile has described a related direction in its own 5G standalone evolution, with AI moving from the cloud into the core and orchestration extending across core, radio, and device layers. T-Mobile executives described how AI is moving into its 5G standalone core. The underlying principle is similar: as operators gain more real-time intelligence and control across network domains, they can potentially tailor network behavior to individual customers, devices, applications, and contexts.
The operator owns the spectrum, operates the RAN, and controls the core. Increasingly, software and AI can determine how those assets behave for a particular subscriber or service. That control may have commercial value.
The commercial test remains ahead:
The deployment still raises important questions. The performance data supplied to FNTV are China Mobile and Huawei measurements and have not been independently verified. More significantly, the ultimate test is commercial: will subscribers consistently perceive enough difference in quality, reliability, and application performance to pay for premium treatment over time?
That said, the underlying proposition is credible. For frequent business travellers, reliable application performance during a high-speed rail journey is materially more valuable than an abstract claim of higher peak throughput.
I have covered railway communications ranging from Huawei’s private 5G deployment at Hungary’s East-West Gate terminal to the decidedly less futuristic reality of a German railway disruption linked to legacy 2G dependence in 2026. China Mobile is pushing the question one stage further: what happens after baseline connectivity becomes reliable?
The network becomes programmable. Then context-aware. Then intelligent. Finally, it becomes commercial. At 350 km/h between Beijing and Shanghai, China Mobile is beginning to demonstrate what that progression could look like. The route to 5G revenue may not be selling passengers a nominally faster network. It may be selling them a materially better journey.
Also see: GSMA Foundry — China Mobile case study: “Connecting High-Speed Rail Passengers”
…………………………………………………………………………………………………………………………………………………………………..
References:
https://www.fierce-network.com/wireless/china-mobile-takes-express-train-5g-revenue
https://www.gsma.com/get-involved/gsma-foundry/gsma_resources/connecting-high-speed-rail-passengers-china-mobile/ – Primary case-study source for the AI algorithm in the packet core, passenger identification, high-speed-rail connectivity optimization, and the broader China Mobile deployment concept
“China Mobile and Huawei Team Up to Launch AI-Powered 5G-A …” – Secondary coverage describing the reported architecture as a combination of a dedicated high-bandwidth 5G-A network for high-speed rail, an AI-native core, and intelligent network-management functions.
China Mobile & ZTE use digital twin technology with 5G-Advanced on high-speed railway in China
Nokia & Deutsche Bahn deploy world’s first 1900 MHz 5G radio network meeting FRMCS requirements
ZTE and China Telecom: 5G network test on a high speed train; Uplink enhancement FAST verification
KDDI, Samsung: 28GHz surveillance video call on train platform using 5G base station
Google’s Internet Access for Emerging Markets – Managed WiFi Network for India Railways
The AI Infrastructure Build-Out: A $10 Trillion Bet on Compute, Power, and Networks
Sept 2026 3GPP meeting updates for 5G Advanced and 6G planning (with timeline for submisson to ITU-R WP 5D via ATIS)
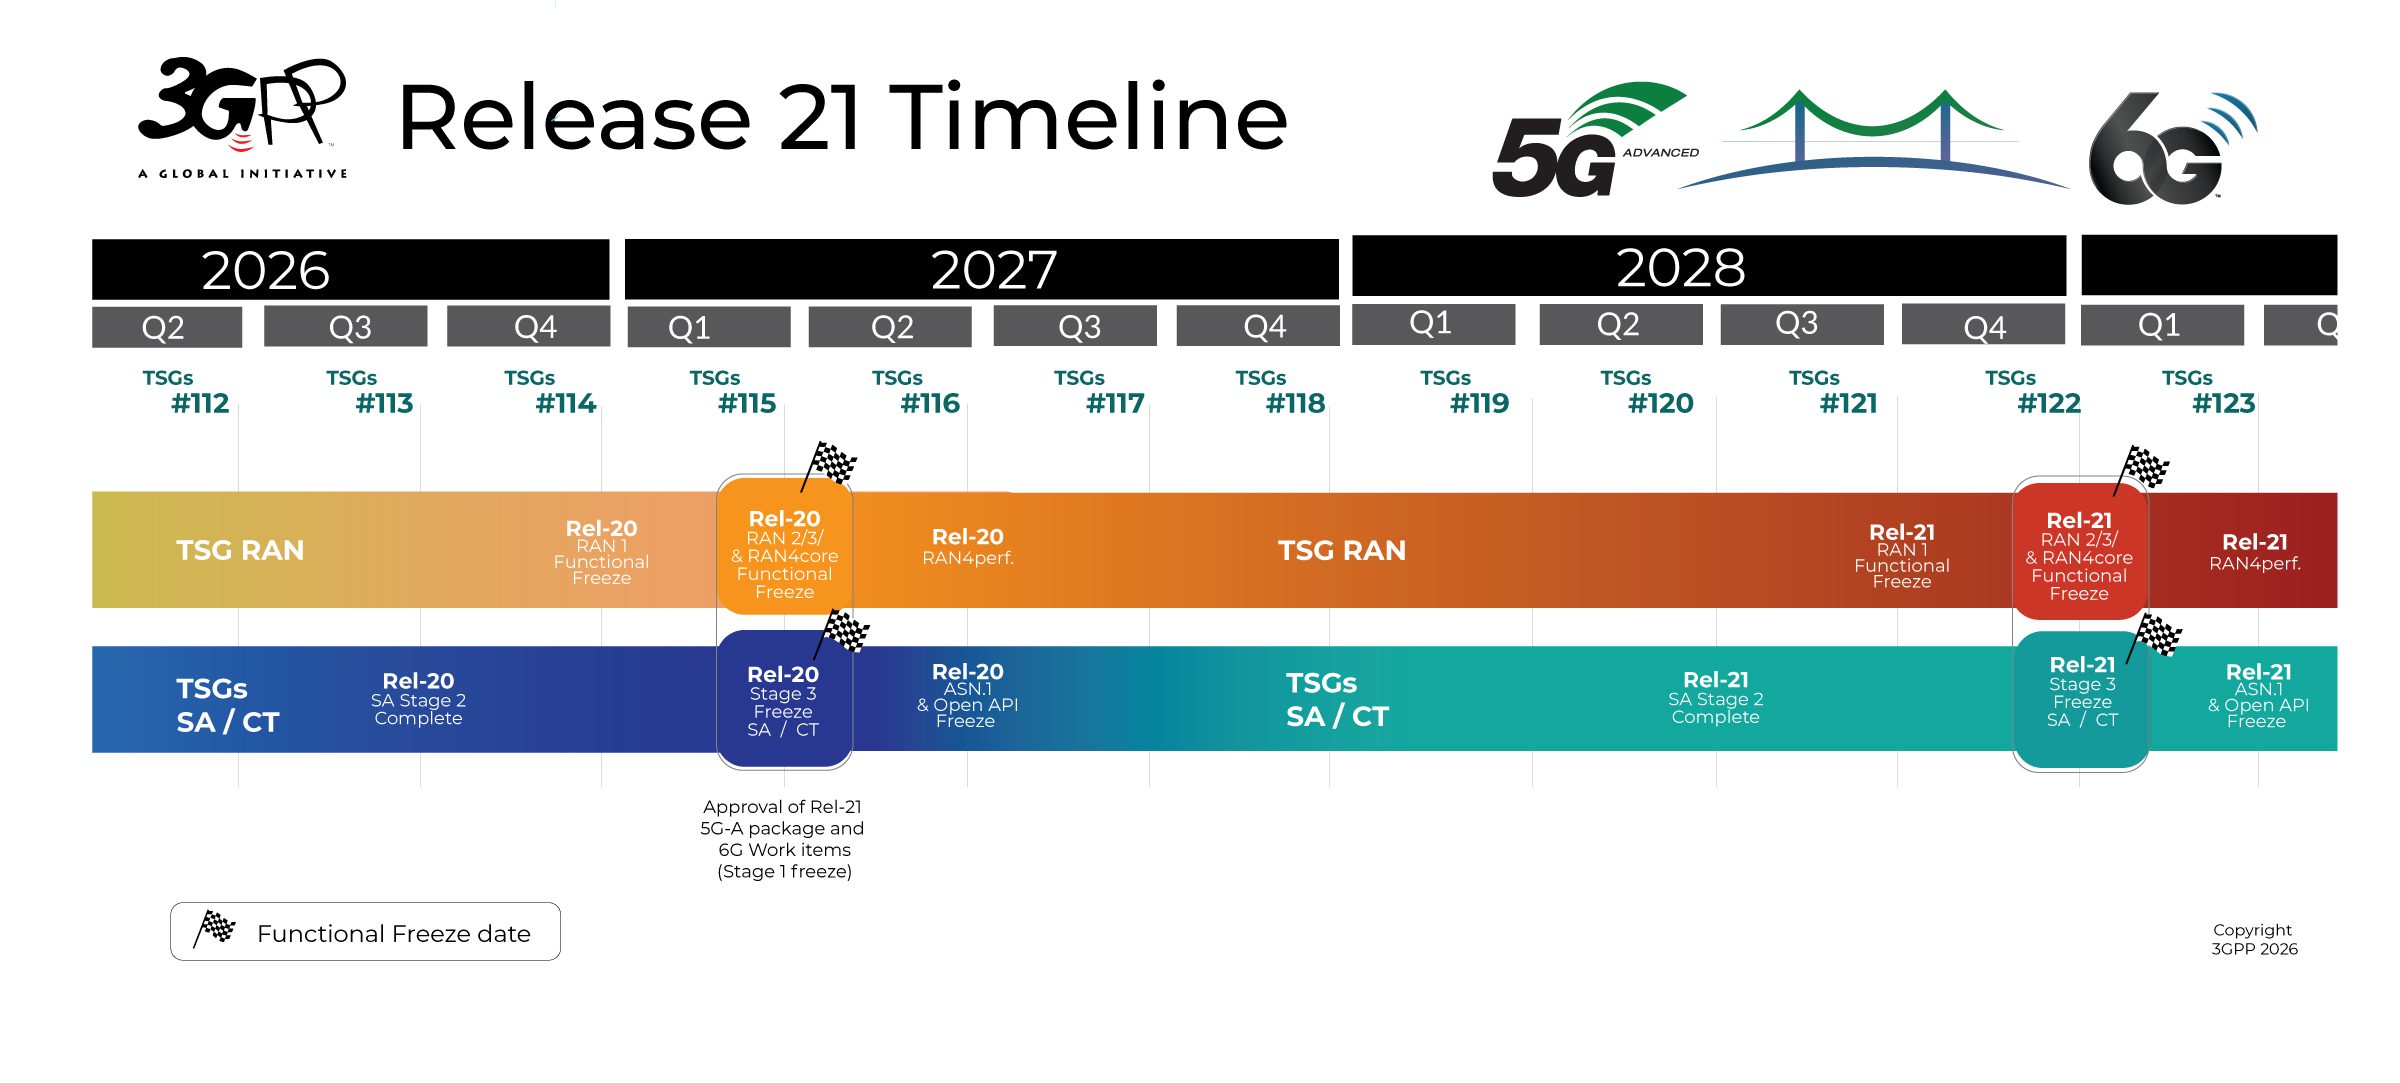
- 100% Stage 2 Freeze: The primary technical output for Release 20 was hitting the 100% completion target for Stage 2 (System Architecture). This officially locks down the architectural aspects for 5G Advanced next wave, transitioning the bulk of execution entirely to Stage 3 protocol and core implementation.
- 6G Dual Connectivity Way Forward: Delegates finalized critical deployment decisions regarding how 6G will integrate with existing infrastructure. Focus solidified around Option 1 (6G-anchored dual connectivity with 5G NR) and Option 3 (Dual stack, no RAN-level aggregation).
- Multi-RAT Spectrum Sharing (MRSS): RAN1 delivered its highly anticipated MRSS preliminary performance evaluation. This evaluates the overhead costs of operators running 5G and 6G simultaneously on the same frequencies, safeguarding migration investments.
- Use Cases and Services: Deepened studies into Integrated Sensing and Communications (ISAC), native AI/ML network applications, and ubiquitous connectivity (“anywhere to everywhere”).
- Radio Advancements: Maturation of the 6G RAN study on Scenarios and Requirements (TR 38.914), steering the industry closer to initial physical layer specifications.
……………………………………………………………………………………………………………………………………………………………….
-
- Dual Connectivity Framework: Delegates officially locked down the deployment pathways for the first phase of 6G. They established a clear consensus favoring Option 1 (6G-anchored dual connectivity with 5G NR) and Option 3 (Dual stack/independent radio lines), settling intense architectural debates on how 6G will overlay on 5G infrastructure.
- MRSS Performance Baseline: RAN1 finalized its preliminary performance evaluations for Multi-RAT Spectrum Sharing (MRSS). This technical milestone establishes the exact overhead margins required to run 5G and 6G simultaneously on legacy bands, preventing spectral efficiency loss during the transition.
- TR 38.914 Technical Alignment: The radio groups finalized the foundational baseline for the Radio Scenarios and Requirements report (TR 38.914), updating propagation channel models to explicitly match the new spectrum ranges targeted for initial Release 21 designs.
- ISAC Requirements Progression: SA2 finalized early system-level flows for Integrated Sensing and Communications (ISAC), formalizing how a 6G network will dynamically allocate base station radio energy to double as radar mapping infrastructure.
-
- Initial Framework Alignment (Mid-2027): ATIS will submit the early Release 21 architectural structures and capability definitions resulting from these choices to the 55th meeting of WP 5D. This acts as an initial informational contribution to show compliance with the IMT-2030 (6G) Framework.
- Formal Candidate Technology Submission (Late 2028 / Early 2029): Once these 2026 foundational agreements are fully written into frozen protocol code during the December 2028 Stage 3 Freeze, ATIS will package them into a formal “Candidate RIT (Radio Interface Technology)” proposal.
- The Absolute Cutoff: This complete compliance package and its accompanying technical self-evaluation will be submitted directly ahead of the 59th meeting of WP 5D in February 2029, which is the final deadline for IMT-2030 candidate evaluations.
References:
https://www.3gpp.org/news-events/3gpp-news/ran113-reports
https://portal.3gpp.org/?tbid=373&SubTB=373#/
Roles of 3GPP and ITU-R WP 5D in the IMT 2030/6G standards process
Comparing AI Native mode in 6G (IMT 2030) vs AI Overlay/Add-On status in 5G (IMT 2020)
ITU-R WP5D IMT 2030 Submission & Evaluation Guidelines vs 6G specs in 3GPP Release 20 & 21
ITU-R M.[IMT-2030.EVAL] & ITU-R M.[IMT-2030.SUBMISSION] reports: Evaluation & Submission Guidelines for 6G RIT/SRITs (6G)
ITU-R WP5D invites IMT-2030 RIT/SRIT contributions
How NTIA “Call to Action for 6G Leadership and Security” might influence 6G/IMT-2030 standards and 3GPP specifications
NGMN issues ITU-R framework for IMT-2030 vs ITU-R WP5D Timeline for RIT/SRIT Standardization
IMT-2030 (“6G”) Minimum Technology Performance Requirements for Radio Interface Technologies
IMT-2030 Technical Performance Requirements (TPR) from ITU-R WP5D
Ericsson reports 10% drop in 1st quarter sales; targets network growth
Executive Summary:
Ericsson reported mixed first-quarter 2026 results, characterized by continued resilience in its Networks segment despite regional demand variability and emerging supply-side cost pressures. The Swedish company recorded 7% year-over-year organic growth in its Networks business, supported by sustained network modernization programs and ongoing 5G deployments across Europe, the Middle East, and Africa (EMEA), as well as increased delivery volumes in India and Japan. This growth offset a decline in North American sales, which followed a period of elevated operator investment in 2025 and reflects a near-term reallocation of capital expenditure by key customers. However, Ericsson reported a 10% total sales drop to 49.33 billion kronor in the first quarter, with EBITA falling to 1.44 billion kronor.
Ericsson reiterated its expectation of a broadly flat global RAN market in 2026 but expressed confidence in its ability to outperform the overall sector. The Networks segment maintained a robust adjusted gross margin of 50.4%, within its guided 49–51% range, with similar margin performance anticipated in the second quarter. Sequential revenue growth is projected to align with typical seasonal trends, approximating a 4% increase.
Despite these operational strengths, Ericsson highlighted increasing uncertainty in the macroeconomic and geopolitical environment. Of particular concern is the rising cost of components—especially semiconductors—driven in part by global AI-related demand. The company indicated that while semiconductors represent a relatively limited portion of its total cost base, sustained price increases are expected to create headwinds.
To mitigate these pressures, Ericsson is pursuing a combination of supply chain optimization, product substitution strategies, operational efficiencies, and selective cost-sharing mechanisms with customers. The company emphasized that its prior investments in supply chain diversification have enhanced resilience, although it acknowledged that it remains exposed to broader market disruptions affecting pricing and component availability.
Geopolitical factors have also introduced operational challenges. Ongoing conflict in the Middle East has necessitated adjustments to logistics and transportation routes, resulting in incremental costs. Ericsson noted that its regional distribution infrastructure has been impacted but that supply continuity has been maintained through flexible supply chain management.
From a financial perspective, Ericsson reported first-quarter EBIT of SEK 1.44 billion, a significant decline from SEK 5.93 billion in the prior year, reflecting restructuring charges and adverse currency movements. Group revenue decreased 10% year-over-year to SEK 49.33 billion, below market expectations, while gross margin contracted to 47.2% from 48.2%.

Image Credit: lars schroder/Agence France-Presse/Getty Images
…………………………………………………………………………………………………………………………………………
Börje Ekholm, Ericsson President and CEO, said:
“Our Q1 results demonstrate continued resilience in a dynamic environment, with organic sales growth of 6%. Our healthy gross margins and strong cash flow reflect the progress we have made in recent years, reducing reliance on geographic mix and strengthening our foundations globally. Our multi-year investments in building a resilient, diversified, supply chain have enabled us to deliver consistently for customers amidst geopolitical and macroeconomic uncertainties. We are facing increasing input costs, especially in semiconductors, caused in part by AI demand. Our ambition is to offset these challenges, by working closely with customers and suppliers, and through product substitution and efficiency actions. Looking ahead, while we continue to expect a flattish RAN market, our focused strategy, leading portfolio, and strengthened positions in mission critical and Enterprise give us confidence in our ability to grow faster than the mobile networks market and drive long-term success.”
Overall, the results underscore a transitional phase for Ericsson, with strong execution in global 5G and modernization programs partially offset by cyclical demand softness in North America and emerging cost inflation in critical technology inputs. The company recorded 7% year-over-year organic growth in its Networks business, supported by sustained network modernization programs and ongoing 5G deployments across Europe, the Middle East, and Africa (EMEA), as well as increased delivery volumes in India and Japan. This growth offset a decline in North American sales, which followed a period of elevated operator investment in 2025 and reflects a near-term reallocation of capital expenditure by key customers.
Ericsson’s quarter reinforces a broader industry pattern: the global RAN market is stabilizing after the 5G deployment peak, but not re-entering a meaningful growth phase. Until 6G capex begins to scale later in the decade, vendor performance will depend more on regional share gains, modernization cycles, and margin discipline than on total market expansion. After the 5G buildout peak, network operators are largely shifting from coverage expansion to optimization, monetization, and cost efficiency, which limits near-term revenue upside for vendors even when unit shipments remain healthy.
………………………………………………………………………………………………………………………………………………
RAN Market dynamics:
The key issue is that RAN demand is no longer being driven by broad-based new macro rollouts. Instead, spending is being concentrated on targeted modernization, selective capacity adds, and feature upgrades, while legacy LTE revenue continues to decline and offsets much of the remaining 5G activity.
That helps explain why vendors can still post pockets of growth in regions like EMEA, India, and Japan while North America softens after a prior wave of heavy investment. In other words, regional growth is becoming more cyclical and more dependent on operators’ capex timing than on a sustained global upgrade super-cycle.
Why RAN growth stays muted:
The structural problem is that RAN is maturing into a low-growth infrastructure market. Dell’Oro’s latest forecast points to only about 1% CAGR over the next five years, with the broader market remaining largely flat until 6G-related capex begins to ramp late in the decade.
That means the industry is effectively living through a long gap between the end of the 5G peak and the start of the 6G investment cycle. During that gap, vendors compete less on market expansion and more on mix, efficiency, software attach, and share gains, which is why financial performance can diverge from headline market growth.
What this means for Ericsson:
For Ericsson, the implication is that beating the market may matter more than the market itself. If the underlying RAN market is flat to low-single-digit growth, then Ericsson’s ability to sustain margin through supply-chain discipline, pricing, and product mix becomes more important than chasing top-line expansion alone.
This is also why component inflation matters now. When market growth is weak, cost pressure from semiconductors, logistics, and geopolitics has a larger effect on earnings quality, because vendors have fewer natural volume tailwinds to absorb it.
6G/IMT 2030 timing risk:
The big strategic uncertainty is timing. If meaningful telco 6G capex does not begin until around 2030–2031 (which seems highly likely), then the wireless telecom industry faces several years of subdued RAN revenue. That creates pressure on vendors to extract value from 5G Advanced, automation, private networks, and software-led differentiation before the next technology cycle arrives.
This is why “no real growth till 6G in 2031” is a reasonable framing. It captures the reality that the market can remain technically active while still being economically stagnant, with limited aggregate revenue growth even as networks become more capable and more software-defined.
From Sebastian Barros:
“Ericsson’s Q1 results are a masterclass in structural paradox. Pulling a 6% organic growth rate in a dead-flat global RAN market is a massive operational flex for a 150-year-old heavyweight. But look under the hood. Reported sales took a 10% hit due to brutal FX headwinds, and their supply chain is under intense pressure as global AI data centers hoard 3nm semiconductor capacity. Their historic dominance in custom ASIC silicon and radio frequency is exactly what makes them structurally vulnerable today. Being functionally addicted to a $35 billion RAN market that accounts for over 60% of their portfolio is a massive liability, as that profit pool is being actively dismantled by x86/GPU disaggregation, open architectures, and geopolitical hardware wars…”
………………………………………………………………………………………………………………………………………………………………….
References:
Ericsson and Forschungszentrum Jülich MoU for neuromorphic computing use in 5G and 6G
AT&T and Ericsson boost Cloud RAN performance with AI-native software running on Intel Xeon 6 SoC
Ericsson and Intel collaborate to accelerate AI-Native 6G; other AI-Native 6G advancements at MWC 2026
Ericsson goes with custom silicon (rather than Nvidia GPUs) for AI RAN
China’s telecom industry rapid growth in 2025 eludes Nokia and Ericsson as sales collapse
SoftBank and Ericsson-Japan achieve 24% 5G throughput improvement using AI-optimized Massive MIMO
Huawei, Qualcomm, Samsung, and Ericsson Leading Patent Race in $15 Billion 5G Licensing Market
Ericsson announces capability for 5G Advanced location based services in Q1-2026
Highlights of Ericsson’s Mobility Report – November 2025
Ericsson’s revenue drops, profits soar; deal with Vodafone and partnership with Export Development Canada look promising
Huawei unveils AI Centric Network roadmap, U6 GHz products, 5G Advanced strategy and SuperPoD cluster computing platforms
Missing from all the MWC 2026 6G AI alliance announcements, Huawei released a series of all-scenario U6 GHz products to help carriers unlock the full potential of 5G Advanced (5G-A) and set the stage for a seamless transition to 6G. Huawei also showcased its SuperPoD cluster for the first time outside China, which they have created to offer “a new option for the intelligent world.”
- The all-scenario U6 GHz products and solutions Huawei released today use innovative technologies to create a high-capacity, low-latency, optimal-experience backbone designed for mobile AI applications.
- There are already 70 million 5G-A users globally, and 5G-A is increasingly being adopted by carriers at scale. In China, Huawei has helped carriers deliver contiguous 5G-A coverage across 270 cities and launch 5G-A packages that monetize experience in over 30 provinces.
The company also launched enhanced AI-Centric Network solutions [1.] that will help carriers prepare for the agentic era by enabling intelligent services, networks, and network elements (NEs). The company’s plans to build more AI-centric networks and computing backbones that will help carriers and industry customers seize opportunities from the AI era.
Note 1. Huawei’s AI-Centric Network roadmap is designed to integrate intelligence directly into 5G-Advanced (5G-A) infrastructure and accelerate the transition toward Level-4 Autonomous Networks. The company plans to work with global carriers (where its not blacklisted) on the large-scale 5G-A deployment, use high uplink to address surging consumer and industry demand for mobile AI applications, and use the U6 GHz band to unlock the full value of spectrum and pave the way for smooth evolution to 6G.

Photo Credit: Huawei
………………………………………………………………………………………………………………
Three-Layer Intelligence in AI-Centric Networks: Accelerating the Agentic Era:
As mobile network operators transition toward AI-native 5G-Advanced and early 6G architectures, Huawei is positioning its AI-Centric Network portfolio as the blueprint for next-generation intelligent networks. By embedding intelligence across service, network, and network element (NE) layers, Huawei aims to establish the foundation for fully agentic, autonomously managed infrastructures.
- Service Layer: Focuses on multi-agent collaboration platforms to transform core carrier services—such as voice and home broadband—into intelligent service platforms.
- Network Layer: Aims to evolve from single-scenario automation to end-to-end single-domain network autonomy. Huawei officially launched AUTINOps, an AI-native intelligent operations solution designed to replace traditional manual O&M with predictive, preventive “digital employees”.
- Network Element (NE) Layer: Utilizes AI to optimize algorithms for RANs (Radio Access Networks) and core networks, improving spectral efficiency and service awareness.
At the Service layer, Huawei is enabling carriers to operationalize multi-agent collaboration frameworks that embed domain-specific intelligence into key service categories: voice, broadband, and digital experience monetization. These AI agents dynamically manage customer experience and lifecycle value, supporting the transformation of core connectivity services into intelligent, context-aware digital offerings.
At the Network layer, the company’s Autonomous Driving Network Level 4 (ADN L4) initiative focuses on single-scenario automation, delivering measurable improvements in O&M efficiency, service quality, and monetization agility. By the close of 2025, ADN single-scenario deployments were active across more than 130 commercial telecom networks. The next phase targets end-to-end, single-domain autonomy across transport, access, and core networks—an essential step toward zero-touch O&M and intent-driven orchestration in 5G-A and 6G environments.
At the Network Element layer, Huawei is jointly advancing AI-driven innovation across RAN, WAN, and core domains. This includes algorithmic optimization for intelligent RAN scheduling, service-aware traffic identification in WANs, and unified intent modeling across B2C and B2H use cases. Such capabilities enhance spectral and energy efficiency, enable predictive resilience, and provide fine-grained service awareness—all foundational for AI-native air interface and network control in 6G.
Computing Backbone with SuperPoD Clusters:
Supporting this vision, Huawei is introducing its next-generation SuperPoD and cluster computing platforms, designed as high-performance compute backbones for distributed AI model training and inference within telecom and enterprise domains. Featuring the proprietary UnifiedBus interconnect and system-level architecture innovations, the Atlas 950, TaiShan 950, and Atlas 850E SuperPoDs, along with the TaiShan 200–500 servers, deliver ultra-low latency and high throughput optimized for trillion-parameter AI models and real-time agentic operations.
Aligned with its open innovation strategy, Huawei continues to expand an open, collaborative computing ecosystem, supporting open-source frameworks and open-access platforms to accelerate the deployment of intelligent, AI-driven digital infrastructure worldwide.
Intelligent Transformation Across Industry Domains:
At MWC Barcelona 2026, Huawei is highlighting 115 end-to-end industrial intelligence showcases across verticals, underscoring its role in helping enterprises adopt AI-centric operational models. Through the SHAPE 2.0 Partner Framework, 22 co-developed AI and digital infrastructure solutions will demonstrate how vertical industries—from manufacturing and energy to transportation and healthcare—can harness 5G-A and AI integration to deliver measurable business outcomes.
Toward 5G-A Commercialization and 6G Evolution:
With large-scale 5G-Advanced rollouts accelerating, Huawei is collaborating with global carriers and ecosystem partners to realize level-4 autonomous networks and establish the architectural bridge to 6G. Central to this evolution is the convergence of AI, connectivity, and computing—enabling networks that can self-learn, self-optimize, and autonomously orchestrate service intent. These AI-Centric Network initiatives and SuperPoD-based computing backbones form the foundation for value-driven, intelligent networks built for the agentic era.
5G-Advanced and Infrastructure Innovations:
Huawei’s 5G-A strategy, branded as GigaUplink, focuses on delivering the high-uplink capacity and low latency required for mobile AI applications:
- U6 GHz Spectrum: Launched a comprehensive portfolio of all-scenario U6 GHz products to unlock 5G-A’s full potential and provide a smooth evolution path to 6G.
- Agentic Core: Introduced the Agentic Core solution, which integrates intelligence natively into the core network to support ubiquitous AI agent access across devices.
- All-Optical Target Network: Proposed an AI-centric optical roadmap featuring dual strategies: “AI for networks” (optimizing operations) and “networks for AI” (supporting AI workloads with ultra-low latency benchmarks of 1-5ms).
………………………………………………………………………………………………………………………………………………………..
References:
https://www.huawei.com/en/news/2026/3/mwc-ai-centric-network
https://carrier.huawei.com/en/minisite/events/mwc2026/
Huawei FY2025: 2.2% YoY revenue increase; strategic pivot to AI & Automotive
NVIDIA and global telecom leaders to build 6G on open and secure AI-native platforms + Linux Foundation launches OCUDU
Omdia on resurgence of Huawei: #1 RAN vendor in 3 out of 5 regions; RAN market has bottomed
Huawei, Qualcomm, Samsung, and Ericsson Leading Patent Race in $15 Billion 5G Licensing Market
Huawei Cloud Review and Global Sales Partner Policies for 2026
Huawei’s Electric Vehicle Charging Technology & Top 10 Charging Trends
Huawei to Double Output of Ascend AI chips in 2026; OpenAI orders HBM chips from SK Hynix & Samsung for Stargate UAE project
Huawei launches CloudMatrix 384 AI System to rival Nvidia’s most advanced AI system
U.S. export controls on Nvidia H20 AI chips enables Huawei’s 910C GPU to be favored by AI tech giants in China
AT&T and Ericsson boost Cloud RAN performance with AI-native software running on Intel Xeon 6 SoC
T-Mobile US announces new broadband wireless and fiber targets, 5G-A with agentic AI and live voice call translation
T-Mobile US (the “Un-carrier”) today announced new targets of 15 million 5G broadband customers by 2030, a 25% increase from its previous target of 12 million by the end of 2028, driven by increased spectral efficiency, better CPE technology, increased eligibility including to business customers with complementary usage profiles, and broadened product offerings to continue to meet evolving customer needs. T-Mobile is also leveraging its scale and nationwide 5G Advanced network to expand into new growth areas, including advertising, financial services, and long-term opportunities in edge and physical AI. The top rated U.S. wireless telco is also expecting between 3 and 4 million T-Fiber customers by 2030.
“T-Mobile is raising the bar on what customers, stockholders, and the industry can expect from the Un-carrier. T-Mobile has an unmatched combination of the Best Network, Best Value, and Best Customer Experiences — hallmarks of our unique Un-carrier differentiation — paired with our industry-leading portfolio of assets,” said T-Mobile CEO Srini Gopalan.
“This is why customers bring their connectivity relationship to T-Mobile. Looking ahead, we see an extraordinary runway to further expand this differentiation — through sustained momentum in network perception, digital and AI-driven transformation, and our future-forward innovation in areas like 6G and advanced AI. With this foundation, I’m confident that the future has never been brighter.”
Here are 2 of many impressive slides from T-Mo’s investor presentation referenced below:
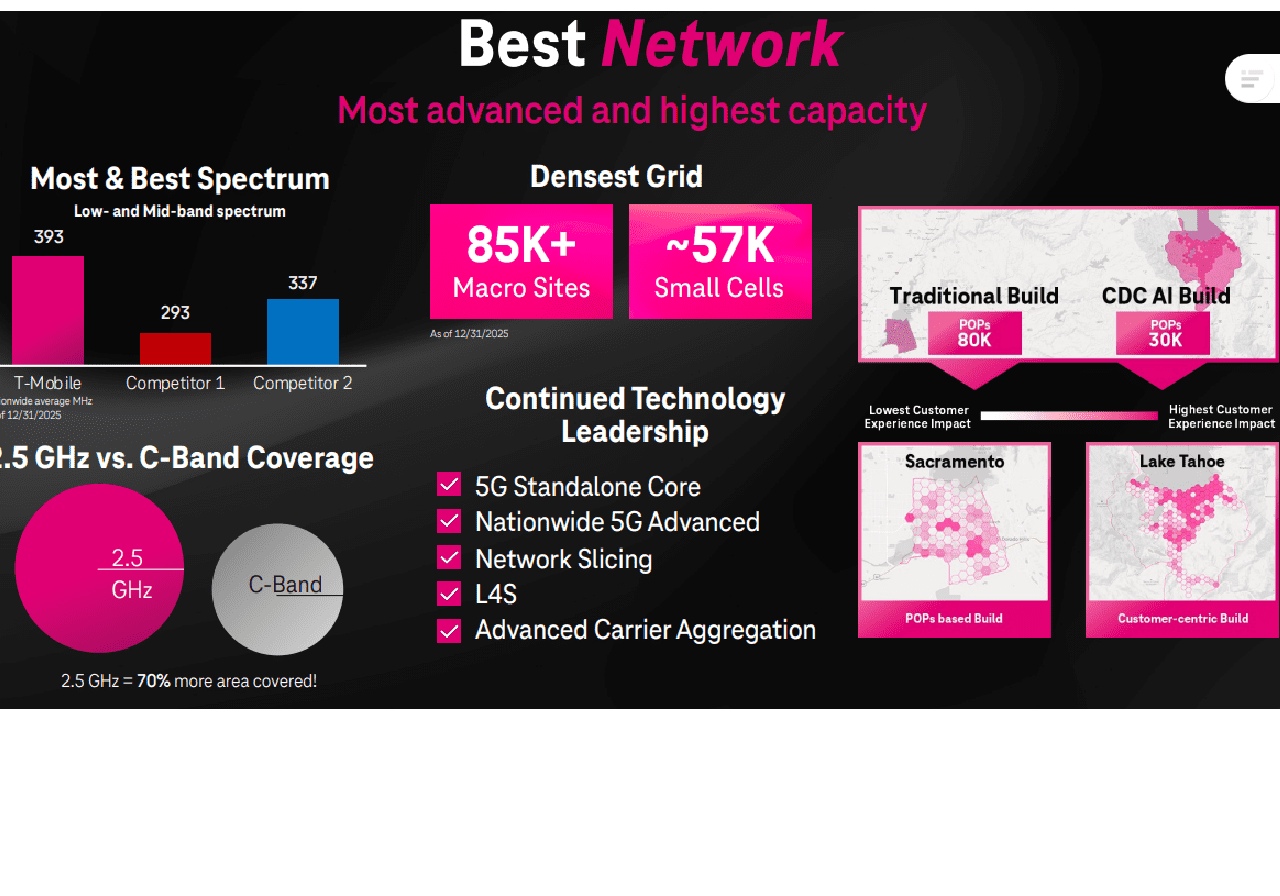
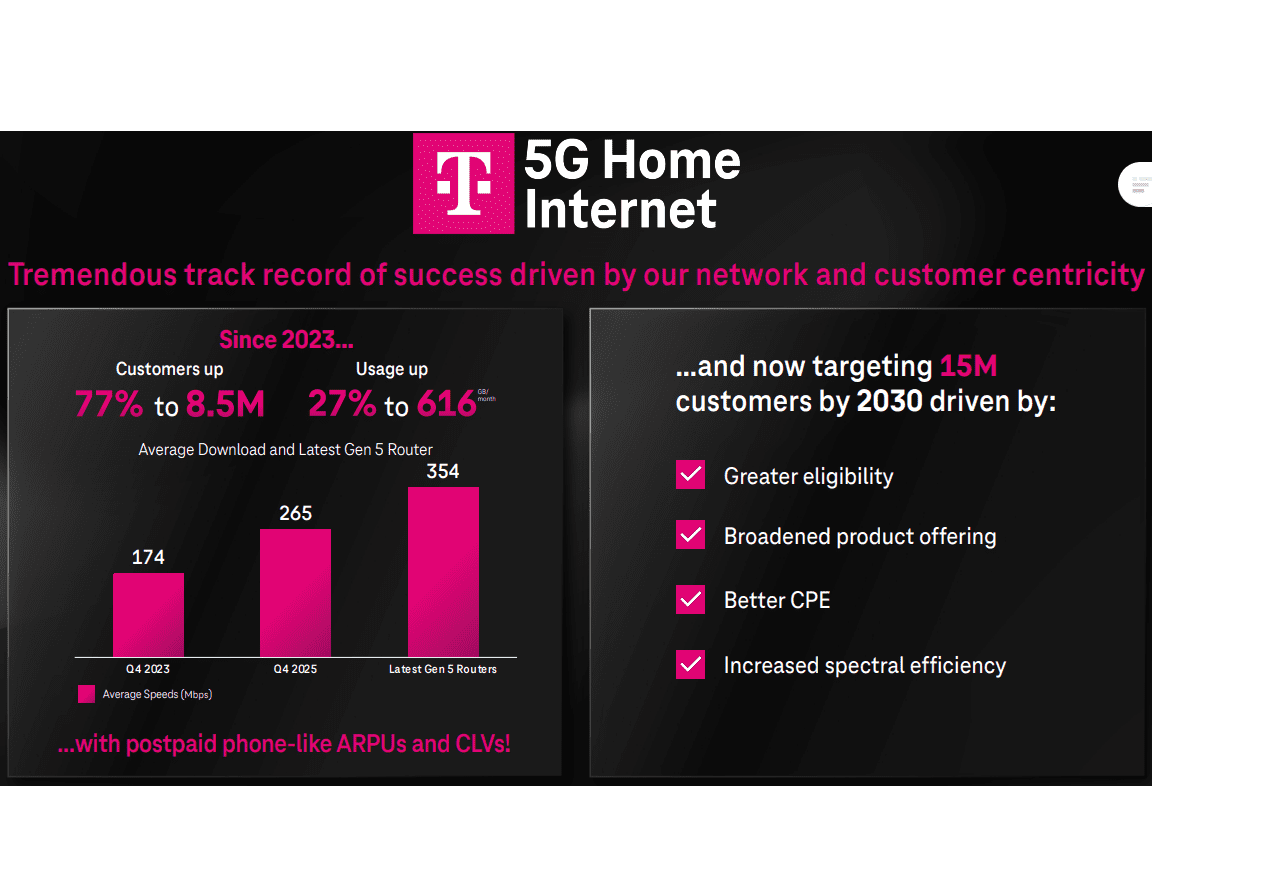
The Un-carrier also plans to launch real-time and agentic AI services directly into its 5G-Advanced (5G-A) network by the end of 2026. This initiative, which began with a beta program in early 2026 for postpaid customers, allows for AI-driven features to function natively within the network, meaning users do not need to download specific apps or upgrade their hardware. This 5G-A offering will include live voice call translation in over 50 languages. By integrating AI directly into the 5G-A infrastructure (RAN, core network, and management layers), T-Mobile is enabling features that work on any eligible device, not just smartphones.
New 5G-A Agentic AI Highlights:
- The initial application is a “Live Translation” feature for voice calls, allowing for real-time translation in over 50 languages.
- “Agentic” AI and Automation: The network will use AI to enhance operational efficiency, including predictive optimization and dynamic resource allocation.
- The 5G-Advanced deployment also supports increased data speeds (up to 6.3 Gbps in tests), low-latency applications like XR and cloud gaming, and enhanced location services.
- The forthcoming capability will permit features to be active with only one participant needing to be on the 5G-A network.
- Infrastructure Partners: T-Mobile is collaborating with partners including NVIDIA, Ericsson, and Nokia to build an AI-RAN (Radio Access Network) framework. Telecompaper Telecompaper +3 This move is part of a broader strategy to transition from 5G to 5G-Advanced, with a focus on delivering “intent-driven” AI services and laying the groundwork for 6G (IMT 2030).
……………………………………………………………………………………………………………………………………….
References:
https://www.t-mobile.com/how-mobile-works/innovation/5g-advanced
https://www.t-mobile.com/news/business/t-mobile-capital-markets-day-update-feb-2026
https://www.t-mobile.com/benefits/live-translation
Virtualization’s role in 5G Advanced (3GPP Release 18) and a proposed new hardware architecture
Disclaimer: The author used Google Gemini to provide research contained in this article.
In a February 9, 2026 article, Ji-Yun Seol, Executive VP and Head of Product Strategy, Networks Business at Samsung, says: “The evolution from 5G to 5G-Advanced and 6G hinges on three interconnected pillars: virtualization for flexible networks, AI integration across all network layers, and automation towards autonomous networks.”
As the IEEE Techblog has extensively covered both AI RAN and the use of AI in 6G (IMT 2030), this post focuses on the role of virtualization in 5G Advanced.
In 3GPP Release 18 (5G-Advanced), virtualization is the foundational technology that enables several “software-defined” breakthroughs. 3GPP Release 18 components) have already been submitted to ITU-R WP 5D for inclusion in the next revision of ITU-R M.2150. Any remaining technical issues and the final decision for publication of ITU-R M.2150-3 are expected to be resolved during the WP 5D meeting concluding in Feb 2026.
3GPP Rel 18 features that depend most heavily on a virtualized, cloud-native architecture include:
- Host AI Models: Run complex machine learning algorithms for channel state information (CSI) feedback, beam management, and positioning.
- Automate Optimization: Enable “zero-touch” operations where the network dynamically adjusts power and resource allocation based on predictive traffic patterns.
While slicing existed in earlier releases, 5G-Advanced introduces more sophisticated, automated management. Virtualization is critical for:
Dynamic Resource Partitioning: Using Cloud-native Network Functions (CNFs) to create dedicated virtual networks on demand for specific use cases like Public Safety or industrial automation.
- SLA Assurance: Automatically scaling virtual resources to guarantee the ultra-low latency required for high-bandwidth applications like XR (Extended Reality).
To support lightweight headsets, 5G-Advanced relies on split-rendering.
- Edge Cloud Dependency: Virtualization allows heavy graphical processing to be moved from the headset to a virtualized Edge Cloud. This requires a highly agile, virtualized edge infrastructure to maintain the near-zero delay needed for immersive experiences.
- Infrastructure Visibility: New protocols provide the 3GPP layer with direct visibility into the underlying virtualized platform to detect vulnerabilities in the software-defined infrastructure.
Virtualization enables “self-organizing networks” (SON) where network entities can self-configure.
- Lifecycle Management: Standardized solutions in Rel-18 allow for the automated downloading, activation, and testing of software across virtualized network functions (VNFs).
| Feature | Primary Virtualization Dependency |
|---|---|
| AI/ML for RAN | Hosting and training models on COTS hardware |
| Edge-Based XR | Offloading computation to virtualized edge nodes |
| Automated Slicing | Rapid instantiation of CNFs for specific “slices” |
| Net Energy Saving | Software-driven power-down of virtual resources |
………………………………………………………………………………………………………………………………………………………………………………………………………………………………….
On the hardware side, traditional telecommunications infrastructure was defined by a tight coupling of network functions to proprietary, purpose-built hardware—resulting in siloed environments where routers, baseband units, and security appliances existed as distinct physical appliances. While providing reliable performance, this monolithic model introduced limitations in scalability, creating high demands for space, power, and capital expenditure for functional upgrades.
Virtualization transforms this paradigm by decoupling network functions from dedicated hardware, deploying them as software-defined workloads on commercial off-the-shelf (COTS) servers. This shift toward general-purpose compute platforms drives operational efficiency, enhances flexibility, and enables AI readiness. The industry adoption followed a staged evolution: starting with the virtualization of core networks—migrating packet gateways and subscriber databases to standard servers—followed by Virtualized RAN (vRAN), which disaggregates baseband processing from radio hardware to operate as cloud-native software.
In 5G-Advanced (Release 18), the hardware shifts from proprietary “black boxes” to a disaggregated architecture of General-Purpose Processors (GPPs) and Specialized Accelerators.
The physical infrastructure required to run these virtualized functions generally falls into three categories:
Virtual Network Functions (VNFs) and Cloud-native Functions (CNFs) run on Commercial Off-The-Shelf (COTS) servers designed for high-density environments.
- Processors: Typically
Intel Xeon Scalable or AMD EPYC processors with high CPU core counts (up to 48+ cores) to handle parallelized workloads.
- Memory: Large-scale deployments require 384GB to over 1TB of DDR4/DDR5 RAM to support multiple network “slices” simultaneously.
- Form Factor: Short-depth chassis (300mm to 600mm) to fit into standard telco racks or outdoor cabinets at the network edge.
- Inline vs. Lookaside:
- Lookaside: The CPU sends specific tasks (like Forward Error Correction) to the card and gets them back.
- Inline: The entire L1 data flow passes through the accelerator, reducing the load on the CPU and improving power efficiency.
- Chips: These cards use FPGAs (Field Programmable Gate Arrays), ASICs (Application-Specific Integrated Circuits), or GPUs.
- GPU Integration: Platforms like NVIDIA Aerial use GPUs to accelerate both 5G signal processing and AI workloads on the same hardware.
- DPUs (Data Processing Units): Used to offload networking and security tasks, ensuring that data moves between the radio and the virtualized core with sub-microsecond precision.
| Hardware Component | Function in 5G-Advanced |
|---|---|
| COTS Servers | Host virtualized core and RAN software (vCU, vDU) |
| L1 Accelerators | Handle compute-heavy signal processing (Beamforming, MIMO) |
| SmartNICs / DPUs | Manage high-speed data transfer and timing synchronization |
| GPUs | Power the AI/ML models for network optimization and XR rendering |
…………………………………………………………………………………………………………………………………………………………………..
References:
https://www.3gpp.org/specifications-technologies/releases/release-18
Samsung: Turning legacy infrastructure into AI-ready networks
Dell’Oro: Analysis of the Nokia-NVIDIA-partnership on AI RAN
RAN silicon rethink – from purpose built products & ASICs to general purpose processors or GPUs for vRAN & AI RAN
Comparing AI Native mode in 6G (IMT 2030) vs AI Overlay/Add-On status in 5G (IMT 2020)
Ericsson announces capability for 5G Advanced location based services in Q1-2026
Ericsson’s 5G Advanced location based services (LBS) offering is a comprehensive suite of innovations designed to redefine location-based services across commercial 5G Standalone (SA) networks. Set for release in Q1 2026, it makes Ericsson the leader in 5G positioning technology, offering a scalable and fully integrated solution on top of Ericsson’s dual-mode 5G Core network.
By embedding positioning as a core 5G SA network capability, Ericsson 5G Advanced location services enables Communications Service Providers (CSPs) to monetize precise location services and expand beyond traditional mobile offerings into verticals such as manufacturing, healthcare, public safety, automotive, drones, and more.
Key benefits:
- High Accuracy: Down to sub-meter for indoor and sub-10 cm for outdoor positioning, enabling precise tracking
- Scalability: Scalable, precise positioning for outdoor applications (automotive, agriculture, drones)
- Seamless Indoor/Outdoor Coverage: Unified 5G positioning technology for both environments.
- Developer & Device Friendliness: No need for device-side apps; improved battery life compared to satellite-based solutions
- Support for Large-Scale Use Cases: Enables massive geofencing, population density analysis, and tracking use cases.
Monica Zethzon, Head of Core Networks, Ericsson, says: “With the launch of 5G Advanced Location Services we are evolving the value of 5G Standalone networks. This innovation gives CSPs the precision and scalability to create differentiated services based on location capabilities.”
Caroline Gabriel, Partner at Analysys Mason, says: “Ericsson’s integrated approach to indoor and outdoor positioning sets a new benchmark in the industry. It addresses critical pain points for operators and enterprises, particularly in sectors where location accuracy is mission-critical.”
The global market for 5G positioning is in its early stages but poised for rapid growth, driven by demand for enhanced precision in diverse sectors. Ericsson’s solution responds to this demand with scalable, developer-friendly capabilities that improve device battery life compared to legacy systems.
This launch further strengthens Ericsson’s location solutions based on Real-Time Kinematics technology, with related devices from Ericsson planned for Q1 2026.

Photo Credit: Ericsson
………………………………………………………………………………………………………………………………………………………….
- Integrated Positioning: Positioning is built into the 5G Standalone (SA) architecture, moving beyond traditional GPS reliance.
- High Accuracy & Efficiency: New techniques improve accuracy (e.g., bandwidth aggregation, carrier-phase measurements) and reduce power consumption for devices.
- AI/ML Integration: Artificial Intelligence/Machine Learning is applied to enhance positioning accuracy, especially for challenging scenarios like beyond-visual-line-of-sight (BVLOS).
- Support for New Devices/Apps: Enables precise tracking for wearables, industrial sensors (RedCap), augmented reality (AR), drone control, and smart grids.
- Beyond-Line-of-Sight (BVLOS): Focus on reliable positioning for industrial and public safety applications where line-of-sight isn’t guaranteed.
- Reduced Power: Solutions target lower power usage, crucial for IoT devices.
- Release 18 (5G Advanced Start): Finalized mid-2024, introduced major LBS enhancements, including RedCap positioning, bandwidth aggregation, and carrier-phase support.
- Release 19 (Ongoing): Continues the evolution, extending LTM (L1/L2-triggered Mobility) and further exploring AI/ML for mobility and positioning.
- Release 20 & Beyond: Will build on these foundations, further evolving towards 6G capabilities.
References:
https://www.ericsson.com/en/press-releases/2026/1/5g-advanced-location-services
5G Advanced offers opportunities for new revenue streams; 3GPP specs for 5G FWA?
What is 5G Advanced and is it ready for deployment any time soon?
Hutchison Telecom is deploying 5G-Advanced in Hong Kong without 5G-A endpoints
China Mobile & ZTE use digital twin technology with 5G-Advanced on high-speed railway in China
Huawei pushes 5.5G (aka 5G Advanced) but there are no completed 3GPP specs or ITU-R standards!
ZTE and China Telecom unveil 5G-Advanced solution for B2B and B2C services
Dell’Oro: RAN market stable, Mobile Core Network market +14% Y/Y with 72 5G SA core networks deployed
A recently published report from Dell’Oro Group notes that after two years of steep declines, initial estimates show that total Radio Access Network (RAN) revenue—including baseband, radio hardware, and software, excluding services—was flat outside of China and up when excluding North America.
“The nearly stable results for the 1Q25-3Q25 period bolster the flat growth thesis we have communicated for some time, reflecting the current state of the 5G network,” said Stefan Pongratz, Vice President of RAN market research at the Dell’Oro Group. “While near-term RAN expectations remain muted, some of the leading RAN suppliers are still cautiously optimistic that more investments are needed over the long-term to ensure the networks evolve from a connectivity pipe into an intelligence grid. Huawei and Ericsson are the clear #1 and 2 players globally – their combined share makes up nearly two-thirds of the RAN market (see table below).” Pongratz added.
Additional highlights from the 3Q 2025 RAN report:
- In the quarter, growth in EMEA was nearly enough to offset declining revenue in North America and the Asia Pacific regions.
- The top 5 RAN suppliers, based on worldwide revenues for the 1Q25-3Q25 period, are Huawei, Ericsson, Nokia, ZTE, and Samsung.
- Market is becoming more concentrated—the top five suppliers accounted for 96 percent of the 1Q25-3Q25 RAN market, up from 95 percent in 2024.
- Huawei and Ericsson’s worldwide RAN revenue share improved for the 1Q25-3Q25 period relative to 2024.
- Huawei and Nokia’s RAN revenue share outside of North America improved for the 1Q25-3Q25 period relative to 2024.
- The short-term outlook remains unchanged, with total RAN expected to remain mostly stable in 2026.
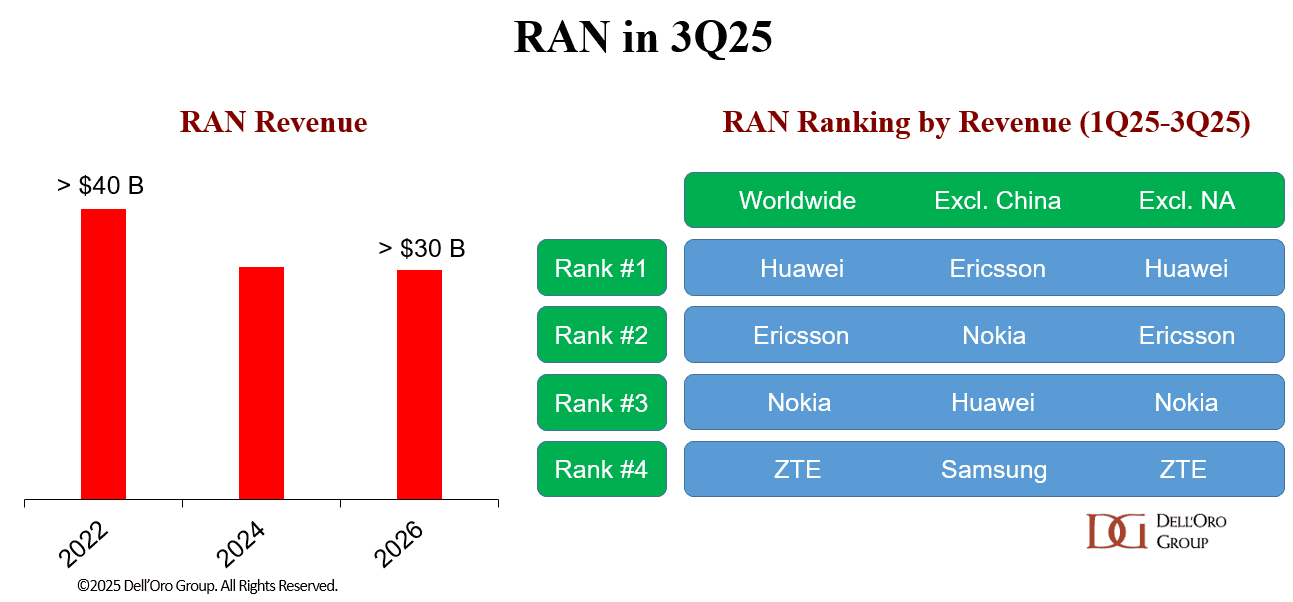

Dell’Oro Group’s RAN Quarterly Report offers a complete overview of the RAN industry, with tables covering manufacturers’ and market revenue for multiple RAN segments including 5G NR Sub-7 GHz, 5G NR mmWave, LTE, macro base stations and radios, small cells, Massive MIMO, Open RAN, and vRAN. The report also tracks the RAN market by region and includes a four-quarter outlook. To purchase this report, please contact us by email at [email protected].
………………………………………………………………………………………………………………………………………….
Data from Omdia, a Light Reading sister company, shows Ericsson, Huawei and Nokia were even more dominant last year than they were in 2023, growing their combined RAN market share by 2.3 percentage points over this period, to 77.4%. Besides China’s ZTE, the only other contender with more than a percentage point of market share was Samsung.
…………………………………………………………………………………………………………………………………………..
Another recent Dell’Oro Group report reveals that the Mobile Core Network (MCN) market revenue outside China surged 14% year-over-year (Y/Y) in 3Q 2025. Twelve Mobile Network Operators (MNOs) have now selected to move forward with 5G-Advanced (the marketing term used for the next phases of 3GPP’s 5G specs, which started with Release 18 and continues with Release 19 and beyond).
“The Chinese market experienced abnormally high growth in 3Q 2024. As a result, the China market revenue declined 39 percent Y/Y for 3Q 2025,” stated Dave Bolan, Research Director at Dell’Oro Group. “The revenue for all the other regions increased, between 9 percent and 17 percent Y/Y, resulting in a worldwide revenue decline of 2 percent Y/Y. As noted, revenue worldwide excluding China rose 14 percent Y/Y, continuing the trend in subscribers migrating to 5G Standalone (5G SA), and revenue worldwide excluding North America declined 5 percent Y/Y.
“MNOs are moving forward with 5G SA (72 in our last count) and moving forward to take advantage of monetization opportunities. Network Slicing announcements continued. Of note is Reliance Jio (India), which announced 10 network slices with guaranteed service level agreements (SLAs) at scale. In October, T-Mobile launched Edge Control, providing enterprises with what Dell’Oro Group refers to as an MNO-provided Mobile Private Network (MPN). This is in response to the challenges of implementing 5G SA Private Wireless networks in the shared CBRS spectrum in the US.
“We have identified 12 MNOs that have commercially launched 5G-Advanced networks (not all this quarter), to take 5G to the next level with new features and performance. MNOs include: China Mobile, China Telecom, China Unicom, CTM (Macau), Du (UAE), e& (UAE), HKT (Hong Kong), Singtel (Singapore), Telstra (Australia), T-Mobile (USA), YTL (Malaysia), and Zain (Kuwait),” added Bolan.
Additional highlights from the 3Q 2025 Mobile Core Network and Multi-Access Edge Computing Report include:
- Region rankings were: EMEA; Asia Pacific, excluding China; China and North America tied; CALA.
- Vendor rankings (with more than 5 percent share) were: Huawei, Ericsson, Nokia, and ZTE.
The Dell’Oro Group Mobile Core Network & Multi-Access Edge Computing Quarterly Report offers complete, in-depth coverage of the market with tables covering manufacturers’ revenue, shipments, and average selling prices for Traditional Packet Core, Evolved Packet Core, 5G Packet Core, Policy, Subscriber Data Management, Signaling, Circuit Switched Core, and IMS Core by geographic regions. To purchase this report, please contact us at [email protected].
About Dell’Oro Group:
Dell’Oro Group is a market research firm that specializes in strategic competitive analysis in the telecommunications, security, enterprise networks, and data center infrastructure markets. Our firm provides in-depth quantitative data and qualitative analysis to facilitate critical, fact-based business decisions.
For more information, contact Dell’Oro Group at +1.650.622.9400 or visit https://www.delloro.com.
References:
MCN Market Up 14 Percent Outside China in 3Q 2025, According to Dell’Oro Group
Market research firms Omdia and Dell’Oro: impact of 6G and AI investments on telcos
Omdia on resurgence of Huawei: #1 RAN vendor in 3 out of 5 regions; RAN market has bottomed
Omdia: Huawei increases global RAN market share due to China hegemony
Dell’Oro Group: RAN Market Grows Outside of China in 2Q 2025
Dell’Oro: RAN revenue growth in 1Q2025; AI RAN is a conundrum
Dell’Oro: Global RAN Market to Drop 21% between 2021 and 2029
Dell’Oro: RAN market still declining with Huawei, Ericsson, Nokia, ZTE and Samsung top vendors
Highlights of Dell’Oro’s 5-year RAN forecast
Dell’Oro: 2023 global telecom equipment revenues declined 5% YoY; Huawei increases its #1 position
Dell’Oro & Omdia: Global RAN market declined in 2023 and again in 2024
Dell’Oro: Mobile Core Network market has lowest growth rate since 4Q 2017
Dell’Oro: Mobile Core Network market driven by 5G SA networks in China
Dell’Oro: Mobile Core Network Market 5 Year Forecast
Dell’Oro: AI RAN to account for 1/3 of RAN market by 2029; AI RAN Alliance membership increases but few telcos have joined
Market research firms Omdia and Dell’Oro: impact of 6G and AI investments on telcos
Market research firm Omdia (owned by Informa) this week forecast that 6G and AI investments are set to drive industry growth in the global communications market. As a result, global communications providers’ revenue is expected to reach $5.6 trillion by 2030, growing at a 6.2% CAGR from 2025. Investment momentum is also expected to shift toward mobile networks from 2028 onward, as tier 1 markets prepare for 6G deployments. Telecoms capex is forecast to reach $395 billion by 2030, with a 3.6% CAGR, while technology capex will surge to $545 billion, reflecting a 9.3% CAGR.
Fixed telecom capex will gradually decline due to market saturation. Meanwhile, AI infrastructure, cloud services, and digital sovereignty policies are driving telecom operators to expand data centers and invest in specialized hardware.
Key market trends:
- CP capex per person will increase from $74 in 2024 to $116 in 2030, with CP capex reaching 2.5% of global GDP investment.
-
Capital intensity in telecom will decline until 2027, then rise due to mobile network upgrades.
-
Regional leaders in revenue and capex include North America, Oceania & Eastern Asia, and Western Europe, with Central & Southern Asia showing the highest growth potential.
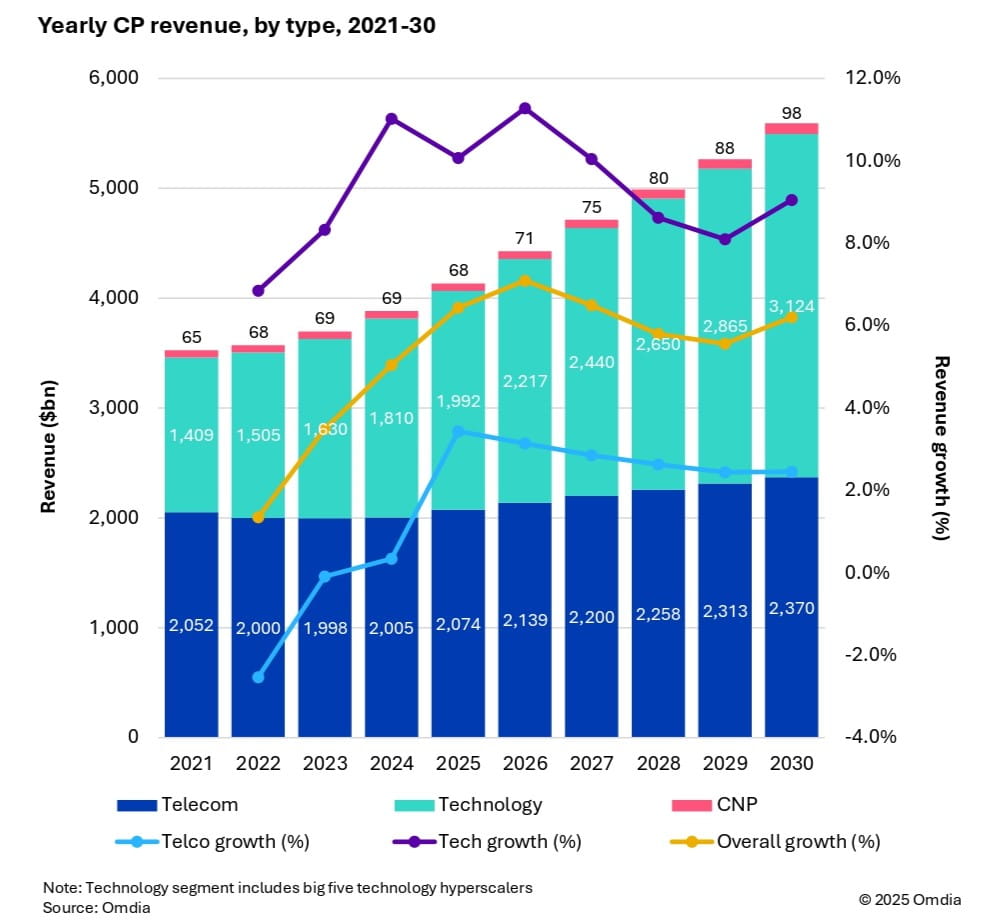 Dario Talmesio, research director at Omdia said, “telecom operators are entering a new phase of strategic investment. With 6G on the horizon and AI infrastructure demands accelerating, the connectivity business is shifting from volume-based pricing to value-driven connectivity.”
Omdia’s forecast is based on a comprehensive model incorporating historical data from 67 countries, local market dynamics, regulatory trends, and technology migration patterns.
…………………………………………………………………………………………………………………………………………………
Separately, Dell’Oro Group sees 6G capex ramping around 2030, although it warns that the RAN market remains flat, “raising key questions for the industry’s future.” Cumulative 6G RAN investments over the 2029-2034 period are projected to account for 55% to 60% of the total RAN capex over the same forecast period.
“Our long-term position and characterization of this market have not changed,” said Stefan Pongratz, Vice President of RAN and Telecom Capex research at Dell’Oro Group. “The RAN network plays a pivotal role in the broader telecom market. There are opportunities to expand the RAN beyond the traditional MBB (mobile broadband) use cases. At the same time, there are serious near-term risks tilted to the downside, particularly when considering the slowdown in data traffic,” continued Pongratz.
Additional highlights from Dell’Oro’s October 2025 6G Advanced Research Report:
- The baseline scenario is for the broader RAN market to stay flat over the next 10 years. This is built on the assumption that the mobile network will run into utilization challenges by the end of the decade, spurring a 6G capex ramp dominated by Massive MIMO systems in the Sub-7GHz/cm Wave spectrum, utilizing the existing macro grid as much as possible.
- The report also outlines more optimistic and pessimistic growth scenarios, depending largely on the mobile data traffic growth trajectory and the impact beyond MBB, including private wireless and FWA (fixed wireless access).
- Cumulative 6G RAN investments over the 2029-2034 period are projected to account for 55 to 60 percent of the total RAN capex over the same forecast period.
Dell’Oro Group’s 6G Advanced Research Report offers an overview of the RAN market by technology, with tables covering manufacturers’ revenue for total RAN over the next 10 years. 6G RAN is analyzed by spectrum (Sub-7 GHz, cmWave, mmWave), by Massive MIMO, and by region (North America, Europe, Middle East and Africa, China, Asia Pacific Excl. China, and CALA). To purchase this report, please contact by email at [email protected].
References:
https://www.lightreading.com/6g/6g-momentum-is-building
6G Capex Ramp to Start Around 2030, According to Dell’Oro Group
https://www.lightreading.com/6g/6g-course-correction-vendors-hear-mno-pleas
https://www.lightreading.com/6g/what-at-t-really-wants-from-6g
Should Peak Data Rates be specified for 5G (IMT 2020) and 6G (IMT 2030) networks?
Peak Data Rate [1.] is one of the most visible attributes of IMT (International Mobile Telecommunications) cellular networks, e.g. 3G, 4G and 5G. As a result, it gets significant attention from analysts and reporters that create high expectations for IMT end users which may never be realized in commercially deployed IMT networks.
For example, the peak data rates specified by the ITU-R M.2410 report for IMT-2020 (5G) have not been realized in any 5G production networks under typical conditions. The ITU-R’s 20 Gbps downlink and 10 Gbps uplink targets are theoretical maximums, achievable only in a controlled test environment with ideal conditions. Please refer to the chart below.
……………………………………………………………………………………………………………………………………………………………………..
Note 1. Peak data rate is the theoretical maximum [achievable] data rate under ideal conditions, which is the received data bits assuming error-free conditions assignable to a single mobile station, when all assignable radio resources for the corresponding link direction are utilized (i.e. excluding radio resources that are used for physical layer synchronization, reference signals or pilots, guard bands and guard times).
………………………………………………………………………………………………………………………………………………………………………
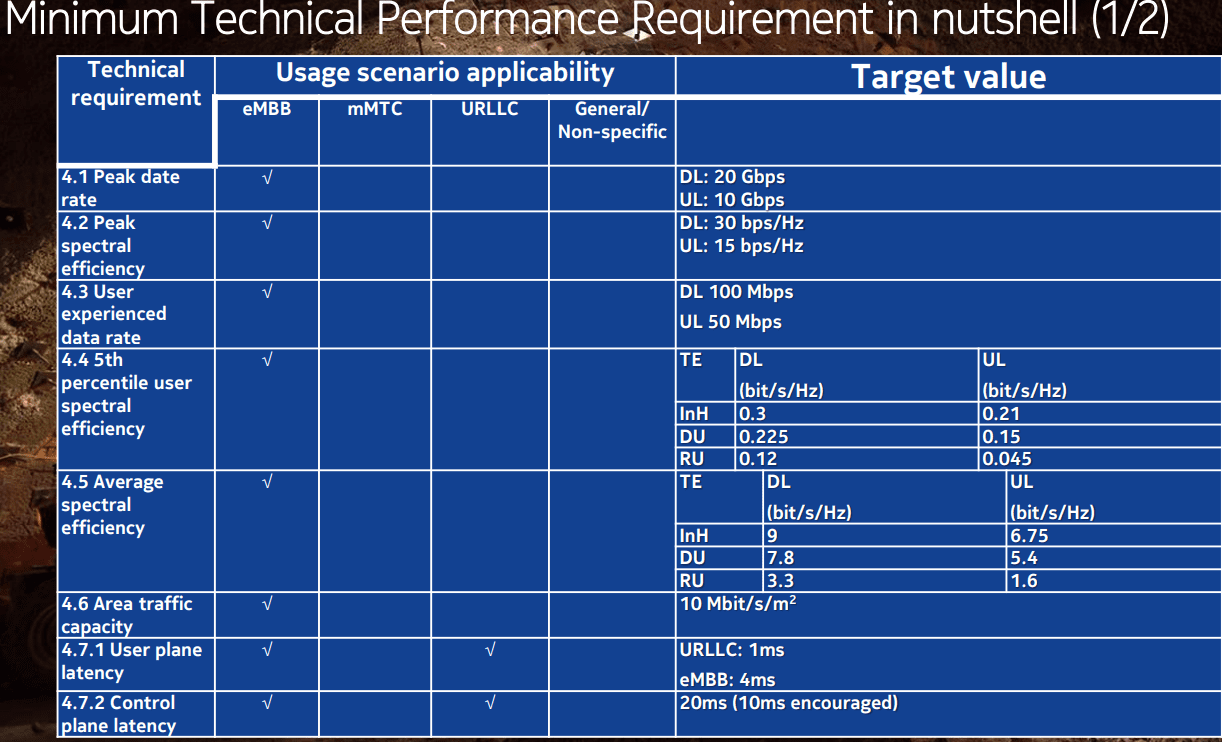
5G services are deployed across three main frequency ranges and the speed capability varies dramatically for each.
- Low-band (sub-6 GHz): Offers wide coverage but only a modest speed improvement over 4G, typically delivering a few hundred Mbps at best.
- Mid-band (sub-6 GHz): Provides a balance of speed and coverage, with peak speeds sometimes reaching 1 Gbps, though typical average speeds are much lower.
- High-band (millimeter wave or mmWave): This is the only band capable of reaching multi-gigabit speeds. However, its signal range is very short and it is easily blocked by physical objects, limiting its availability to dense urban areas and specific venues. 5G mmWave base station power consumption is also very high which limits coverage.
- mmWave spectrum: Higher-band millimeter wave spectrum offers massive bandwidth, enabling multi-gigabit speeds. However, its use is limited to dense urban areas and specific venues due to its short range.
- Carrier aggregation: Combining multiple frequency bands (e.g., mmWave with mid-band) significantly increases the total available bandwidth and is crucial for achieving the highest download speeds.
- 5G Advanced (Release 18): New developments in 5G-Advanced technology (also known as 5.5G) enable even higher performance. The Telstra record in 2025 utilized 5G Advanced software.
- Equipment and device capabilities: Peak speeds require cutting-edge network hardware from vendors like Ericsson, Nokia, and Samsung, as well as the latest mobile devices powered by advanced modems from companies like Qualcomm and MediaTek.
The gap between what IMT-2020 (5G) technology can deliver (on paper) and what is actually realized in commercial 5G networks has grown larger and larger over the past few years [2.]. Here’s a summary of speed differences:
| Speed metric | ITU-R specification | Reality in commercial networks |
|---|---|---|
| Peak data rate | 20 Gbps (downlink)
10 Gbps (uplink) |
Reached only in isolated demonstrations, typically using high-band mmWave technology. |
| User experienced rate | 100 Mbps (downlink)
15 to 50 Mbps (uplink) |
The typical average speed for many users, particularly on low- and mid-band deployments. mmWave is higher, but the range is limited. |
Note 2. The gap is even greater for 5G latency! The minimum required latency in ITU-R M.2410 for user plane are:
– 4 ms for eMBB
– 1 ms for URLLC
assumes unloaded conditions (a single user) for small IP packets (e.g. 0 byte payload + IP header), for both downlink and uplink.
The minimum requirement for control plane latency is 20 ms. Proponents are encouraged to consider lower control plane latency, e.g. 10 ms.
However, the average latency experienced in deployed commercial 5G networks is higher, typically ranging between 5 and 20 milliseconds, depending on the network architecture, spectrum, and use case. One reason is that the 3GPP Release 16 spec for 5G-NR enhancements for URLLC in the RAN and Core network were never completed.
5G mmWave spectrum has the potential for the lowest latency, but its limited range and line-of-sight requirements limit restrict deployments to dense urban areas. Therefore, most 5G users connect via mid-band or low-band, which have higher latency.
……………………………………………………………………………………………………………………………………………………………….
For that reason, several companies (Apple, Nokia, TELECOM ITALIA, Deutsche Telekom, SK Telecom, Spark NZ, AT&T) have proposed not to define IMT-2030 peak data rate requirement values in ITU-R M.[IMT-2030.TECH PERF REQ] nor to maintain the IMT-2020 (5G) peak data rate numbers from the ITU-R M.2410 report.
Author’s Note: The IMT-2030 performance requirements in ITU-R M.[IMT-2030.TECH PERF REQ] are to be evaluated according to the criteria defined in Report ITU-R M.[IMT‑2030.EVAL] and Report ITU-R M.[IMT-2030.SUBMISSION] for the development of IMT-2030 recommendations within ITU-R WP5D.
……………………………………………………………………………………………………………………………………………………………………………….
Addendum – Measurements of top 5G network speeds:
- In the first half of 2025, Ookla said e& in the United Arab Emirates was the world’s fastest 5G network, noting a median upload speed of 52.21 Mbps. Other top performers like South Korea, Qatar, and Brazil also see median speeds well above 20 Mbps.
- U.S. performance: In the U.S., major carriers are in a close race. In mid-2024, Opensignal found Verizon with the fastest 5G upload speed at 21.2 Mbps, with T-Mobile close behind. However, as of early 2025, a separate Opensignal report credited T-Mobile with the fastest overall upload experience, at 17.9 Mbps, though that figure includes both 4G and 5G connections.
- European performance: Speeds vary across Europe. Ookla reported that in the first half of 2025, Magenta Telekom in Austria achieved a median 5G upload speed of 35.67 Mbps, while Three in the U.K. recorded a median of 13.07 Mbps.
- Rural vs. urban divide: Average 5G uplink speeds are often higher in urban areas where mid-band spectrum is more prevalent. However, as of mid-2023, Opensignal noted that the rural-urban gap for 5G upload speeds in the U.S. was narrowing due to increased rural investment.
- Dependence on network type: Whether a network uses 5G standalone (SA) or non-standalone (NSA) architecture impacts speeds. In early 2025, an analysis in the U.K. showed that while 5G SA had lower latency, 5G NSA still had a slightly higher proportion of high-speed uplink connections.
…………………………………………………………………………………………………………………………………………………………
References:
https://www.itu.int/pub/r-rep-m.2410-2017
3GPP Release 16 5G NR Enhancements for URLLC in the RAN & URLLC in the 5G Core network
IMT-2030 Technical Performance Requirements (TPR) from ITU-R WP5D
Key Objectives of WG Technology Aspects at ITU-R WP 5D meeting June 24-July 3, 2025
ITU-R WP5D IMT 2030 Submission & Evaluation Guidelines vs 6G specs in 3GPP Release 20 & 21
ITU-R: IMT-2030 (6G) Backgrounder and Envisioned Capabilities
Draft new ITU-R recommendation (not yet approved): M.[IMT.FRAMEWORK FOR 2030 AND BEYOND]
ITU-R M.2150-1 (5G RAN standard) will include 3GPP Release 17 enhancements; future revisions by 2025