China Mobile
China Mobile and Huawei Turn High-Speed Railway 5G-A into a Premium Service
Introduction:
China Mobile may have found a credible way to monetize 5G which has been one of the most persistent commercial problems for mobile network operators. The China state backed carrier aims to turn a 5G Advanced network into a consumer service Chinese people will pay for. On China’s Beijing–Shanghai high-speed railway, where trains operate at up to 350 km/h, China Mobile and Huawei have deployed a 5G-Advanced (5G-A) [1.] architecture that goes beyond coverage and peak-rate claims. The network is designed to identify passengers travelling aboard the train, differentiate them from users located near the rail corridor, recognize application-level performance requirements, and allocate radio and core-network resources accordingly.
Note 1. 3GPP & ITU-R Standardization Status: 5G-Advanced, incorporating enhancements from 3GPP Release 18 (the initial 5G-Advanced baseline), was included in the latest revision of Recommendation ITU-R M.2150-3 [IMT 2020 RIT/SRITs], which was approved in February 2026 as the latest 5G RAN standard.
3GPP Release 19 carries the official 5G-Advanced logo and introduces a wide array of advanced features and functional enhancements that expand upon Release 18, but it has not yet been contributed to ITU-R WP5D. That’s because ATIS and other 3GPP organizational partners are aligning upcoming submission timelines around the broader IMT-2030 (6G) guidelines. Release 19 functions as a transitional bridge. Elements of Release 19, alongside upcoming Release 20 studies, are being packaged as part of the broader baseline evaluation requirements leading up to the major IMT-2030 tech proposal window
……………………………………………………………………………………………………………………………………………………………………
The commercial proposition is straightforward: China Mobile wants to sell a differentiated connectivity experience rather than simply another nominal speed tier.
China Mobile’s 5G-A High-Speed Rail Premium Package effectively creates a premium service class within the public mobile network. According to China Mobile and Huawei, subscribers can receive data rates two to three times higher than those available through standard packages, particularly for latency-sensitive and bandwidth-intensive services such as video conferencing, livestreaming, and cloud gaming.
That makes the Beijing–Shanghai deployment more than an ambitious coverage project. It is an effort to operationalize contextual, application-aware quality differentiation at consumer scale.
Reliable connectivity aboard a train moving at 350 km/h is inherently difficult. Devices traverse cells rapidly, driving frequent handovers, while large numbers of passengers compete for capacity within a highly challenging RF environment. A train carriage also presents substantial propagation constraints: passengers are concentrated in a metal enclosure, and demand tends to be synchronized around high-bandwidth applications.
China Mobile has deployed dedicated capacity along the route using 2.6-GHz 8T8R and 700-MHz spectrum within a three-carrier 5G-Advanced network. Neither band is inherently unique. U.S. operators, for example, use 700-MHz low-band spectrum and hold substantial spectrum near 2.5 GHz. The distinctive element is China Mobile’s integration of those bands into a dedicated high-speed rail mobility architecture, combined with AI-assisted passenger classification and service prioritization.
China Mobile says that multiband load balancing, carrier aggregation, and Huawei’s train-specific power-adaptation technology improved perceived uplink performance by 38.5% and downlink performance by 9.5%. Those figures are vendor- and operator-reported measurements, rather than independently verified results, but they illustrate the priority placed on uplink and experience consistency as well as headline downlink rates. More important than the additional radio capacity, however, is the control layer built above it.

China Mobile and Huawei use AI on the Beijing–Shanghai high-speed rail line to sell premium 5G service, turning network control into revenue. (Source: Google Gemini)
…………………………………………………………………………………………………………………………………………………………………………..
The network identifies the passenger context:
China Mobile says it has integrated AI inference into the 5G core’s Network Data Analytics Function, or NWDAF. The system evaluates approximately three minutes of user mobility data—including speed, base-station transitions, and network topology—to determine whether a subscriber is travelling aboard the high-speed train or simply using the public network in proximity to the railway.
China Mobile claims that the system identifies high-speed rail passengers with more than 95% accuracy. Once a user has been classified as a railway passenger, the network can modify frequency-selection priorities to retain that subscriber on dedicated rail capacity while moving conventional public-network users to alternative resources.
The operator says that, at typical base stations, as many as 60% of non-rail users can be migrated off the rail-focused network layer.
That changes the network’s role. Rather than simply transporting packets across available capacity, the system interprets user context and uses that inference to make policy decisions about radio and core-network resource allocation.
In practical terms, the network is attempting to distinguish between two users who may be physically close to one another but have very different connectivity requirements:
This is a more sophisticated model than conventional consumer traffic management. The policy is not based solely on a static premium plan or a generic QoS marking. It is informed by mobility context, location, network topology, and application behavior.
From capacity to application experience:
China Mobile says its NWDAF can detect deteriorating application performance and dynamically establish dedicated guaranteed-bit-rate bearers for eligible subscribers and services.
In 2025, the company said the system could accelerate 27 applications across five categories. It now says that capability has expanded to 55 applications in six categories, including multistream acceleration for short-form video and livestreaming services.
Intelligent processing within the radio network adds a further control layer. China Mobile and Huawei describe millisecond-level optimization of rate, latency, power, and carrier selection for specific users and services.
The result begins to resemble an intelligent service-delivery platform rather than a conventional mobile broadband network.
That distinction matters because mobile operators have spent years seeking a viable monetization model for 5G capabilities such as network slicing, deterministic performance, differentiated QoS, and application-aware service delivery. Selling another increment of nominal speed to a subscriber who can already stream video without difficulty is not especially compelling. Selling a reliable, business-grade experience for a video meeting during a high-speed journey between Beijing and Shanghai is easier to understand—and potentially easier to monetize.
One proposition is additional bandwidth. The other is confidence that an important application will work when it matters.
China Mobile’s service branding reinforces that distinction. Premium subscribers receive a dynamic China Mobile HSR VIP logo on their devices, making the service tier visible as well as functional.
Why rail is a useful proving ground:
Railway environments are particularly suitable for testing this model because the value of performance differentiation is immediately apparent. A passenger trying to participate in a video conference, upload files, livestream, or access a cloud application does not particularly care whether the underlying network is branded as 5G, 5G-Advanced, or eventually 6G. The relevant question is whether the service works reliably.
That is why the Beijing–Shanghai deployment may have significance beyond China.
In the United Kingdom, Ofcom reported in June that mobile service was poor in between 58% and 83% of train tests, depending on the operator. Its benchmark for a good connection was modest: 5 Mbit/s downlink, 1.5 Mbit/s uplink, and latency of no more than 50 milliseconds—sufficient for an acceptable video call. Ofcom reported in June that those conditions frequently were not met.
China Mobile is using AI to determine which passenger’s video call should receive priority. Britain is still working to ensure that the connection is available at all.
London provides an instructive counterpoint. The Elizabeth line initially opened without mobile coverage. Transport for London now says that all Elizabeth line stations have 4G coverage and tunnel sections have both 4G and 5G coverage. The lesson is not that advanced, differentiated services are unnecessary. It is that the industry must first solve the basic infrastructure problem before it can credibly commercialize higher-value connectivity tiers.
China Mobile has moved beyond that initial engineering threshold. Its question is: what services become commercially viable once connectivity is reliable enough to manage and differentiate?
A broader 5G monetization model:
A search for comparable deployments did not identify another commercial rail service that combines 5G-Advanced, AI-based passenger identification, application-level performance detection, and premium consumer service differentiation in quite the same way.
Other railway initiatives are progressing, but generally toward a different goal. Germany, for example, is testing 5G standalone for railway communications, with an emphasis on the Future Railway Mobile Communication System, or FRMCS. In 2025, Deutsche Bahn began testing what Fierce Network described as the world’s first 5G-based FRMCS deployment on live outdoor tracks. The trial is focused on establishing next-generation railway communications capabilities.
The contrast is useful as per this table:
Both are valid applications of 5G. They address different buyers, operating models, and value chains.
Mobile operators have historically sold relatively blunt consumer products: minutes, messages, data allowances, and broad speed tiers. Fifth-generation networks promised more precise commercial tools, including slicing, service assurance, policy control, and differentiated quality. Translating those tools into consumer propositions has proved difficult, although the model has been more successful in industrial and enterprise deployments.
I saw one version of that industrial model at the East-West Gate intermodal terminal in Hungary, where Huawei private 5G provides the uplink capacity, reliability, and guaranteed latency required to automate railway logistics. The Beijing–Shanghai deployment applies a related technical proposition to a very different customer: the passenger.
That makes 5G’s consumer value proposition more tangible.
Huawei’s responses to FNTV’s questions on the case study are revealing. Additional spectrum and capacity establish the baseline experience; AI-based profiling and intelligent radio processing then provide the fine-grained resource management that improves it. Put simply: capacity creates the network, while control creates the product.
That distinction will become more important as operators seek to prevent connectivity from becoming a commodity.
Hyperscale cloud providers built highly profitable businesses in part by layering proprietary software, orchestration, and operational control above broadly available infrastructure. Telecom operators own valuable assets—licensed spectrum, radio access networks, transport, core networks, and increasingly distributed compute—but have struggled to translate those assets into differentiated, higher-margin services.
An intelligent mobile network provides a potential route forward.
T-Mobile has described a related direction in its own 5G standalone evolution, with AI moving from the cloud into the core and orchestration extending across core, radio, and device layers. T-Mobile executives described how AI is moving into its 5G standalone core. The underlying principle is similar: as operators gain more real-time intelligence and control across network domains, they can potentially tailor network behavior to individual customers, devices, applications, and contexts.
The operator owns the spectrum, operates the RAN, and controls the core. Increasingly, software and AI can determine how those assets behave for a particular subscriber or service. That control may have commercial value.
The commercial test remains ahead:
The deployment still raises important questions. The performance data supplied to FNTV are China Mobile and Huawei measurements and have not been independently verified. More significantly, the ultimate test is commercial: will subscribers consistently perceive enough difference in quality, reliability, and application performance to pay for premium treatment over time?
That said, the underlying proposition is credible. For frequent business travellers, reliable application performance during a high-speed rail journey is materially more valuable than an abstract claim of higher peak throughput.
I have covered railway communications ranging from Huawei’s private 5G deployment at Hungary’s East-West Gate terminal to the decidedly less futuristic reality of a German railway disruption linked to legacy 2G dependence in 2026. China Mobile is pushing the question one stage further: what happens after baseline connectivity becomes reliable?
The network becomes programmable. Then context-aware. Then intelligent. Finally, it becomes commercial. At 350 km/h between Beijing and Shanghai, China Mobile is beginning to demonstrate what that progression could look like. The route to 5G revenue may not be selling passengers a nominally faster network. It may be selling them a materially better journey.
Also see: GSMA Foundry — China Mobile case study: “Connecting High-Speed Rail Passengers”
…………………………………………………………………………………………………………………………………………………………………..
References:
https://www.fierce-network.com/wireless/china-mobile-takes-express-train-5g-revenue
https://www.gsma.com/get-involved/gsma-foundry/gsma_resources/connecting-high-speed-rail-passengers-china-mobile/ – Primary case-study source for the AI algorithm in the packet core, passenger identification, high-speed-rail connectivity optimization, and the broader China Mobile deployment concept
“China Mobile and Huawei Team Up to Launch AI-Powered 5G-A …” – Secondary coverage describing the reported architecture as a combination of a dedicated high-bandwidth 5G-A network for high-speed rail, an AI-native core, and intelligent network-management functions.
China Mobile & ZTE use digital twin technology with 5G-Advanced on high-speed railway in China
Nokia & Deutsche Bahn deploy world’s first 1900 MHz 5G radio network meeting FRMCS requirements
ZTE and China Telecom: 5G network test on a high speed train; Uplink enhancement FAST verification
KDDI, Samsung: 28GHz surveillance video call on train platform using 5G base station
Google’s Internet Access for Emerging Markets – Managed WiFi Network for India Railways
The AI Infrastructure Build-Out: A $10 Trillion Bet on Compute, Power, and Networks
Key take-aways: “16th Smart City and Intelligent Economy Expo” for Huawei, Alibaba & China’s three state backed carriers
Disclaimer: Perplexity.ai was used to research this article and generate the table below.
The 16th Smart City and Intelligent Economy Expo was held from September 11 to 13, 2026 in Ningbo, China. It was heavily backed by Huawei and China’s three state-backed carriers: China Telecom, China Mobile, and China Unicom. It covered more than 30,000 square meters in five halls, included more than 380 enterprises and institutions, and ran over 20 associated activities.
China’s three state backed carriers actively demonstrated next-generation network connectivity and Edge-AI integration. A major focus was “Human-Machine Symbiosis,” showcasing how 5G/6G network architectures and localized intelligent computing hubs handle full-chain robotic applications across commercial retail and public service systems.
Under the theme “AI Transformation for a Brighter Future,” the three-day event featured more than 380 enterprises displaying industrial robotics, consumer AI technologies, and smart city infrastructure. The municipal government of Ningbo, Zhejiang’s Department of Economy and Information Technology, the China Academy of Information and Communications Technology (CAICT), the China Electronics Industry Federation, China Telecom, China Mobile, and China Unicom co-hosted the event.

A Few Highlights:
- Huawei presented its latest-generation AI inference server equipped with the 950DT processor;
- Alibaba Cloud displayed its five-layer full-stack architecture “chip-cloud-model-inference-application” for the agent era;
- Kingdee released the Lingji AI-native platform;
- China Telecom exhibited the Stellar Super Agent (TeleAgent), China Mobile showcased the AI multi-model aggregation platform MoMA and 6G space-air-ground communication achievements, and China Unicom presented the Forbidden City digital twin platform and other integrated scenarios.
- Domestic GPUs from Xiwang, high-bandwidth memory from Liji Storage, RF filters from Xingyao Semiconductor, and other core chips in critical technology areas were on display.
- The National Manufacturing Digital Transformation Promotion Center premieres the AI-empowered direct-drive high-end industrial machine tool system developed by Academician Tan Jianrong’s team. Multiple academicians all attended this event.
The telecommunications narrative centered on an evolution from conventional network supply to intelligent-service infrastructure—combining AI platforms, next-generation access and transport, cloud resources, and sector-specific applications.
Digging Deeper:
The show also featured Alibaba Cloud’s five-layer “chip-cloud-model-inference-application” architecture for the agent era. Taken together with Huawei’s inference hardware and the operator platforms, the expo’s implicit architecture was a localized, vertically integrated AI stack: domestic chips and memory at the bottom; distributed cloud and compute in the middle; foundation and domain models above that; and agents, robots, digital twins, industrial systems, and public-service applications at the top.markets.financialcontent
“Human-Machine Symbiosis” and robotics:
The most visible new exhibit was the inaugural “Human-Machine Symbiosis” area. Nearly 10 leading companies showcased the full robotics chain, including a physical exploded-view presentation of humanoid-robot components and more than 30 robots demonstrating use cases in commercial retail, public services, and other environments.markets.financialcontent
The significance is less the robot count than the framing. Rather than isolating humanoid robots as a hardware novelty, the expo connected them to:
-
Component supply chains and embodied-AI systems.
-
On-site operational use cases in retail and public-service environments.
-
AI models and agent platforms.
-
Industrial automation and multi-robot coordination.
-
Communications and compute infrastructure capable of supporting distributed sensing, inference, command, and operations.
That linkage was strengthened by the new “Embodied Intelligence in Factories” section, which brought four working production lines into the exhibition venue. Junpu Intelligence showed a multi-robot collaborative precision-assembly line for battery-management systems. This shifts the conversation from humanoid-robot demonstrations toward production-grade orchestration: multiple machines, shared spatial awareness, task allocation, machine vision, industrial control, and quality processes.markets.financialcontent
Network and edge-AI implications:
The Ningbo event did not establish that commercial 6G is available today; rather, it used 6G achievements and space-air-ground concepts to signal the network requirements anticipated for AI-driven physical systems. For nearer-term deployment, the relevant foundations are 5G/5G-Advanced, private cellular, cloud-edge orchestration, AI-native core evolution, and localized inference.
The technical logic is straightforward:
-
Robots need local response. Safety, manipulation, navigation, machine vision, and multi-robot collaboration can require low and predictable latency, so inference and control cannot always reside in a distant centralized cloud.
-
Local compute hubs become operational nodes. Edge or on-premises AI infrastructure can host vision-language-action models, smaller specialized models, digital-twin data, real-time analytics, and orchestration functions close to factories, stores, campuses, or municipal sites.
-
Networks must coordinate, not simply connect. A physical-AI application needs reliable device connectivity, traffic prioritization, security, device management, data transport, service exposure, and integration between local and centralized computing domains.
-
The network itself becomes AI-enabled. Huawei has articulated a three-layer approach spanning network-element intelligence, network intelligence, and business intelligence. The stated objective includes better equipment efficiency, full-domain operations and maintenance, and agentic AI functions embedded into the core-network environment.
-
Space-air-ground integration expands the operational domain. China Mobile’s 6G space-air-ground showcase aligns with a broader Chinese operator narrative around supporting drones, vehicles, remote assets, low-altitude networks, and eventually wider-area AI services. Huawei likewise links future AI-enabled services to 3GPP non-terrestrial-network integration, although this remains a developing standards and deployment agenda rather than a near-term replacement for terrestrial 5G infrastructure.
The event’s central significance is that China’s state-backed operators are increasingly presenting themselves as AI infrastructure companies with communications assets, rather than communications companies adding isolated AI features. This has several implications:
-
Operators are moving up the stack. China Telecom’s agent and token-facing model, China Mobile’s multi-model platform, and China Unicom’s digital-twin applications all extend beyond access, transport, and traditional cloud resale.
-
Embodied AI creates a new justification for edge networks. Robotics, industrial automation, public-service machines, and mixed physical/digital workflows can make distributed compute and managed connectivity commercially relevant in ways that generic enterprise AI has not always done.
-
Domestic technology self-sufficiency is a material theme. The presence of domestic GPUs, high-bandwidth memory, RF filters, server platforms, and Chinese cloud/model providers shows that the event was as much about indigenous AI infrastructure as end-user applications.
-
Smart-city deployment is becoming a proving ground. Retail, public services, manufacturing, digital twins, education, healthcare, mobility, and city operations offer live environments in which operators can bundle connectivity, AI, cloud, security, integration, and managed services.
-
The most immediate opportunity is 5G-A plus edge AI, not 6G. The expo’s 6G language is strategic positioning. Deployable value over the next few years is more likely to come from 5G-Advanced/private wireless, cloud-edge compute, AI agents, computer vision, and integrated management platforms.
Conclusions:
More broadly, the Ningbo expo fits the national telecom-industry message visible at MWC Shanghai 2026: China Mobile, China Telecom, and China Unicom are already associating advanced mobile networks with humanoid robotics, drones, autonomous vehicles, and AI-enabled services. Huawei, meanwhile, is promoting AI-native network evolution and future 6G/NTN integration as the longer-horizon foundation for an “intelligent world.”
After 16 years of dedication to the digital intelligence track, the Smart City and Intelligent Economy Expo has become an important platform for showcasing city image and promoting industrial cooperation. Ningbo has fully implemented the “AI+” initiative, with the city’s digital economy added value exceeding one trillion yuan for the first time in 2025, reaching 1,059.15 billion yuan and accounting for 56.6% of GDP.
……………………………………………………………………………………………………………………………………………………………………………….
References:
Analysis & Economic Implications of AI adoption in China
China vs U.S.: Race to Generate Power for AI Data Centers as Electricity Demand Soars
China’s open source AI models to capture a larger share of 2026 global AI market
China’s telecom industry rapid growth in 2025 eludes Nokia and Ericsson as sales collapse
China ITU filing to put ~200K satellites in low earth orbit while FCC authorizes 7.5K additional Starlink LEO satellites
China gaining on U.S. in AI technology arms race- silicon, models and research
U.S. export controls on Nvidia H20 AI chips enables Huawei’s 910C GPU to be favored by AI tech giants in China
China’s state owned telcos slash CAPEX to the lowest in decades!
Goldman Sachs: Big 3 China telecom operators are the biggest beneficiaries of China’s AI boom via DeepSeek models; China Mobile’s ‘AI+NETWORK’ strategy
Omdia: Huawei increases global RAN market share due to China hegemony
China Telecom’s 2025 priorities: cloud based AI smartphones (?), 5G new calling (GSMA), and satellite-to-phone services
.
China’s telecom industry rapid growth in 2025 eludes Nokia and Ericsson as sales collapse
According to a Chinese government update, “Telecommunications business volume and revenue grew steadily, mobile internet access traffic maintained rapid growth, and the construction of network infrastructure such as 5G, gigabit optical networks, and the Internet of Things was further promoted.”
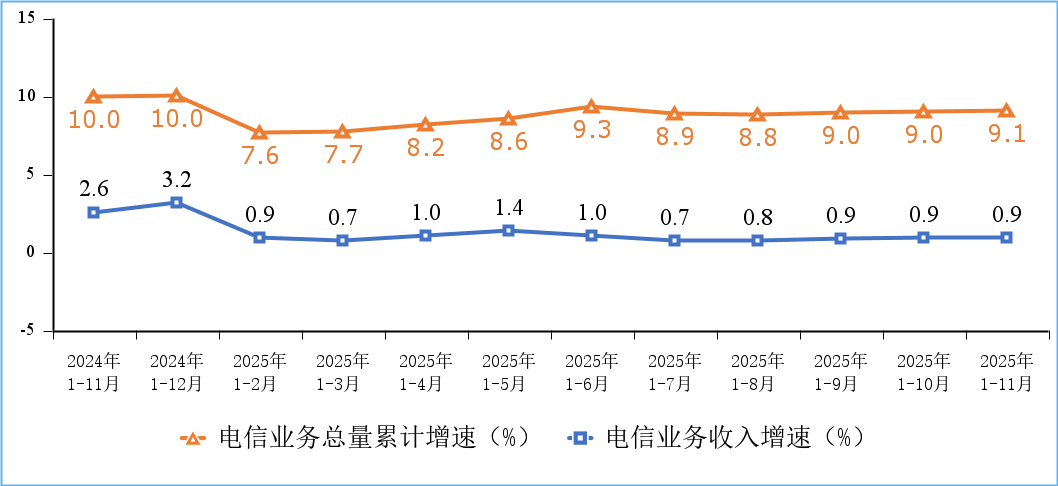
Figure 1. Cumulative growth rate of telecommunications service revenue and total telecommunications service volume
There were 4.83 million 5G base stations in service in China at the end of November 2025, an increase of 579,000 since late 2024 and 37.4% of the total number of mobile base stations in China. In one year, China claims to have added more 5G base stations than Europe has installed since the 5G technology was first put into service.
The total number of mobile phone users of the top four Chinese telcos (China Mobile, China Telecom, China Unicom, China Broadcasting Network) reached 1.828 billion, a net increase of 38.54 million from the end of last year. Among them, 5G mobile phone users reached 1.193 billion, a net increase of 179 million from the end of last year, accounting for 65.3% of all mobile phone users.
Meanwhile, the total number of fixed broadband internet access users of the three state owned telecom operators (China Mobile, China Telecom and China Unicom) reached 697 million, a net increase of 27.12 million from the end of last year. Among them, fixed broadband internet access users with access speeds of 100Mbps and above reached 664 million, accounting for 95.2% of the total users; fixed broadband internet access users with access speeds of 1000Mbps and above reached 239 million, a net increase of 32.52 million from the end of last year, accounting for 34.3% of the total users, an increase of 3.4 percentage points from the end of last year.
The construction of gigabit fiber optic broadband networks continues to advance. As of the end of November, the number of broadband internet access ports nationwide reached 1.25 billion, a net increase of 48.11 million compared to the end of last year. Among them, fiber optic access (FTTH/O) ports reached 1.21 billion, a net increase of 49.42 million compared to the end of last year, accounting for 96.8% of all broadband internet access ports. As of the end of November, the number of 10G PON ports with gigabit network service capabilities reached 31.34 million, a net increase of 3.133 million compared to the end of last year.
The penetration rate of gigabit and 5G users continued to increase across all regions. As of the end of November, the penetration rates of fixed broadband access users with speeds of 1000Mbps and above in the eastern, central, western, and northeastern regions were 34.6%, 33.8%, 35.8%, and 28.5%, respectively, representing increases of 3.4, 2.6, 4.1, and 4.9 percentage points compared to the end of last year; the penetration rates of 5G mobile phone users were 64.9%, 65.9%, 65.1%, and 65.9%, respectively, representing increases of 8.2, 8.7, 8.8, and 9.6 percentage points compared to the end of last year.
…………………………………………………………………………………………………………………………………………………………………
Separately, Light Reading reports that Ericsson and Nokia sales of networking equipment to China have collapsed.
Ericsson recently published earnings release for the final quarter of 2025 puts China revenues at just 3% of total sales last year. This would equate to revenues of 7.1 billion Swedish kronor (US$798 million). Based on a rounding range of 2.5% to 3.4%, it works out to be between SEK5.92 billion ($665 million) and SEK8.05 billion ($905 million) – down sharply compared with the SEK10.2 billion ($1.15 billion) Ericsson made in 2024, according to that year’s Ericsson annual report.
Nokia does not break out details of revenues from mainland China, instead lumping them together with the sales it generates in neighboring Hong Kong and Taiwan. But this “Greater China” business is in decline. Total annual revenues – which include Nokia’s sales of fixed, Internet Protocol and optical network products, as well as 5G – slumped from almost €2.2 billion ($2.6 billion) in 2019 to around €1.5 billion ($1.8 billion) in 2020, before creeping back up to nearly €1.6 billion ($1.9 billion) by 2022. Two years later, they had fallen to about €1.1 billion ($1.3 billion).
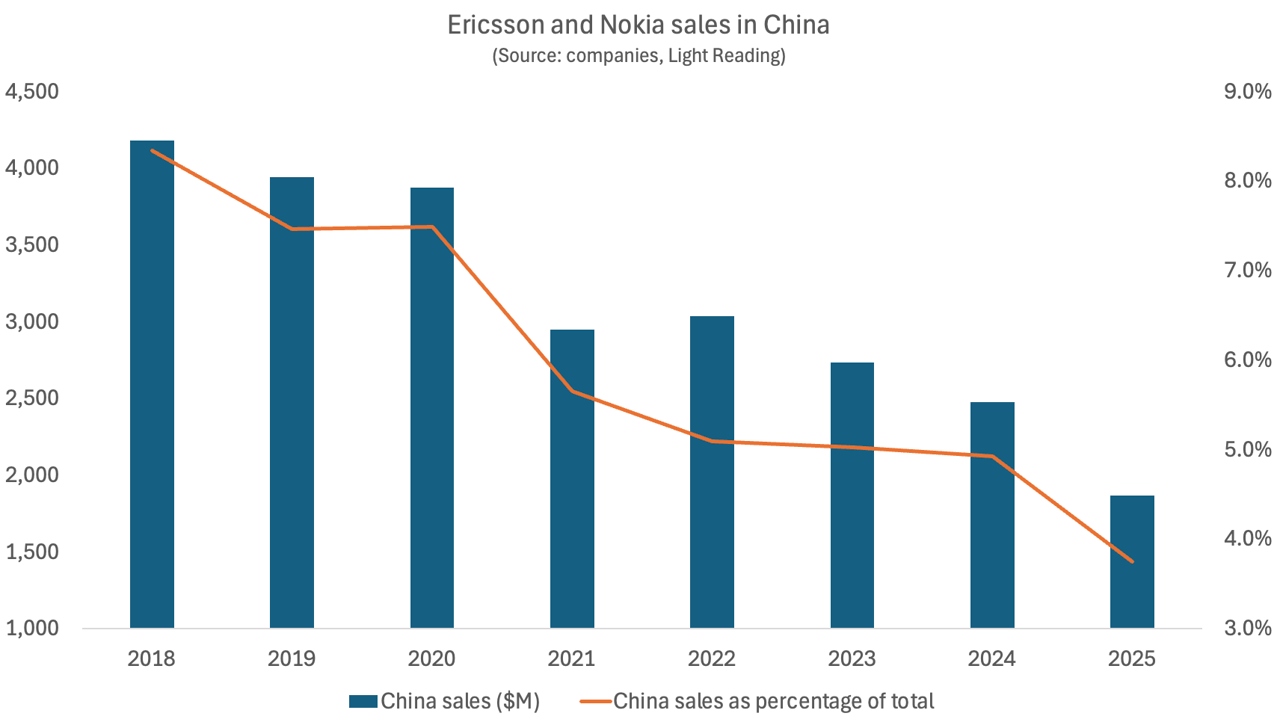
Bar Chart Credit: Light Reading
Nokia has recently indicated the complete disappearance of its China business. “Western suppliers, which is only us and Ericsson, have 3% market share now in China and it’s been coming down, and we are going to be excluded from China for national security reasons,” said Tommi Uitto, the former president of Nokia’s mobile networks business group, at a September press conference in Finland also attended by Justin Hotard, Nokia’s CEO. It implies China’s government is now treating the Nordic vendors in the same way Europe and the U.S. are banning Huawei and ZTE networking equipment.
Nokia revealed in its latest earnings update that Greater China revenues for 2025 had fallen by another 19%, to €913 million ($1.08 billion) – just 42% of what Nokia earned in the region seven years earlier. In the last few years, moreover, Nokia has cut more jobs in Greater China than in any other single region. While figures are not yet available for 2025, the Greater China headcount numbered 8,700 employees in 2024, down from 15,700 in 2019.
Ericsson has significantly reduced its China operations following greatly reduced 5G market share. In September 2021, the company consolidated three operator-specific customer units into a unified structure, impacting several hundred sales and delivery roles within its ~10,000-person local workforce. This followed the divestment of a Nanjing-based R&D center (approx. 650 employees), aligning with strategic pivots away from legacy 2G-4G technologies. The company’s total workforce in Northeast Asia plummeted from about 14,000 in mid-2021 to roughly 9,500 at the end of last year, according to Ericsson’s financial statements.
Exclusion from China would leave Ericsson and Nokia on the outside of the world’s most promising 6G market in 2030. That would intensify concern about a bifurcation of 6G into Western and Chinese variants of IMT 20230 RIT/SRIT standard and the 3GPP specified 6G core network.
……………………………………………………………………………………………………………………………………….
References:
https://www.miit.gov.cn/gxsj/tjfx/txy/art/2025/art_7514154ec01c42ecbcb76057464652e4.html
https://www.lightreading.com/5g/ericsson-and-nokia-see-their-sales-in-china-fall-off-a-cliff
https://www.mordorintelligence.com/industry-reports/china-telecom-market
China’s open source AI models to capture a larger share of 2026 global AI market
Goldman Sachs: Big 3 China telecom operators are the biggest beneficiaries of China’s AI boom via DeepSeek models; China Mobile’s ‘AI+NETWORK’ strategy
China Telecom’s 2025 priorities: cloud based AI smartphones (?), 5G new calling (GSMA), and satellite-to-phone services
China ITU filing to put ~200K satellites in low earth orbit while FCC authorizes 7.5K additional Starlink LEO satellites
China gaining on U.S. in AI technology arms race- silicon, models and research
China ITU filing to put ~200K satellites in low earth orbit while FCC authorizes 7.5K additional Starlink LEO satellites
- Purpose: The planned systems are intended to provide global broadband connectivity, data relay, and positioning services, directly competing with U.S. efforts like SpaceX’s Starlink network.
- Filing Entities: The primary filings were submitted by the state-backed Institute of Radio Spectrum Utilization and Technological Innovation, along with other commercial and state-owned companies like China Mobile and Shanghai Spacecom.
- Status: These filings are an initial step in a long international regulatory process and serve as a claim to limited spectrum and orbital slots. They do not guarantee all satellites will ultimately be built or launched. The actual deployment will be a gradual process over many years.
- Context: The move is part of an escalating “space race” to dominate the LEO environment. Early filings are crucial for securing priority access to orbital resources and avoiding signal interference. The sheer scale of the Chinese proposal would, if realized, dwarf most other planned constellations.
- Regulations: Under ITU rules, operators must deploy a certain percentage of the satellites within seven years of the initial filing to retain their rights.
- Shanghai Yuanxin (Qianfan), currently China’s most advanced LEO satellite operator, has submitted a regulatory request for an additional 1,296 satellites.
- Telecommunications giant China Mobile is planning two separate constellations totaling 2,664 satellites.
- ChinaSat, the established state-owned satellite provider, is focusing on a 24-satellite medium-Earth orbit (MEO) system.
- GalaxySpace, a private satellite manufacturer based in Beijing, has applied for 187 satellites, and China Telecom has applied for 12.
Image Credit: Klaus Ohlenschlaeger/Alamy Stock Photo
“This gives SpaceX what they need for the next couple of years of operation. They’re launching a bit over 3,000 satellites a year, so 7,500 satellites being authorized is potentially enough for SpaceX to do what they want to do until late 2027,” said Tim Farrar, satellite analyst and president at TMF Associates.
SpaceX has plans for a larger D2D satellite constellation that would use the AWS-4 and H-block spectrum it is acquiring from EchoStar. It is awaiting FCC approval for the US$17 billion deal, but the spectrum is not expected to be transferred until the end of November 2027.
The FCC noted that the changes will allow the Starlink system to serve more customers and deliver “gigabit speed service.” Along with permission for another tranche of satellites, the FCC has set new parameters for frequency use and lower orbit altitudes. The modified authorizations will also apply to new satellites to be launched.
Starlink’s LEO satellite network competitors are Amazon Leo, OneWeb and AST Space Mobile.
………………………………………………………………………………………………………………………………………………………..
References:
U.S. BEAD overhaul to benefit Starlink/SpaceX at the expense of fiber broadband providers
Huge significance of EchoStar’s AWS-4 spectrum sale to SpaceX
Telstra selects SpaceX’s Starlink to bring Satellite-to-Mobile text messaging to its customers in Australia
SpaceX launches first set of Starlink satellites with direct-to-cell capabilities
SpaceX has majority of all satellites in orbit; Starlink achieves cash-flow breakeven
Amazon Leo (formerly Project Kuiper) unveils satellite broadband for enterprises; Competitive analysis with Starlink
NBN selects Amazon Project Kuiper over Starlink for LEO satellite internet service in Australia
GEO satellite internet from HughesNet and Viasat can’t compete with LEO Starlink in speed or latency
Amazon launches first Project Kuiper satellites in direct competition with SpaceX/Starlink
Vodafone and Amazon’s Project Kuiper to extend 4G/5G in Africa and Europe
China’s state owned telcos slash CAPEX to the lowest in decades!
China’s big three state-owned telecom operators are drastically slashing capital expenditures (CAPEX) before the next wave of heavy spending on 6G mobile network infrastructure beginning in 2030. Over a year ago, the IEEE Techblog reported the planned CAPEX reductions in this post.
- China Telecom expects its capital expenditure to decline by 11% to 83.6 billion yuan in 2025, returning to pre-5G expansion levels.
- China Mobile also plans to cut its capital expenditure by 8% in 2025, bringing spending close to 2012 levels.
- China Unicom, the smallest of the three, recorded the sharpest drop in spending.
Reasons for the Cuts:
- The 5G network infrastructure buildout has largely reached its peak, with China already having 3.5 million 5G base stations.
- The companies are preparing for the next major investment cycle, which is expected to focus on 6G and AI infrastructure.
- The CAPEX cuts are also being driven by government directives to improve market value and increase shareholder dividends.
- The companies are prioritizing investments in AI infrastructure and computational infrastructure.
- China Mobile’s Chairman Yang Jie stated that the next major investment cycle is expected to focus on 6G and is unlikely to begin before 2028.
………………………………………………………………………………………………………………………………………………………………………………………………………………………………….
1. China Mobile, the largest wireless carrier in China with over 1 billion subscribers, slashed its annual capital expenditure by over 9% to 164 billion yuan in 2024. The company plans to cut another 8% this year to 151.2 billion yuan. That amount is approaching the 2012 level of 127.4 billion yuan, and is set to decline further in the years to come.
“The overall investment size in the next two to three years will continue to steadily fall,” Yang Jie, China Mobile’s chairman, told reporters in Hong Kong last Thursday. Asked what would trigger the next capital spending spree, Yang said: “From what I see now, the next investment peak will be on 6G” — but he expects that to kick off around 2028. Until then, the industry veteran expects “the proportion of investment to expand in the areas of computation and AI.”

China Mobile Chairman Yang Jie told reporters in Hong Kong on March 20 that the next telecom investment peak would be for 6G mobile network building. (Photo by Kenji Kawase)
Jefferies telecom analyst Edison Lee, said China Mobile’s capex figures were “lower than expected.” The ratio versus its revenue was 18% last year, marking the first dip below 20%, and he expects this proportion to further sink to 16% this year. “This is negative for equipment vendors such as ZTE,” Lee said, although it provides more room for returns to shareholders.
2. China Telecom (#2 in China) announced on Tuesday that its CAPEX for 2024 came to 93.51 billion yuan ($12.9 billion), 5% lower than the previous year. The forecast for this year is even lower, at 83.6 billion yuan, down 11% and lowering the amount to the level before the peak 5G network investment years of around 2020 to 2023. However, with soaring demand for AI computing, it plans a further hike in digital infrastructure spending. It will boost investment in cloud computing and data centers by 22% to RMB45.5 billion ($6.3 billion), making it the biggest single capex item, accounting for 38% of the total.
The company said it’s focused on four technology directions: network, cloud and cloud-network integration, AI and quantum security. It revealed it had deployed 70,000 5G-A base stations in 121 cities, with 5G RedCap coverage in more than 200 cities, and said it had signed up 2.4 million subs to its pioneering D2D mobile satellite service.
Chairman Ke Ruiwen told Nikkei Asia that “the general trend is heading downward.” He added that “before building the new large-scale network (apparently referring to 6G), the investment trend is going continue falling.” He said the company would continue to pursue its strategy focused on cloud and digital transformation.
Source: Cynthia Lee/Alamy Stock Photo
3. China Unicom, the smallest of the three state owned telcos, also slashed its capital spending by 17% to 61.37 billion yuan in 2024, while planning a further reduction to 55 billion yuan this year. “Our investment emphasis has already shifted away from mobile broadband to computing network capabilities for internet data centers and cloud,” said Tang Yongbo, Unicom’s vice president. He also mentioned the impending heavy investment period when the 6G era arrives.
China Telecom and China Unicom have a “co-build, co-share” partnership for 5G investment.
…………………………………………………………………………………………………………………………………………………………………………………………………………………
All three Chinese network operators’ actual capital expenditure in 2024 were lower than the previous guidance they had provided, by an average of 5%. The sum of annual capital expenditure for the three Chinese telcos was 319 billion yuan for 2024, and the combined estimate for 2025 is 289.8 billion yuan. Including China Tower — a tower builder established in 2014 through a merger of the three telecom companies’ related businesses, and publicly listed in 2018 — the total capex last year was 351 billion yuan. This year’s projected amount of 322 billion yuan would be one of the lowest in decades.
References:
https://www.lightreading.com/finance/china-telecom-boosts-profit-cuts-capex
China Mobile & China Unicom increase revenues and profits in 2023, but will slash CAPEX in 2024
Dell’Oro: Global telecom CAPEX declined 10% YoY in 1st half of 2024
Omdia: Huawei increases global RAN market share due to China hegemony
Goldman Sachs: Big 3 China telecom operators are the biggest beneficiaries of China’s AI boom via DeepSeek models; China Mobile’s ‘AI+NETWORK’ strategy
According to a new research report from Goldman Sachs-China, the three major, state owned telecom operators (China Mobile, China Telecom, China Unicom) are quietly becoming the core beneficiaries of China’s AI boom. One reason is that, thanks to their deployment of China’s most extensive cloud infrastructure, they can serve other cloud companies as well as provide their own cloud services to their end user customers. They also enjoy the cost and scale advantages of owning their own data centers and bandwidth. For some IaaS companies, data center and connectivity together account for as much as 60% of total expense, according to Goldman-China.
Goldman analysts believe that telecom operators’ cloud businesses have obvious cost advantages compared to other cloud companies. Those are the following:
- The big 3 Chinese network operators have built their own Data Centers (DCs) and so do not rely on external DC service providers. They even provide DC services to other cloud companies such as Alibaba, which makes the IDC expenses of their cloud business lower.
- The bandwidth cost of operator cloud business is significantly lower than that of other cloud companies because operators use their own network infrastructure, while other cloud companies need to pay operators for bandwidth and private network fees connecting different data centers.
- For the IaaS cloud business, if external DC and bandwidth are used, data center costs (DC services and bandwidth) will account for a considerable proportion of the total cost of the cloud company. Goldman cites QingCloud Technology as an example, its data center costs (including cabinets, bandwidth, etc.) account for 50%-60% of its total costs.
Looking ahead, the telcos are strongly placed to take advantage of the DeepSeek AI boom, thanks to their early embrace of DeepSeek and the government’s push to promote AI among the state-owned enterprises that account for about 30% of operator revenue, Goldman argues. The report states, “the state-owned enterprise background makes the deployment of AI/Deepseek by government agencies and state-owned enterprises more beneficial to telecom operators.”
In the past two weeks, China’s three major operators have begun to help important customers deploy DeepSeek models. China Mobile supports PetroChina in deploying a full-stack Deepseek model; China Telecom provides the same service to Sinopec; and China Unicom cooperates with the Foshan Municipal Bureau of Industry and Information Technology. More importantly, the State-owned Assets Supervision and Administration Commission of the State Council (SASAC) launched the “AI+” action plan on February 21 to encourage Chinese state-owned enterprises to accelerate the development and commercial application of AI. According to Goldman Sachs research, government-related customers account for about 30% of telecom operators’ cloud revenue. Therefore, the deployment of AI/DeepSeek by government agencies and state-owned enterprises will clearly benefit telecom operators.
Separately, China Mobile announced at Mobile World Congress 2025 in Barcelona that it is leveraging artificial intelligence to transform telecommunications networks and drive unprecedented data growth while positioning itself at the forefront of AI-Native network innovation. China Mobile Executive Vice President Li Huidi outlined the company’s ambitious “AI+NETWORK” strategy in a keynote address titled “AI+NETWORK, Pioneering the Digital-Intelligent Future” during the Global MBB Forum Top Talk Summit on Sunday.

Li Huidi, executive vice president of China Mobile, speaks at the Global MBB Forum Top Talk Summit at Mobile World Congress in Barcelona, Spain, March 2, 2025. (Photo/China Mobile)
…………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………….
References:
https://wallstreetcn.com/articles/3741901 (Chinese)
https://www.telecoms.com/partner-content/china-mobile-unveils-ai-network-strategy-at-mwc
https://www.lightreading.com/ai-machine-learning/china-telcos-rush-to-embrace-deepseek
China Telecom’s 2025 priorities: cloud based AI smartphones (?), 5G new calling (GSMA), and satellite-to-phone services
China adds 20M “5G package” subscribers in July; 1H-2024 earnings gains outpace revenues for all 3 major China telcos
The number of 5G subscribers in China increased by a sizeable 20 million last month, according to new data from the country’s big three state owned network providers (China Mobile, China Telecom, China Unicom). Of the three, China Mobile is still the only one to report actual customers using its 5G network; China Telecom and China Unicom are sticking to their 5G package subscribers metric, which essentially means customers signed up to a 5G plan, regardless of whether they use 5G network services (most continue to use 4G).
- China Mobile’s July net adds came in at 13.7 million, pushing its 5G customer base up to a colossal 528 million. China Mobile disclosed that it has 129 million customers using its 5G New Calling over high-definition video service reached 129 million, of which, smart application subscribers numbered 11.82 million.
- China Telecom added 3.1 million 5G package customers for a total of 340 million. They did not talk about 5G in their earnings report (more below).
- China Unicom added 2.9 million 5G package customers for a total of 279 million. China Unicom shared details of its 5G network build-out, pointing out that its 5G mid-band base stations numbered in excess of 1.31 million as of mid-year, while low-band sites reached 780,000.
For each of them, cloud and digital transformation (rather than 5G subs) drove topline growth, profit rose more than revenue and shareholder returns increased.
- China Mobile said net profit had improved 5.3% to RMB80.2 billion ($11.2 billion), outpacing revenue, which rose 3% to RMB546.7 billion ($76.6 billion).
- China Telecom, reported net earnings of 21.8 billion Chinese yuan (US3.1 billion), an 8.2% gain over last year, with revenue up 2.8% and service revenue 4.3% higher.
- China Unicom reported 11.3% higher net income of 13.8 billion ($1.93) on the back of a 2.9% lift in sales to RMB197.3 billion ($27.6 billion).
China Mobile says its digital transformation business grew 11% to RMB147.1 billion ($20.6 billion), accounting for 26% of all revenue. China Telecom reported digital industry sales of RMB73.7 billion ($10.3 billion), a 7% increase, and China Unicom said revenue grew 7% to RMB43.5 billion ($6.1 billion).
Source: Cynthia Lee/Alamy Stock Photo)
All three state owned telcos experienced double-digit growth in cloud services. China Telecom’s Tianyi Cloud grew revenue by 20% to RMB55 billion ($7.7 billion), while China Mobile Cloud hiked sales by 19% to RMB50 billion ($7 billion) and China Unicom grew 24% to RMB32 billion ($4.5 billion).
…………………………………………………………………………………………………………………………………………………………………………………………………………………..
Silence is Golden?
There was a distinct lack of 5G commentary in China Telecom’s half year report; it is the last of the three to post numbers and did so alongside the publication of the market’s operational statistics for July. The telco shared its 5G package figures – it added almost 18 million in the first six months of 2024, incidentally – but made no other reference to the technology in a fairly wordy statement about its year-to-date performance. Instead, the operator focused on the progress of its digital transformation strategy, leaning heavily on the promise of artificial intelligence. Specifically, China Telecom is talking up what it terms AI+ – there’s always one – and the Xingchen large language model it launched at the back end of last year.
“The Company strengthened the integration and mutual promotion of capabilities in various fields, continuously enriched the Xingchen large model series product portfolio, empowered the intelligent transformation for thousands of industries, and supported enterprises to achieve costs reduction and efficiency enhancement,” it said.
…………………………………………………………………………………………………………………………………………………………………………………………………………………..
References:
https://www.telecoms.com/5g-6g/china-added-20-million-5g-subs-last-month
https://www.lightreading.com/finance/cloud-digital-transformation-drive-chinese-telcos-h1-growth
GSMA: China’s 5G market set to top 1 billion this year
MIIT: China’s Big 3 telcos add 24.82M 5G “package subscribers” in December 2023
China Telecom and China Mobile invest in LEO satellite companies
WSJ: China’s Telecom Carriers to Phase Out Foreign Chips; Intel & AMD will lose out
China’s telecom industry business revenue at $218B or +6.9% YoY
China Telecom and China Mobile invest in LEO satellite companies
Two of China’s state-owned telcos have taken stakes in new LEO satellite companies.
- China Telecom has set up a new fully owned subsidiary, Tiantong Satellite Technology Co., registered in Shenzhen with 1 billion Chinese yuan (US$138 million) paid-in capital. China Telecom, which is currently the only operator with a mobile satellite license, operates three Tiantong Geo orbit satellites, launched between 2016 and 2021, covering China, the western Pacific and its neighbors.
- In April China Mobile took a 20% stake in a new RMB4 billion ($551 million) state-owned company, China Shikong Xinxi Co., registered in Xiongan. China Satellite Network Group, the company behind Starnet, China’s biggest LEOsat project, will own 55%, and aerospace contractor Norinco, a 25% shareholder.
China Telecom will shutter its legacy satellite subsidiary, established in 2009, and transfer the assets into the new company.
The other new business, China Shikong, lists its scope as satellite communication, satellite navigation and remote sensing services.
The two investments come as China Starnet is readying to launch its first satellites in the second half of the year. It is aiming to build a constellation of 13,000, with the first 1,300 going into operation over the next five years, local media has reported.

In addition to Starnet, two other mass constellations are planned – the state-owned G60 and a private operator, Shanghai Hongqing. Neither has set a timetable. They will be playing catch up with western operators like Starlink and OneWeb, which are already operating thousands of commercial satellites.
Since foreign operators are forbidden from selling into China, it is not yet clear how China is going to structure its LEO satellite industry and what role precisely the new operators are going to play.
References:
Chinese telcos tip cash into satellite (lightreading.com)
China Mobile launches LEO satellites to test 5G and 6G – Developing Telecoms
Very low-earth orbit satellite market set to reach new heights | TelecomTV
5G connectivity from space: Exolaunch contract with Sateliot for launch and deployment of LEO satellites
LEO operator Sateliot joins GSMA; global roaming agreements to extend NB-IoT coverage
Momentum builds for wireless telco- satellite operator engagements
Satellite 2024 conference: Are Satellite and Cellular Worlds Converging or Colliding?
China Mobile reports record operating revenues in 1st Quarter 2024
China Mobile, the world’s largest operator in terms of subscribers, recorded operating revenues of CNY263.7 billion ($36.4 billion) in the first quarter of the year, an increase of 5.2% year-on-year, the carrier said in its earnings statement. The company’s net profit increased 5.5% year-on-year to CNY29.6 billion. Also, the telco reported that revenue from telecommunications services was CNY219.3 billion, up by 4.5% year-on-year. The telco ended the first quarter of the year with a total of 488 million 5G subscribers. China Mobile had reported a net addition of 138 million 5G subscribers during 2023. In the mobile segment, the telco reached a total of 996 million subscribers at the end of March 2024, after an addition of 5 million customers during the first quarter.
Highlights:
- Adopt a strategy-led approach, driving new milestones in business performance
- Leverage innovation, deepening strategic transformation with remarkable results
- Expedite further business upgrade, facilitating mutual advancement of the “two new elements”
- Achieve breakthroughs amidst adversity, yielding fruitful results from innovation and reform Dedicated to enhancing shareholder returns, using a multi-pronged approach Forge ahead with determination, accelerating the building of a world-class enterprise
Mr. Yang Jie, Chairman of the Company commented, “In 2023, despite various challenges faced by the Company in a complex and severe macro- environment, we seized the opportunities emerging from accelerated economic and social digital transformation. This helped anchor us in our position as a world class information services and sci-tech innovation enterprise. Our efforts were focused on fully implementing our “1-2-2-5” strategy and strengthening innovation and core competitiveness to promote high-quality and sustainable development. Our business results reached new milestones, with revenue surpassing the RMB trillion mark for the first time in our history of development, and net profit attaining a record high. In terms of operations, our strategic transformation, reforms and innovation all advanced to a new level, underscoring our solid progress in establishing a world-class enterprise that takes pride in outstanding products, reputable brands, leading innovation and modern governance.”
“The Group will continue to pursue stable progress while forging ahead with a steadfast focus on integrity and innovation. We will enhance core functions, improve core competitiveness, expedite the cultivation and growth of emerging sectors of strategic importance, develop new quality productive forces at an accelerated pace, and establish ourselves as a world-class information services and sci-tech innovation enterprise to a high standard. With these efforts, we will consistently create greater value for our shareholders and customers,” the China state owned telco said.
China Mobile plans to launch 5G-Advanced (5G-A) technology in over 300 cities across China this year, according to local press reports. The telco, which claims a leading role in the development of 5G-A 3GPP specifications, also plans to promote the release of over 20 5G-A compatible phones within the year. To showcase its new 5G-A network, China Mobile has established 5G-A demonstration halls in various locations across China.
China Mobile’s vice president, Gao Tongqing, stated that this launch will further accelerate the development of new information infrastructure and unlock the full potential of 5G technology. The carrier also said it aims to achieve widespread adoption of 5G-A technology in China through partnerships with manufacturers and chip suppliers.
Beijing, Shanghai and Guangzhou are among the first cities where China Mobile will activate the new technology.
China had a total of 11.6 million mobile communication base stations as of the end of last year, of which 3.4 million were 5G base stations. 5G base stations currently account for nearly 29% of total mobile base stations in China. The ratio is 7.8 percentage points higher compared to the end of 2022.
Future Outlook:
The impact of the new wave of technological revolution and industrial reforms will continue to grow, so will the importance of integrated innovation. The three aspects of this integrated innovation will be highlighted in the power of information, the new generation information technology, and the merger of information service and social operation systems. At the same time this integrated innovation will deepen in three directions – the applications of a new generation of information technology to rapidly form new growth momentum, the collaboration of industry, academia, research and application to foster a new innovation paradigm, and the integration of digital and real economy to open up new development opportunities.
China Mobile sees valuable opportunities as they expand our information services. With the advocacy of the national “AI+” initiative and the further accelerated advancement of Digital China, the industry experiences new growth potential from the development of new quality productive forces. This progress brings forth the emergence of data as a new factor of production, computility as a new fundamental energy source and AI as a new instrument of production. The information services industry has not only in itself become an important sector for the development of new quality productive forces, but also a strong support for other sectors in this pursuit. General AI, particularly represented by AI large models, is developing robustly.
The role of AI is also fast changing from an assisting tool that helps different industries improve quality and efficiency, to an indispensable infrastructure and core capability that supports economic and social transformation and development. While AI brings forth disruptive applications, “AI+” opens up vast blue-ocean of opportunities. Fixating the vision of building a world-class information services and sci-tech innovation enterprise, we will capture opportunities arising from the development of “AI+” and extending our “5G+” initiatives towards 6 this direction. We will identify a new roadmap of transformation and upgrade through comprehensive, systematic and deep-dived integrated innovation. In doing so, we will drive more creation to enrich life, enhance quality production and support precise governance powered by digital intelligence. We will satisfy, drive and create demand to form a new for value growth trajectory and fuel the future development of the Company.
References:
p240321.pdf (chinamobileltd.com)
https://www.rcrwireless.com/20240423/carriers/china-mobile-q1-revenues-up-5-year-on-year
China Mobile & ZTE use digital twin technology with 5G-Advanced on high-speed railway in China
China Mobile & China Unicom increase revenues and profits in 2023, but will slash CAPEX in 2024
China Mobile verifies optimized 5G algorithm based on universal quantum computer
China Mobile to deploy 400G QPSK by the end of 2023
Omdia: China Mobile tops 2023 digital strategy benchmark as telcos develop new services
WSJ: China’s Telecom Carriers to Phase Out Foreign Chips; Intel & AMD will lose out
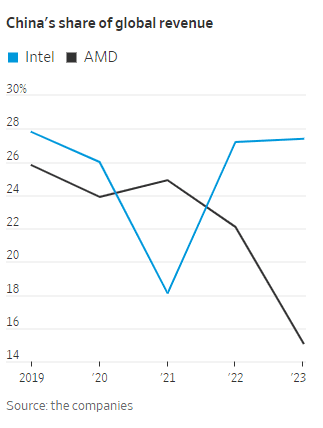
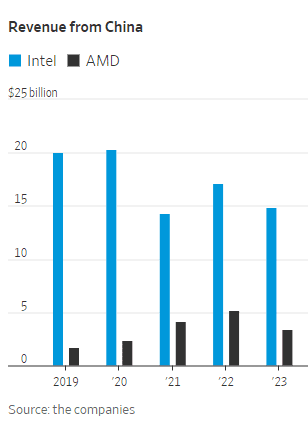
China’s largest telecom firms were ordered earlier this year to phase out foreign computer chips from their networks by 2027. That news confirms and expands on reports from recent months. It was reported in the Saturday print edition of the Wall Street Journal (WSJ). The move will hit U.S. semiconductor processor companies Intel and Advanced Micro Devices. Asia Financial reported in late March that these retaliatory bans would cost the U.S. chip firms billions.
The deadline given by China’s Ministry of Industry and Information Technology (MIIT) aims to accelerate efforts by Beijing to halt the use of such core chips in its telecom infrastructure. The regulator ordered state-owned mobile operators to inspect their networks for the prevalence of non-Chinese semiconductors and draft timelines to replace them, the people said.
In the past, efforts to get the industry to wean itself off foreign semiconductors have been hindered by the lack of good domestically made chips. Chinese telecom carriers’ procurements show they are switching more to domestic alternatives, a move made possible in part because local chips’ quality has improved and their performance has become more stable, the people said.
Such an effort will hit Intel and AMD the hardest, they said. The two chip makers have in recent years provided the bulk of the core processors used in networking equipment in China and the world.
China’s MIIT, which oversees the regulation of the wireless, broadcasting and communication industries, didn’t respond to WSJ’s request for comment. China Mobile and China Telecom , the nation’s two biggest telecom carriers by revenue, also didn’t respond.
In March 2023, the Financial Times reported China is seeking to forbid the use of Intel and AMD chips, as well as Microsoft’s operating system, from government computers and servers in favor of local hardware and software. The latest purchasing rules represent China’s most significant step yet to build up domestic substitutes for foreign technology and echo moves in the US as tensions increase between the two countries. Among the 18 approved processors were chips from Huawei and state-backed group Phytium. Both are on Washington’s export blacklist. Chinese processor makers are using a mixture of chip architectures including Intel’s x86, Arm and homegrown ones, while operating systems are derived from open-source Linux software.
Beijing’s desire to wean China off American chips where there are homemade alternatives is the latest installment of a U.S.-China technology war that is splintering the global landscape for network equipment, semiconductors and the internet. American lawmakers have banned Chinese telecom equipment over national-security concerns and have restricted U.S. chip companies including AMD and Nvidia from selling their high-end artificial-intelligence chips to China.
China has also published procurement guidelines discouraging government agencies and state-owned companies from purchasing laptops and desktop computers containing Intel and AMD chips. Requirements released in March give the Chinese entities eight options for central processing units, or CPUs, they can choose from. AMD and Intel were listed as the last two options, behind six homegrown CPUs.
Computers with the Chinese chips installed are preapproved for state buyers. Those powered by Intel and AMD chips require a security evaluation with a government agency, which hasn’t certified any foreign CPUs to date. Making chips for PCs is a significant source of sales for the two companies.
China Mobile and China Telecom are also key customers of both chip makers in China, buying thousands of servers for their data centers in the country’s mushrooming cloud-computing market. These servers are also critical to telecommunications equipment working with base stations and storing mobile subscribers’ data, often viewed as the “brains” of the network. Intel and AMD have the lion’s share of the overall global market for CPUs used in servers, according to data from industry researcher TrendForce. In 2024, Intel will likely hold 71% of the market, while AMD will have 23%, TrendForce estimates. The researcher doesn’t break out China data.
China’s localization policies could diminish Intel and AMD’s sales in the country, one of the most important markets for semiconductor firms. China is Intel’s largest market, accounting for 27% of the company’s revenue last year, Intel said in its latest annual report in January. The U.S. is its second-largest market. Its customers also include global electronics makers that manufacture in China.
In the report, Intel highlighted the geopolitical risk it faced from elevated U.S.-China tensions and China’s localization push. “We could face increased competition as a result of China’s programs to promote a domestic semiconductor industry and supply chains,” the report said.
References:
https://www.wsj.com/tech/china-telecom-intel-amd-chips-99ae99a9 (paywall)
https://www.ft.com/content/7bf0f79b-dea7-49fa-8253-f678d5acd64a
China Mobile & China Unicom increase revenues and profits in 2023, but will slash CAPEX in 2024
GSMA: China’s 5G market set to top 1 billion this year
MIIT: China’s Big 3 telcos add 24.82M 5G “package subscribers” in December 2023
China’s telecom industry business revenue at $218B or +6.9% YoY