T-Mobile US
Skeptical Analysis: SpaceX Selects Qualcomm for Nationwide Terrestrial 5G Network; Impact on Big 3 U.S. Wireless Carriers
Disclosure: ChatGPT was used extensively for research, technical analysis, and drafting assistance in this article. The author reviewed and fact-checked the material and is responsible for the final content.
Executive Summary:
SpaceX has selected Qualcomm Technologies’ Dragonwing Cellular Infrastructure platforms to provide the radio and baseband technology for Starlink Mobile’s planned nationwide U.S. terrestrial 5G network. The multi-year agreement calls for deployment across tens of thousands of macro cell sites, with initial rollout expected to begin in 2027. Qualcomm characterized the agreement as its largest 5G infrastructure deal to date. Financial terms were not disclosed. The agreement represents a major expansion of Qualcomm’s role in cellular infrastructure beyond its established position in mobile-device processors and modems. For SpaceX, it is an important step toward building a terrestrial mobile network that complements its Starlink satellite constellation and could eventually compete directly with AT&T, Verizon and T-Mobile.
Qualcomm’s announcement highlighted:
- Qualcomm Technologies is supplying its Dragonwing Cellular Infrastructure platforms to support Starlink Mobile’s planned nationwide U.S. terrestrial 5G network.
- Featuring Massive MIMO, power-efficient processing, and commercial-grade Layer 1 software, Dragonwing QRU100 and QDU100 platforms support Starlink’s nationwide network deployment.
- SpaceX plans for U.S. nationwide deployment rollout to begin in 2027, with tens of thousands of sites deployed over the multi-year agreement.

Unlike Starlink’s existing direct-to-device (D2D) satellite service, the new deployment involves conventional terrestrial cellular infrastructure, including base stations, radio units and distributed-unit processing. The planned network will use Qualcomm’s Dragonwing QRU100 and QDU100 platforms, together with commercial-grade Physical Layer software.
“Building a nationwide network demands high performance and power efficiency at every site. Dragonwing Cellular Infrastructure platforms bring together advanced Massive MIMO, purpose-built processing and commercial-grade Physical Layer software to help Starlink deliver an exceptional nationwide network,” said Durga Malladi, EVP & GM, Technology Planning, Edge Solutions, and Data Center, Qualcomm Technologies, Inc. “Together with SpaceX, we are building world-leading cellular infrastructure in the United States, advancing 5G today, with an opportunity to lay the foundation for AI-native 6G in the years ahead.”
“We shouldn’t live in a time where phone calls are still dropping whether you’re at home or on-the-go. Starlink is building the first fully-integrated nationwide satellite and terrestrial network that will keep people connected no matter where they are. We’re excited to collaborate with Qualcomm Technologies and leverage their industry expertise and platform to accelerate our timeline to develop our base station end-to-end architecture,” said Michael Nicolls, Senior Vice President of Starlink.
…………………………………………………………………………………………………………………………………………………………………………………………
Technical Architecture of Qualcomm Dragonwing:
The SpaceX-Qualcomm agreement covers two principal building blocks of the 5G Radio Access Network (RAN):
1. Dragonwing QRU100 – Radio Unit Processing
The QRU100 platform provides highly integrated processing for Massive MIMO radio units. SpaceX plans to deploy 64T64R (64 transmit and 64 receive paths) Massive MIMO configurations.
Massive MIMO uses multiple antenna elements to transmit and receive multiple spatial streams. Combined with beamforming, it can direct radio energy toward individual users or groups of users rather than distributing it uniformly across a cell sector.
This approach can improve spectral efficiency, increase sector capacity and enhance coverage, particularly in environments with substantial user density and interference.
The 64T64R configuration is a significant capability for a nationwide macro-cell deployment. However, actual performance will depend on spectrum bandwidth, propagation conditions, antenna configuration, interference management and network loading.
2. Dragonwing QDU100 – Distributed Unit Processing
The QDU100 provides high-performance processing for latency-sensitive Layer 1 (L1) baseband functions.
In a 5G RAN, the distributed unit (DU) handles time-sensitive baseband processing and communicates with the radio unit (RU). This processing includes important physical-layer functions required for transmitting and receiving cellular signals. Qualcomm is supplying both the radio-unit and distributed-unit building blocks, along with commercial-grade Physical Layer software. This gives SpaceX an integrated radio and baseband technology foundation for its planned terrestrial network.
However, Qualcomm is a relatively new entrant in the macro-cell RAN equipment market, and its Dragonwing platforms do not yet have the extensive commercial deployment history of established suppliers such as Ericsson, Nokia and Samsung. Although Qualcomm has secured some early commercial deployments, these do not establish that its QRU100 and QDU100 platforms can deliver the reliability, performance, interoperability and power efficiency required across a nationwide network involving tens of thousands of sites. The SpaceX agreement therefore represents both a major opportunity for Qualcomm and a substantial test of its ability to compete in the cellular infrastructure market.
Power Efficiency and Network Economics:
Power consumption is an important consideration when deploying tens of thousands of macro cell sites. Massive MIMO radios and baseband processing can require substantial electrical power, particularly when operating at high capacity. Qualcomm says its Dragonwing platforms are designed to improve performance per watt across radio and distributed-unit processing.
If these efficiency improvements are achieved in commercial deployments, they could reduce operating expenses and improve the economics of building and operating a nationwide network.
Qualcomm also describes the architecture as flexible and evolvable, supporting a multiband network deployed in multiple rollout phases.
However, the companies have not disclosed all the technical details needed to evaluate the complete RAN implementation, including specific operating bands, fronthaul interfaces, functional splits and interoperability arrangements.
Terrestrial 5G and Satellite Connectivity: An Integrated Network Strategy:
SpaceX’s longer-term objective is to combine terrestrial cellular infrastructure with its satellite constellation to provide more comprehensive mobile coverage.
Terrestrial 5G macro cells will provide the primary capacity layer in populated areas, where conventional cellular infrastructure can support higher traffic volumes and more consistent indoor connectivity.
Starlink satellites can complement terrestrial coverage in remote locations, rural areas and places where deploying conventional cell sites is economically difficult.
This hybrid architecture could offer advantages over relying exclusively on either terrestrial cellular networks or satellite-to-device connectivity.
However, the November 4 Qualcomm agreement is specifically focused on the terrestrial 5G portion of Starlink Mobile. It should not be confused with an announcement about a new satellite radio interface or a completed satellite-to-terrestrial interoperability solution.
The immediate technical challenge is building a high-capacity terrestrial RAN that can use SpaceX’s spectrum resources efficiently while integrating with its broader satellite connectivity strategy.
…………………………………………………………………………………………………………………………………………………………………………………………
Implications for the Three Major U.S. Wireless Carriers:
The Qualcomm agreement advances SpaceX’s ambition to become a facilities-based wireless network operator rather than remaining primarily a satellite connectivity provider or wholesale partner.
That creates a potential new competitive threat to AT&T, Verizon and T-Mobile. Nevertheless, the threat should be viewed as a multiyear development rather than an immediate challenge to their existing nationwide networks.
The three established carriers have extensive spectrum holdings, tower infrastructure, fiber backhaul, established retail distribution, enterprise relationships and millions of existing subscribers. Replicating those capabilities will require substantial investment and years of execution.
1. AT&T
AT&T could face additional competition in consumer wireless, particularly if Starlink Mobile eventually offers competitive nationwide coverage and bundles satellite broadband with terrestrial mobile service. AT&T has invested heavily in its 5G network and fiber infrastructure. Its established customer base, extensive fiber footprint and enterprise relationships provide competitive advantages that SpaceX will not quickly replicate. The more important longer-term question is whether SpaceX can offer an attractive combination of terrestrial 5G capacity and satellite coverage at a price that encourages AT&T subscribers to switch.
2. Verizon
Verizon faces a similar potential competitive challenge, particularly in premium wireless services and enterprise connectivity. Verizon has invested substantially in C-band 5G and Massive MIMO technology to increase network capacity and improve performance. SpaceX’s planned 64T64R architecture demonstrates that it intends to compete using sophisticated terrestrial RAN technology rather than relying exclusively on satellite coverage. Verizon’s existing network scale, spectrum resources and enterprise customer relationships are significant competitive advantages. Nevertheless, a well-funded new entrant could increase pricing pressure and force additional investment in capacity, coverage and customer retention.
3. T-Mobile
T-Mobile faces a particularly interesting situation because it already has a Starlink partnership for satellite-to-mobile connectivity. That relationship provides T-Mobile customers with satellite connectivity in areas where conventional cellular coverage is unavailable. However, SpaceX’s planned terrestrial network introduces a potential conflict: today’s satellite connectivity partner could become tomorrow’s direct wireless competitor. T-Mobile has extensive 5G spectrum resources and a substantial competitive advantage from its existing nationwide network. It also has experience integrating satellite connectivity into its mobile service offerings. The strategic question is whether T-Mobile can preserve the benefits of its Starlink relationship while competing against SpaceX’s expanding terrestrial infrastructure business.
…………………………………………………………………………………………………………………………………………………………………………………………
Qualcomm’s Expanding Role in Cellular Infrastructure:
The agreement is also significant for Qualcomm’s position in the telecommunications equipment supply chain. Qualcomm is best known for its Snapdragon mobile processors and cellular modem technology. Its Dragonwing Cellular Infrastructure platforms represent an expansion into the radio and baseband processing equipment used in cellular networks.
Qualcomm said the equipment would provide a flexible foundation for a multi-band network, which can be deployed in stages. The initial rollout will focus on terrestrial 5G, with the architecture designed to accommodate developments in connectivity and network intelligence.
The SpaceX agreement gives Qualcomm a major opportunity to establish its infrastructure technology in a large-scale U.S. network deployment. It also places Qualcomm in a more prominent competitive position alongside established cellular infrastructure technology suppliers.
The commercial success of this effort will depend on more than winning a major customer. Qualcomm must demonstrate that its radio and baseband platforms can meet carrier-grade requirements for performance, reliability, interoperability and power efficiency at scale.
A Potential New Competitor in U.S. Wireless Infrastructure?
SpaceX’s selection of Qualcomm Dragonwing for its planned nationwide terrestrial 5G network is more consequential than another satellite-to-phone announcement. It demonstrates that SpaceX intends to build substantial terrestrial cellular infrastructure using advanced Massive MIMO radio technology and dedicated baseband processing.
The planned deployment of tens of thousands of sites, beginning in 2027, represents a significant undertaking. However, a deployment announcement does not establish that nationwide coverage, competitive network performance or attractive operating economics have been achieved.
For AT&T, Verizon and T-Mobile, the immediate competitive threat remains limited because SpaceX’s terrestrial network buildout has not yet been demonstrated and its financing and execution remain uncertain (more in the section below). Their established infrastructure, spectrum portfolios, customer relationships and operating experience will be difficult to replicate.
Nevertheless, SpaceX has substantial existing assets, satellite infrastructure and spectrum resources that could support its entry into the wireless market. Whether it can finance and execute a nationwide terrestrial network while meeting its other major capital commitments remains an open question. See next section for more about the financing risks SpaceX faces.
The ultimate competitive test will not be the number of cell sites deployed or the sophistication of the Massive MIMO radios. It will be whether Starlink Mobile can deliver reliable nationwide coverage, competitive capacity and service quality at an economically sustainable cost. That remains to be demonstrated.
Capital Requirements and Financing Risks:
Building a nationwide terrestrial 5G network across tens of thousands of macro cell sites will require many billions of dollars in capital expenditures, in addition to spectrum acquisition, fiber backhaul, network integration and ongoing operating costs. SpaceX already faces enormous competing capital demands from its xAI initiatives, particularly the construction of AI data centers and computing infrastructure.
Separately, the broader AI infrastructure buildout has increasingly involved substantial borrowing and complex financing arrangements among AI infrastructure providers, cloud and service companies, and equipment suppliers. Many of these arrangements involve circular or mutually dependent commitments that raise questions about the ultimate sources of funding, underlying demand and the sustainability of the associated debt.
This creates a more fundamental concern for SpaceX’s terrestrial 5G ambitions: where will the capital come from to finance another massive infrastructure buildout? Relying on additional debt would increase leverage and financial risk, while equity financing could dilute existing shareholders. Funding construction from Starlink’s operating cash flow would require that business to generate sufficient free cash flow after its own substantial capital requirements. Infrastructure partnerships and vendor financing might defer some upfront expenditures but would not eliminate the underlying economic costs.
Until SpaceX discloses a credible, adequately funded deployment plan, its ability to finance a greenfield nationwide cellular network alongside its enormous AI infrastructure commitments remains a major unanswered question. The Qualcomm agreement establishes a technology supplier relationship; it does not establish that SpaceX has secured the financing necessary to build the network.
Conclusions:
While the agreement is impressive, two overarching concerns remain:
1. Qualcomm’s limited track record in commercial RAN deployments, particularly for the QRU100/QDU100 combination.
2. SpaceX’s ability to finance the proposed network while meeting its other major capital commitments.
–>Until these two questions are answered, the agreement represents a significant technology and business commitment—not proof that the proposed nationwide network can be successfully built and operated.
………………………………………………………………………………………………………………………………………………………………………………………………………………………………….
References:
https://www.sec.gov/Archives/edgar/data/1181412/000162828026066880/spcx-20260930.htm
https://www.t-mobile.com/news/un-carrier/reaching-for-the-stars-with-t-satellite
SpaceX Moves to Acquire Nationwide 800 MHz Spectrum for Starlink Mobile D2D Service
Analysis & Opinion: SpaceX to build, lease or buy a hybrid/terrestrial satellite network?
FT: SpaceX considering Starlink Direct-to-Consumer mobile service & terrestrial cellular network infrastructure in the U.S.
Analysis: SpaceX FCC filing to launch up to 1M LEO satellites for solar powered AI data centers in space
T-Mobile’s Strategy of Deploying Multi-Vendor AI-RAN on “Kinetic Edge” using AWS Pillars
Introduction:
During its Q3 2026 earnings call, T-Mobile US announced a definitive step away from traditional, single-purpose radio access networks (RANs) by detailing the real-world deployment of its “Kinetic Edge” [1.] architecture which operates on AWS infrastructure. By combining a multi-vendor AI-RAN footprint with a deeply distributed cloud orchestration layer in partnership with AWS, the U.S. network operator is attempting a fundamental structural shift: transforming cell towers into shared platforms capable of running concurrent cellular routing and third-party AI compute workloads.
Note 1. The T-Mobile Kinetic Edge architecture (announced in late October 2026 in partnership with AWS) is a distributed intelligence infrastructure designed to support Physical AI at production scale. It eliminates the need for expensive onboard computing on machines (like humanoid robots or delivery drones) by moving sub-millisecond AI inference workloads directly to the network edge. The underlying infrastructure layout, session parameters, and technical architecture of this deployment were discussed at the AWS re:Invent 2026 Event Catalog (Session IND384).That session outlined how T-Mobile operates its physical AI infrastructure at production scale for its 130M+ subscriber base using three integrated AWS pillars:
- AWS Outposts (The Hardware Plane): Deployed directly within T-Mobile’s localized edge sites and central offices to provide a fully managed, low-latency hybrid hardware footprint. Outposts host the compute layer, keeping the execution of physical AI inference nodes inches away from the 5G user plane function (UPF) to maintain sub-millisecond execution loops.
- Amazon SageMaker (The Model Pipeline): Handles the training, optimization, and continuous refinement of the complex spatial telemetry, real-world vision, and physical reasoning models. It allows T-Mobile to continuously push optimized model variations out to edge containers.
- Amazon Bedrock AgentCore (The Orchestration Engine): Serves as the backbone platform to host, scale, and secure autonomous, long-running agentic workloads. It decouples the agent logic from the backend plumbing, utilizing serverless microVM environments for strict session isolation per workload.
- AgentCore Identity & Policy: Enforces rigid, real-world permissions for unattended physical fleets via Cedar policies, ensuring autonomous edge actions remain safely sandboxed.
- AgentCore Gateway & Memory: Exposes internal APIs as unified Model Context Protocol (MCP) tool endpoints, while retaining stateful context across active device sessions.
Architectural Topology Breakdown:
| Layer | Technology | Primary Function |
|---|---|---|
| Physical AI Edge Device | Humanoid Robots, Vision Cameras, Fleet Sensors | Gathers real-time sensory inputs, handles localized movement commands, offloads processing. |
| Deterministic Wireless Fabric | T-Mobile 5G-Advanced Network & AI-RAN | Provides steady, low-latency uplink/downlink to transfer raw sensor streams and return telemetry. |
| Local Compute Node | AWS Outposts | Processes sub-millisecond inferencing and local data breakouts away from the distant central cloud. |
| Distributed AI Infrastructure | Amazon SageMaker & Bedrock AgentCore | Handles localized vision, reasoning, and machine learning models dynamically. |
CEO Srini Gopalan framed this structural shift as a transition away from standard, legacy telecom metrics to running distributed token-based intelligence. He stated, “Our future value is no longer bound to basic SIM cards or standard data buckets. We are engineering a platform to run distributed, token-based intelligence for millions of humanoid robots, drones, and autonomous systems by 2035.”
T-Mobile’s new network architecture serves as an ambitious architectural goal—and raises critical engineering questions—regarding how operators hope to eventually balance deterministic radio schedules with dynamic enterprise inference at the network edge.
The Baseband Convergence: Multi-Vendor AI-RAN at the Cell Site:
The foundational layer of the Kinetic Edge is T-Mobile’s verified execution of a commercial AI-RAN connection in Bellevue, Washington, which integrates Nvidia’s accelerated computing platform with Nokia’s 5G Standalone (SA) macro base stations. In traditional architectures, the Distributed Unit (DU) relies on highly specialized, fixed-function ASICs to execute Layer 1 (Physical Layer or PHY) digital signal processing. Under the AI-RAN framework, these workloads are shifted onto software-defined, GPU-accelerated hardware profiles. This allows the physical cell site footprint to execute two distinct tasks simultaneously:
-
- Inline Layer 1 Acceleration: Executing high-density 5G-Advanced signal processing—such as massive MIMO beamforming calculation and low-density parity-check (LDPC) decoding—directly within a programmable software stack.
- Opportunistic AI Inference: Utilizing unallocated or transiently idle compute cycles on the exact same silicon to host localized machine learning models, edge vision analytics, and autonomous system telemetry.
Ankur Kapoor, EVP & Chief Network Officer, explained the software philosophy behind this infrastructure trial. “We cannot rely entirely on rigid, single-purpose ASICs if we want an agile network layer,” Kapoor noted. “Our engineering team is actively steering a hybrid model, developing software layers optimized for both specialized merchant silicon and accelerated GPU stacks, allowing us to pivot compute resources on demand.” The immediate engineering challenge remains operational isolation. Unlike standard data center servers where a few milliseconds of compute jitter goes unnoticed, cellular networks operate under strict microsecond-level hybrid automatic repeat request (HARQ) deadlines. T-Mobile’s deployment must prove that heavy enterprise AI inference spikes cannot bleed into the compute budget reserved for timing-critical radio resource management.
Distributed Cloud Orchestration: The AWS “Kinetic Edge” Fabric:
To push deterministic connectivity out to the local cell edge, T-Mobile is wrapping its physical AI-RAN nodes in a distributed cloud framework managed via AWS. This architecture essentially stretches the AWS cloud control plane down to the operator’s regional hubs and central office cell aggregation sites.
       [ AWS Core Cloud Control Plane ]
                     │
                     ▼
       [ T-Mobile Regional Edge Hubs ]
   (Centralized Control & Heavy Orchestration)
                     │
                     ▼
       [ Localized Cell Site Node ]
 ┌───────────────────────────────────────────┐
 │  Co-located AI-RAN Compute Infrastructure │
 ├─────────────────────┬─────────────────────┤
 │   Deterministic     │    Opportunistic    │
 │  5G Layer 1/2 Stack │ Enterprise AI Stack │
 └─────────────────────┴─────────────────────┘
CTO Dr. John Saw detailed the core mechanics of this distributed offload strategy in a technical brief accompanying the announcement. “To unlock true physical AI, we must eliminate core network transport latency,” Dr. Saw stated. “The Kinetic Edge is designed to offload heavy vision, spatial telemetry, and real-world reasoning AI models onto distributed cell-site nodes, putting the execution engine inches away from the user plane function (UPF).”
Saw expects cellular traffic patterns in 2030 to be different from today as AI usage increases. Saw said his mobile traffic assumption for 2030 is “still downlink heavy but increasingly uplink rich,” driven by AI wearables, AI agents and “explosive growth by then of physical AI devices, like humanoids, robots, delivery drones, vehicles and factory machines.” Check out Saw’s Physical AI blog here.
Chris Sambar, Chief Enterprise Officer, emphasized how this framework underpins T-Mobile’s enterprise monetization strategy. “Our B2B priority is monetizing the physical edge,” Sambar stated. “By exposing this low-latency AWS fabric to enterprise clients, we can guarantee deterministic, localized compute slots for industrial computer vision and robotics coordination directly on our infrastructure.”
The control plane must intelligently manage this distribution. Heavy macro-orchestration and model training remain centralized within regional edge hubs, while light, highly optimized model weights are pushed to individual edge nodes based on localized user density and enterprise demand.
Intelligent Radio Resource Management (RRM) Overlays:
Beyond hosting third-party workloads, the integration of AI directly into the RAN stack redefines internal network management. T-Mobile’s architecture leverages supervised machine learning models to build automated, predictive Radio Resource Management (RRM) overlays.
Traditional RRM relies on reactive, hard-coded algorithms to handle handovers, power allocation, and frequency scheduling based on past channel quality indicators (CQI). Ankur Kapoor highlighted how AI shifts this paradigm: “Our current live trials utilize AI-managed beamforming and predictive radio resource scheduling directly across subframes. The network no longer just reacts to interference; it models local spatial telemetry to preemptively mitigate link degradation before it impacts the terminal device”.
- Spatial Telemetry Ingestion: The AI-RAN layer continuously ingests massive streams of real-world spatial data and device behavior patterns across the sector.
- Predictive Beamforming Adjustment: Instead of waiting for a signal link to degrade, the predictive models anticipate localized network congestion, building clutter interference, or sudden user clustering.
- Dynamic Resource Re-allocation: The radio subframe allocation and multi-antenna beam vectors are adjusted dynamically ahead of time, maximizing spectral efficiency and keeping physical resource blocks (PRBs) optimally distributed.
The Interoperability and 6G Transition Horizon:
T-Mobile’s Q3 2026 milestones offer a compelling look at the future of network monetization, but the architecture’s long-term viability hinges on open standards. While this deployment successfully pairs Nokia and Nvidia architectures on a 5G Standalone core, the telecom industry must demand independently reproducible multi-vendor interoperability.
Dr. John Saw explicitly tied these architectural steps to the operator’s long-term 6G strategy, setting an aggressive timeline. “T-Mobile is anchoring a firm 2030 commercial deployment timeline for the nation’s first 6G network,” Dr. Saw declared. “6G will natively expand on this Kinetic Edge foundation, shifting from traditional cell communication to a ‘radar-behaving’ topology that pairs Integrated Sensing and Communication (ISAC) with uplink-dense architectures.” The upcoming FCC spectrum auctions for upper C-band and 2.7GHz offer T-Mobile opportunity to add capacity for 6G as well as to boost uplink bandwidth, Saw added.
As 3GPP Release 20 and Release 21 move through their respective study and normative spec cycles towards 2027–2029, these real-world deployment lessons must be codified. Ensuring that shared-compute RAN platforms are open and interchangeable across competing hardware and software vendors will determine whether architectures like the Kinetic Edge become the universal foundation for 6G, or remain isolated, proprietary engineering triumphs.
References:
https://finance.yahoo.com/quote/TMUS/earnings/TMUS-Q3-2026-earnings_call-713930.html
https://www.t-mobile.com/news/network/physical-ai-is-leaving-the-lab
https://aws.amazon.com/blogs/industries/your-guide-to-aws-for-telecom-at-reinvent-2026/
https://aws.amazon.com/blogs/architecture/lets-architect-architecting-for-the-edge/
https://www.lightreading.com/6g/t-mobile-we-ll-be-first-with-6g-and-no-to-spacex-mvno
T-Mobile US announces new broadband wireless and fiber targets, 5G-A with agentic AI and live voice call translation
AWS to deploy AI inference chips from Cerebras in its data centers; Anapurna Labs/Amazon in-house AI silicon products
AT&T and AWS to deliver last mile connectivity for AI workloads; AT&T Geo Modeler™ AI simulation tool
Evaluating T-Mobile’s SuperBroadband – Has it Been a Commercial Success?
Disclaimer: Perplexity.ai & Google Gemini were used to research and help write this article.
……………………………………………………………………………………………………………..
Introduction:
What the evidence establishes:
| Commercial indicator | Public evidence | Assessment |
|---|---|---|
| Named customers | Launch coverage identified Aramark Destinations and Columbia Sportswear as customers. | Evidence of initial adoption, but not of deployment scale. |
| Continued customer engagement | October reporting identified Aramark Destinations and Aramark Nexus as customers and discussed their connectivity requirements. | More substantial than launch-day promotion alone, but without quantified contract value or installed-site counts. |
| Customer, site and revenue growth | The public materials reviewed do not establish a SuperBroadband-specific customer total, activated-site total, revenue figure or growth rate. | Insufficient evidence to judge commercial scale. |
| Profitability and retention | Those materials provide no product-specific margins, acquisition costs, renewal rates or churn figures. | Insufficient evidence to judge sustainable commercial success. |

+-----------------------------------------------------------------------+

|                       Distributed Enterprise Site                     |
|                                                                       |
|   +-----------------------+               +-----------------------+   |
|   |  T-Mobile FWA Node    |               |  Starlink LEO Dish    |   |
|   | (Primary Terrestrial) |               |  (Space-Based Backup) |   |
|   +-----------+-----------+               +-----------+-----------+   |
|               |                                       |               |
|               +-------------------+-------------------+               |
|                                   |                                   |
|                                   v                                   |
|                     +---------------------------+                     |
|                     | Ericsson Cradlepoint Edge |                     |
|                     | Router & Outdoor Adapters |                     |
|                     +-------------+-------------+                     |
|                                   |                                   |
|                                   v                                   |
|                     +---------------------------+                     |
|                     |   NetCloud Manager (LAN)  |                     |
|                     +---------------------------+                     |
+-----------------------------------------------------------------------+
- Edge Router Infrastructure:Ericsson serves as the lead infrastructure vendor, deploying enterprise-grade Cradlepoint routers and outdoor adapters. T-Mobile has also integrated Inseego and Cisco hardware platforms to scale deployment configuration choices.
- Satellite Endpoint: Every deployment includes a business-performance Starlink Phased-Array Satellite Kit professionally mounted and calibrated on-site.
- Management Engine: The dual connections terminate directly into the local router, which is monitored and managed via Ericsson Enterprise Wireless Solutions’ NetCloud Manager software platform.
- Traffic Flow Configurations: NetCloud software handles active traffic steering via two primary configurations based on enterprise requirements:
- Failover Mode: The local router treats the 5G Advanced FWA link as the primary data conduit. If the local router detects cell degradation, packet loss, or a link-down event, it reactively transfers active LAN traffic to the Starlink satellite leg.
- Load Balancing: Data streams are distributed across both the cellular and satellite paths simultaneously to manage peak bandwidth constraints and prioritize specific enterprise applications.
- Turnkey Deployment: T-Mobile manages the entire lifecycle, including custom site solution engineering, professional hardware mounting/cabling handled via field service partner Acuative, and automated provisioning.
- Centralized Visibility: Enterprise IT administrators retain full monitoring capabilities across all distributed endpoints using T-Mobile’s consolidated cloud dashboard, the T-Platform portal.
- The 99.99% Uptime Guarantee: SuperBroadband represents T-Mobile’s first wireless-first broadband tier backed by a contractually binding 99.99% uptime Service Level Agreement (SLA). If local link availability drops below this threshold, enterprise accounts receive an automated financial credit equivalent to 20% of the base monthly service cost.
- Commercial Tiers: Standard enterprise pricing structures start at $250 per month per site tied to a 36-month commitment. This base commercial fee includes unlimited primary 5G business data, standard Starlink backup data, all bundled router/satellite hardware kits, and ongoing 24/7 technical operations center monitoring.
Conclusions:
T-Mobile’s SuperBroadband has secured recognizable enterprise customers, but publicly available evidence does not yet establish meaningful deployment scale, revenue contribution or profitability. It is an early commercial foothold—not yet a demonstrated commercial success.
Deutsche Telekom: Device-to-Cloud AI Traffic Won’t Force RAN Upgrades or Increase CAPEX
Introduction:
Deutsche Telekom is in the process of “upgrading mid-range plans,” according to Dhananjay Mirchandani, DT’s senior VP for group controlling and the group’s next CFO from May 1, 2027. “I cannot recall a single conversation in which Alex Jenbar [CTO of Telekom Deutschland] … or somebody else approached us and said, ‘in addition to whatever we currently have on our roadmaps for RAN modernization, that there is an incremental requirement for an investment to be able to prepare ourselves for additional uplink/AI-related traffic,'” he said. “[That’s] just to give you a sense of the degree of confidence we have in terms of our own capex planning, specifically related to mobile network capacity,” he added.
His assessment on medium-term mobile capacity is bound to be sobering for its radio access network (RAN) vendors in Germany: Ericsson, Huawei and Nokia.
The rise of agentic and physical AI could upend decades of mobile network design that dedicates most bandwidth to download speeds (i.e., downlink) and much less to the data channels for uploads (i.e., uplink). It’s not certain how or when traffic patterns will change in a big way, but telcos are talking about preparing for a wave of AI-fueled traffic coming from smartphones, smart glasses or robots.
The Reality Check – No Incremental RAN Capex:
During an investor event, financial analysts directly pressed Deutsche Telekom’s incoming CFO, Srinivas Mirchandani, on whether capital intensity would escalate after 2027 to handle the upstream traffic generated by physical AI, wearables, and smartphone-based LLM queries.
• The Stand: Mirchandani honestly noted that he could not recall a single internal conversation where the CTO of Telekom Deutschland (Alex Jenbar) requested incremental investment beyond their existing radio access network (RAN) modernization roadmaps to handle AI uplink traffic.
• The Baseline Numbers: DT’s long-term guidance (established at its 2024 Capital Markets Day) mandates that capital spending outside the U.S. and spectrum will sit at 21% of service revenue by 2027. While DT is trading slightly above that now, it is entirely due to heavy fiber-optic rollouts in Germany, not mobile radio expansions.
| Attribute | Deutsche Telekom (Europe Group) | T-Mobile US |
|---|---|---|
| Capex Stance | Rigid cap on mobile intensity; excess savings diverted strictly to German landline fiber infrastructure. | Confirmed network architecture expansion funded via standardized 5G-Advanced cycles. |
| AI Traffic Philosophy | Believes traffic peaks are manageable within existing, scheduled modernization roadmaps. | Views the network explicitly as the “connective tissue for physical AI and AI wearables.” |
| Uplink Solutions | Delaying heavy structural changes; emphasizing spectrum efficiency under legacy boundaries. | Implementing Uplink Carrier Aggregation, Uplink MIMO, and Transmit Switching under 5G-Advanced. |
- Delaying Capex via Software: Panelists from across the telco ecosystem—including Turkcell and Deutsche Telekom’s own group partnering division—noted that AI is actually delaying capex cycles rather than accelerating them. Operators are deploying AI algorithms inside the radio access network to optimize power consumption, conduct predictive capacity planning, and boost edge throughput. In short: AI software is making existing hardware last longer.
- The Opex ROI Conundrum: Telcos are seeing immediate financial returns from “AI for the network” (e.g., DT projects €2.5 billion in cumulative cost savings by 2030 through AI automation). However, the business model for a “network for AI”—where consumers or enterprise clients pay a premium for high-speed, low-latency uplink to feed remote LLMs—remains entirely unproven.
- The 6G Boundary Wall: Based on this author’s carrier checks, most Tier-1 network operators now view massive, structural upstream re-architecting as a “6G-era investment narrative” rather than an immediate 5G sub-6GHz demand. Until dedicated enterprise use cases validate moving further up the value chain, hardware vendors will have to wait for a significant revenue lift from device-to-cloud AI traffic.

Source: Deutsche Telekom, Photo: Norbert Ittermann
…………………………………………………………………………………………………………….
Conclusions:
Deutsche Telekom (DT) indicates that rising device-to-cloud traffic volumes will not necessitate premature radio access network (RAN) upgrades. Technical analyses suggest that upcoming capacity demands driven by agentic AI may not immediately accelerate RAN capital expenditure.
DT does not see AI uplink traffic driving an incremental increase to its RAN capex plans in the medium term. DT is holding a rigid perimeter around its long-term financial guidance. By 2027, capital intensity (excluding the U.S. and spectrum) is strictly capped at 21% of service revenues. Excess capital is not being funneled into expanding cell site capacities for upstream AI traffic; it is being aggressively diverted toward landline fiber-optic buildouts in Germany.
-
- Uplink Carrier Aggregation (CA): Allows the network to combine multiple frequency bands (e.g., mid-band and low-band) exclusively for the upstream path. This maximizes the utilization of already-deployed spectrum without requiring operators to acquire or build new macro tower infrastructure.
- Uplink MIMO & Transmit Switching: Enhances data throughput from consumer AI wearables and smartphones back to the cloud by multiplying the data paths between the device and the tower antenna arrays. [
- Network Slicing: Under 5G SA, carriers can allocate a virtualized, highly efficient “slice” of the existing spectrum explicitly for low-latency AI queries. Slicing can improve resource allocation and protect selected service requirements, but it is not a substitute for sufficient uplink capacity. However, it isolates upstream data paths without needing incremental physical hardware upgrades.
References:
https://www.openranforum.com/home
AI-RAN and Agentic AI get real: Ericsson, Nokia, Verizon & other operators enter into a new network automation era
Cisco Execs: New “Network Supercycle” as Agentic AI Workloads Reshape Telecom Infrastructure
Cisco report: Agentic AI to reshape WAN traffic, AI inference will be ~25% of total traffic by 2035
Nokia’s AI Applications Study: “Physical AI” may require RAN redesign to support high‑volume, low‑latency uplink traffic
STL Partners webinar: Agentic AI needed for RAN autonomy & efficiency
The Financial Trap of Autonomous Networks: Scaling Agentic AI in the Telecom Core
AT&T’s 600 MHz Deployment with Ericsson: Turning Low-Band Spectrum Into Coverage and Uplink Capacity
SoftBank’s Transformer AI model boosts 5G AI-RAN uplink throughput by 30%, compared to a baseline model without AI
T‑Mobile achieves record 5G Uplink speed with 5G NR Dual Connectivity
Telstra achieves 340 Mbps uplink over 5G SA; Deploys dynamic network slicing from Ericsson
Finland’s Elisa, Ericsson and Qualcomm test uplink carrier aggregation on 5G SA network
Analysis and Implications of Deutsche Telekom’s potential full acquisition of T-Mobile
Deutsche Telekom is Europe’s largest telecommunications carrier with 273 million mobile customers in 50 countries. The German telco is reportedly considering a move to take full ownership of T-Mobile US by raising its stake from roughly 54% to 100%, thereby converting the publicly traded U.S. carrier into a wholly owned subsidiary. This potential merger/acquisition would represent a significant strategic and corporate restructuring within the global telecommunications landscape and would mark the consolidation of one of the largest wireless operators under a single parent entity.
During his 12-year tenure as Deutsche Telekom’s CEO Tim Höttges has helped turn T-Mobile from a money-losing underdog to the world’s most valuable telecom brand by market capitalization. Höttges has invested billions in T-Mobile’s U.S. infrastructure to support its 5G fixed-wireless home-internet product. T-Mobile contributes nearly two-thirds of Deutsche Telekom’s revenue.
Analysts say T-Mobile is currently constrained on large deals: Its high leverage makes borrowing expensive, and it can’t issue stock without diluting its German parent’s stake. By combining Deutsche Telekom and T-Mobile into a single $300 billion behemoth, the company would likely be able to raise debt at a lower cost, among other benefits. T-Mobile has been buying fiber-internet operators in the U.S. to compete with AT&T and Verizon and offer bundled wireless and home internet to more customers.

Deutsche Telekom CEO Höttges addressing shareholders at the firm’s annual meeting in April. Oliver Berg/
From a corporate strategy perspective, full ownership would provide Deutsche Telekom with complete control over T-Mobile US’s capital allocation, operational priorities, and long-term network investment strategy. Currently, while Deutsche Telekom exercises effective control through its majority stake, a 100% acquisition would eliminate minority shareholders, simplify governance structures, and allow the parent company to internalize the full economic value generated by T-Mobile US’s operations. This could be particularly relevant as the U.S. market continues to drive substantial cash flow and growth relative to Deutsche Telekom’s European operations.
The transaction would also have implications for corporate structure and financial reporting. Full ownership would enable Deutsche Telekom to restructure T-Mobile US within its corporate hierarchy, potentially integrating it more closely with other group entities or aligning its financial reporting more directly with parent-company objectives. Such consolidation could improve transparency for investors and reduce the complexity associated with managing a majority-owned public subsidiary.
However, executing a deal of this magnitude would present substantial challenges. The transaction would likely require extensive regulatory review in both the United States and Europe, including scrutiny from the Federal Communications Commission, the Department of Justice, and European competition authorities. Valuation would be a critical consideration, given T-Mobile US’s market position as the second-largest wireless carrier in the United States and its ongoing investments in 5G infrastructure, network modernization, and enterprise services. Financing the acquisition would also require careful consideration of debt levels, capital structure, and the impact on Deutsche Telekom’s balance sheet.
From a market perspective, the potential merger could be viewed as a consolidation move that reflects the increasing importance of the U.S. wireless market in global telecommunications strategy. T-Mobile US has emerged as a competitive leader in recent years, with strong performance in 5G deployment, spectrum efficiency, and customer acquisition. Full ownership would enable Deutsche Telekom to align these strengths more closely with its broader global strategy, potentially accelerating technology transfer, network architecture harmonization, and cross-border service integration.
Höttges has also put billions into expanding the German network, where fiber-internet subscribers have nearly tripled since 2023. He champions a cause popular with European regulators: tech sovereignty, or reducing reliance on American and Chinese technology. In February Deutsche Telekom opened Germany’s first AI gigafactory, a massive data center. The gigafactory uses AI GPU chips from Nvidia, which is of course an American company, based in Santa Clara, CA.
The CEO plans to retire at the end of 2028 and wants the right successor to be found first, said people familiar with the matter. He said on the German “OMR” podcast that his successor will need a different skill set. Artificial intelligence (AI) is overhauling the workforce and automating next-generation networks, transforming the industry at an astonishing pace. “Back then, a sober numbers guy was the right choice,” he said. “Today, I believe we need a visionary who understands the future architecture of modern infrastructure.”
In summary, Deutsche Telekom’s reported interest in acquiring full ownership of T-Mobile US represents a significant strategic consideration that would consolidate corporate control, simplify governance, and potentially enhance the parent company’s ability to capture the full financial benefits of its U.S. operations. While the strategic rationale is compelling, the transaction would entail substantial regulatory, financing, and valuation complexities that would need to be carefully addressed before any definitive agreement could be reached.
…………………………………………………………………………………………………………………………………………………………………………………
References:
https://www.telekom.com/en/company/companyprofile/company-profile-625808
https://www.wsj.com/business/telecom/t-mobile-deutsche-telekom-merger-4fdc8eba
https://finance.yahoo.com/markets/stocks/articles/deutsche-telekom-wants-whole-t-143743459.html
https://www.telekom.com/en/company/companyprofile/company-profile-625808
Analysis: OpenAI and Deutsche Telekom launch multi-year AI collaboration
Deutsche Telekom: successful completion of the 6G-TakeOff project with “3D networks”
Deutsche Telekom selects Iridium for NB-IoT direct-to-device (D2D) connectivity
Deutsche Telekom and Google Cloud partner on “RAN Guardian” AI agent
Deutsche Telekom offers 5G mmWave for industrial customers in Germany on 5G SA network
Deutsche Telekom migrates IP-based voice telephony platform to the cloud
Deutsche Telekom Network Day: Fiber, Mobile Network, Open RAN and 5G SA Launch in 2024
SK Telecom and Deutsche Telekom to Jointly Develop Telco-specific Large Language Models (LLMs)
Deutsche Telekom with AWS and VMware demonstrate a global enterprise network for seamless connectivity across geographically distributed data centers
T-Mobile expands FTTH footprint via 50-50 JVs with Oak Hill Capital and Wren House
T-Mobile US announces new broadband wireless and fiber targets, 5G-A with agentic AI and live voice call translation
Highlights of 2025 Broadband Nation Expo: Comcast, T-Mobile keynotes + selected quotes
AT&T deploys nationwide 5G SA while Verizon lags and T-Mobile leads
T-Mobile’s new CEO Srini Gopalan faces fierce competition from AT&T, Verizon and MVNOs
T-Mobile’s growth trajectory increases: 5G FWA, Metronet acquisition and MVNO deals with Charter & Comcast
Evercore: T-Mobile’s fiber business to boost revenue and achieve 40% penetration rate after 2 years
WSJ: T-Mobile hacked by cyber-espionage group linked to Chinese Intelligence agency
T-Mobile posts impressive wireless growth stats in 2Q-2024; fiber optic network acquisition binge to complement its FWA business
Ookla: Starlink a viable competitor for hybrid 5G/NTN services due to network performance improvements and larger coverage area
SpaceX’s Starlink low-Earth orbit (LEO) satellite constellation providing high speed internet service is increasingly positioning itself as a scalable broadband access platform within the global telecom ecosystem. It now has growing relevance for both retail and enterprise connectivity use cases.
Network performance improvements (see below) have occurred alongside substantial subscriber growth. Starlink’s global user base expanded from approximately 4.6 million at the end of 2024 to over 10 million by early 2026, underscoring the LEO satellite platform’s ability to scale capacity while maintaining service quality.
This evolution is exemplified by T-Mobile’s “SuperBroadband” offering, which integrates 5G fixed wireless access (FWA) with Starlink satellite connectivity to deliver hybrid terrestrial–non-terrestrial network (NTN) solutions for business customers. The viability of such architectures is directly dependent on sustained improvements in satellite network throughput, latency, and service consistency.
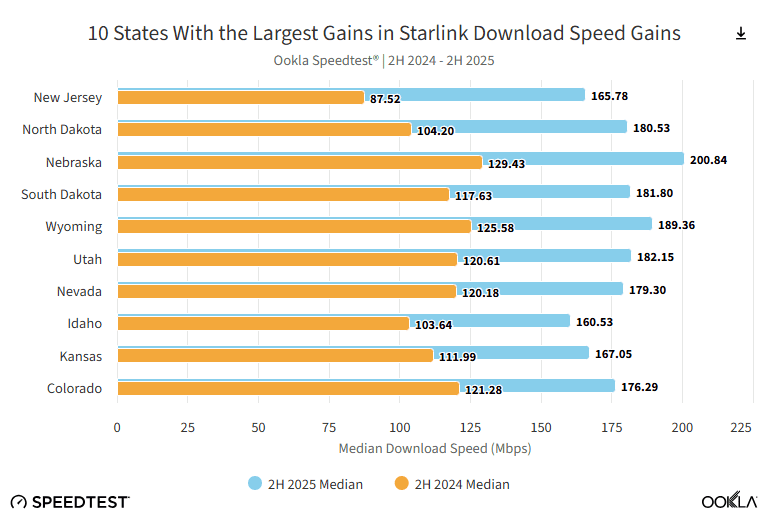
Ookla Speedtest® data for the second half of 2025 indicates significant year-over-year improvements in Starlink’s performance across key network metrics. Median download speeds exceeded 100 Mbps in 49 states, compared to 23 states in 2H 2024, reflecting both increased system capacity and improved spectral efficiency. Performance gains were also observed across the lower quartile of users: 25th percentile download speeds improved in 48 states, with the number of states below 50 Mbps declining from eleven to two (Alaska and Florida). This shift indicates not only higher peak throughput but also improved quality of experience (QoE) consistency across the subscriber base.
Latency performance has also trended positively, driven by both constellation densification and architectural enhancements. While Starlink continues to target ~20 ms median latency, the number of states with median multi-server latency below 40 ms increased from one to ten between 2H 2024 and 1H 2025. By 2H 2025, top-performing regions—including New Jersey, Colorado, Arizona, and Washington, D.C.—achieved median latencies of approximately 37 ms, approaching parity with certain terrestrial broadband deployments and enabling latency-sensitive applications.
There has been a rapid expansion of the Starlink constellation and ongoing satellite technology upgrades. As of February 2026, the constellation exceeded 10,000 satellites in orbit, materially increasing aggregate network capacity and reducing cell congestion through greater spatial reuse. The deployment of Generation 3 (V3) satellites—featuring an order-of-magnitude increase (~10×) in downlink capacity relative to prior generations—has further enhanced throughput. Concurrently, upgrades to inter-satellite laser links have enabled more efficient space-based routing, reducing dependency on terrestrial gateway infrastructure, minimizing bottlenecks, and improving end-to-end latency performance.
Notably, these network enhancements have coincided with rapid subscriber growth. Starlink’s global user base expanded from approximately 4.6 million at year-end 2024 to over 10 million by early 2026, demonstrating the platform’s ability to scale capacity in line with demand while maintaining or improving key performance indicators.
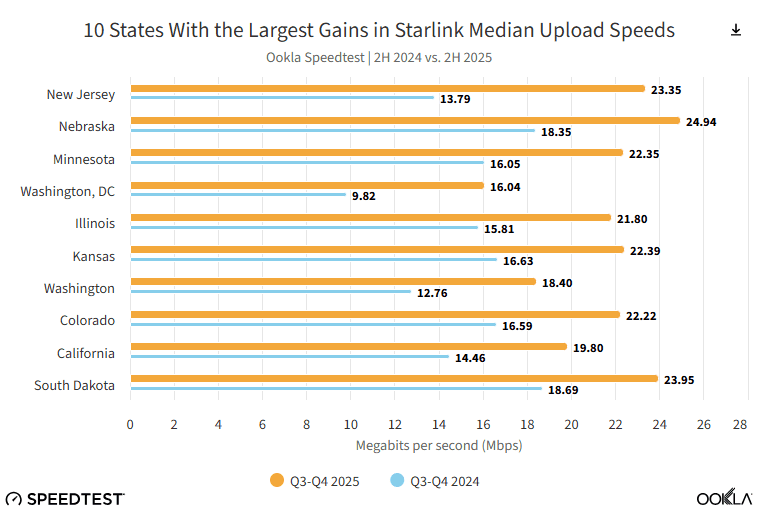
Uplink performance has also improved materially, with 22 states achieving median upload speeds ≥20 Mbps in 2H 2025, compared to zero states in the prior-year period. This threshold is aligned with the FCC’s current broadband definition, underscoring Starlink’s increasing capability to meet regulatory benchmarks for two-way broadband services. Nebraska, New Jersey, and Minnesota recorded the largest gains, with Nebraska leading overall at 24.94 Mbps median upload throughput.
However, performance gains remain uneven across certain geographies. States including Connecticut, Hawaii, and New Hampshire exhibited relatively modest uplink improvements, suggesting localized constraints related to capacity allocation, gateway distribution, or demand density. These variances highlight the continued importance of targeted constellation scaling and ground segment optimization to ensure uniform service quality.
In Q4, 44.7% of Starlink’s user base achieved the FCC’s 100/20 Mbps broadband benchmark, signaling the provider’s transition from a niche rural solution to a high-performance market disruptor. By scaling its LEO constellation to over 10,000 nodes and deploying higher-throughput payloads, Starlink has successfully optimized spectral efficiency and reduced latency, maintaining QoS even as its global subscriber base scaled to 10 million.
While the U.S. remains Starlink’s primary market, the competitive landscape is shifting. Amazon’s Project Kuiper faces significant deployment headwinds; despite an FCC mandate to orbit 1,618 satellites by July 2026, the company has only deployed roughly 240 units and has petitioned for a two-year extension due to launch capacity constraints. This market penetration places legacy GEO operators like Hughesnet and Viasat at a strategic disadvantage. Although these incumbents are leveraging aggressive pricing and CPE (Customer Premises Equipment) refreshes to stem churn, the inherent latency limitations of GEO architecture continue to pose a significant structural barrier to competing with LEO-based performance.
Overall, the data indicates that Starlink is transitioning from a niche rural broadband solution toward a more robust, high-capacity access network capable of supporting hybrid 5G/NTN architectures and enterprise-grade connectivity services.
…………………………………………………………………………………………………………………………………………………………………………………………………………….
Addendum – LEO vs GEO satellite internet:
The technical architectures of Low Earth Orbit (LEO) and Geostationary Earth Orbit (GEO) systems are fundamentally defined by their orbital altitude, which dictates their latency, link budget, and network complexity.
- Orbital Mechanics and Altitude:
- GEO satellites reside at a fixed altitude of approximately 35,786 km. They orbit at the same speed as the Earth’s rotation, appearing stationary from the ground, which allows for simple, fixed-point antenna installations.
- LEO satellites operate at significantly lower altitudes, typically between 160 km and 2,000 km. Because they are closer to Earth, they must travel at much higher velocities (approx. 28,000 km/h) to maintain orbit, completing a full revolution in about 90–128 minutes.
- Latency and Propagation Delay:
- GEO: The extreme distance results in a high propagation delay, with a typical round-trip time (RTT) of 500–600 ms. This is unsuitable for real-time applications like VoIP, gaming, or high-frequency trading.
- LEO: Proximity to Earth reduces latency to 20–50 ms, making the performance comparable to terrestrial fiber.
- Link Budget and Power Requirements:
- GEO: High path loss over 36,000 km requires high-power Traveling Wave Tube Amplifiers (TWTAs) and large, high-gain satellite antennas to maintain signal integrity. However, the terminal transmit power required for low-bitrate applications can actually be lower than LEO due to the stable, optimized architecture of legacy GEO MSS systems.
- LEO: Lower path loss enables the use of lower-power RF systems. However, the rapid movement requires complex phased array antennas at the user terminal to electronically track satellites and manage seamless handoffs between nodes in the constellation.
- Network Resilience and Capacity:
- GEO: A single satellite can cover up to 42% of the Earth’s surface, but capacity is centralized; a single point of failure can impact an entire region.
- LEO: Resilience is achieved through distributed constellations of thousands of satellites. These systems often utilize Intersatellite Links (ISLs)—optical or RF mesh networks in space—to route data between satellites, reducing the need for local ground gateways.
| Feature | LEO Architecture | GEO Architecture |
|---|---|---|
| Altitude | 160 – 2,000 km | ~35,786 km |
| Latency (RTT) | 20 – 50 ms | 500 – 600 ms |
| Coverage | Regional/Global via large constellation | ~1/3 of Earth per satellite |
| Terminal Type | Advanced tracking/Phased array | Fixed parabolic dish |
| Operational Life | ~5 years (due to atmospheric drag) | ~15 years |
…………………………………………………………………………………………………………………………………………………………………………………………………………….
References:
https://www.ookla.com/articles/starlink-hits-new-us-highs
Ookla: D2D satellite connectivity surged 24.5% during last 9 months; Starlink’s footprint expansion leads the way
US Mobile’s new bundle combines its multi-network mobile service with Starlink residential internet
Starlink doubles subscriber base; expands to to 42 new countries, territories & markets
Elon Musk: Starlink could become a global mobile carrier; 2 year timeframe for new smartphones
Direct-to-Device (D2D) satellite network comparison: Starlink V2 (Starlink Mobile) vs “Satellite Connect Europe”
Blue Origin announces TeraWave – satellite internet rival for Starlink and Amazon Leo
Amazon Leo (formerly Project Kuiper) unveils satellite broadband for enterprises; Competitive analysis with Starlink
China ITU filing to put ~200K satellites in low earth orbit while FCC authorizes 7.5K additional Starlink LEO satellites
GEO satellite internet from HughesNet and Viasat can’t compete with LEO Starlink in speed or latency
T-Mobile expands FTTH footprint via 50-50 JVs with Oak Hill Capital and Wren House
T-Mobile US is expanding its fiber-to-the-home (FTTH) footprint by investing ~$2.7 billion in two new 50-50 joint ventures (JVs) with Oak Hill Capital ($2 billion for GoNetspeed and Greenlight Networks) and Wren House ($700 million for i3 Broadband). These partnerships aim to pass around 1.8 million homes, largely in the northeastern U.S., accelerating T-Mobile’s fixed broadband expansion alongside their 5G network. Those deals are expected to close in the first half of 2027. T-Mobile, which markets fiber services under the brand name “T-Fiber,” said the deals are part of a plan to serve 18 million to 19 million total broadband customers – including 3 million to 4 million fiber customers – by the end of 2030.
- GoNetspeed offers voice and broadband services to residential and business customers (including multiple-dwelling units, or MDUs) in parts of Alabama, Connecticut, Maine, Massachusetts, Missouri, New York, Pennsylvania and Vermont, with plans to light up networks in cities in New Jersey and Rhode Island. GoNetspeed sells a handful of fiber-fed broadband tiers up to 6 Gbit/s and offers DSL in some areas.
- Greenlight Networks, founded in 2011, supports speeds up to 10 Gbit/s for residential and business customers in New York (Rochester, Buffalo, Binghamton, Capital Region and Hudson Valley), Pennsylvania (Scranton, Wilkes-Barre and Lehigh Valley), and Baltimore, Maryland. It serves about 225,000 homes and nearly 10,000 small businesses.
- i3 Broadband serves parts of Illinois and Missouri with broadband and voice services.
T-Mobile said GoNetspeed and Greenlight are expected to pass a combined 1.3 million households by the end of 2026, with i3 Broadband expected to pass roughly 500,000 households by that time. As it is with T-Mobile’s prior fiber JVs, the service providers involved in this new pair of transactions will operate under wholesale models that enable T-Mobile to offer “simple” plans with no annual service contracts.
- Target: ~1.8 million new homes passed, primarily in the Northeast.
- Partners: Joint ventures with investment firms Oak Hill Capital and Wren House.
- Strategic Goal: Deepen fiber footprint to support a target of 18-19 million broadband customers by 2030, with 3-4 million on fiber.
- Starlink Business Backup: T-Mobile is introducing a Starlink-powered backup option to provide comprehensive, resilient connectivity for business customers, enhancing their “SuperBroadband” offerings.
- Broadband Strategy: This move follows earlier 2025 moves, including the joint venture with EQT to acquire Lumos and the takeover of Metronet, strengthening T-Mobile’s position as a major fiber competitor.
Image Credit: Panther Media GmbH/Alamy Stock Photo
……………………………………………………………………………………………………………………………………………………………
New Street Research analysts David Barden and Vikash Harlalka (via Light Reading) said GoNetspeed passed about 770,000 locations in June 2025, with 725,000 of them passed with fiber, and the rest passed by copper and hybrid fiber/coax (HFC). They also estimate that Greenlight passed about 330,000 locations and i3 Broadband passed roughly 370,000 with fiber as of June 2025. Combined, the three operators involved in the proposed T-Mobile JVs pass nearly 1.5 million total locations, including 1.4 million fiber locations, according to NSR.
Based on an assumption that each fiber network operator has achieved penetration levels of about 25%, New Street said this implies that the Oak Hill JV has about 275,000 customers while the Wren House JV has about 75,000. At that level, they said that means T-Mobile is paying about $725 million for customers from the Oak Hill JV and $250 million for customers from the Wren House JV. The New Street analysts said today’s announcement shows that T-Mobile continues to have interest in acquiring “pure-play fiber operators.” As such, they also believe that the odds of a reported T-Mobile-Uniti deal have dropped.
The analysts also believe that the new fiber-focused JVs will also lower the odds of a potential combination with a major US cable operators such as Charter Communications. “A larger fiber footprint also makes it more difficult to get a deal approved by regulators,” they explained.
……………………………………………………………………………………………………………………………………………………………..
Even with the two new JV’s, T-Mobile’s fiber footprint will still be dwarfed by those of AT&T and Verizon,
- AT&T is targeting a 60 million fiber-to-the-premises (FTTP) footprint by 2030, leveraging joint ventures to accelerate deployment.
- Verizon, following acquisitions of Frontier and Eaton Fiber, projects 32 million fiber passings by 2026, with plans to reach 40–50 million via further partnerships and inorganic growth. Verizon, which also struck a deal to acquire Eaton Fiber last fall, is on track to end 2026 with more than 32 million fiber passings. CEO Dan Schulman reiterated that Verizon plans to broaden its fiber footprint to 40 million-50 million “over the medium term,” but did not provide a more specific timeframe. “There’s no question that fiber is a key differentiator … against competitors that don’t have it,” Schulman said, noting that the attachment rate of Verizon mobile customers who also get broadband from Verizon is hovering at about 55%.
……………………………………………………………………………………………………………………………………………………………..
References:
https://www.lightreading.com/broadband/t-mobile-s-new-jvs-fixate-on-fiber
https://www.lightreading.com/broadband/verizon-surpasses-6m-fwa-subs-as-priority-shifts-to-fiber
T-Mobile US announces new broadband wireless and fiber targets, 5G-A with agentic AI and live voice call translation
Analysis: AT&T 1Q-2026 results: increased fiber penetration, FWA momentum, D2D deals, and mobile/home internet bundles
Evercore: T-Mobile’s fiber business to boost revenue and achieve 40% penetration rate after 2 years
T-Mobile & EQT Joint Venture (JV) to acquire Lumos and build out T-Mobile Fiber footprint
Highlights of 2025 Broadband Nation Expo: Comcast, T-Mobile keynotes + selected quotes
T-Mobile posts impressive wireless growth stats in 2Q-2024; fiber optic network acquisition binge to complement its FWA business
T-Mobile US announces new broadband wireless and fiber targets, 5G-A with agentic AI and live voice call translation
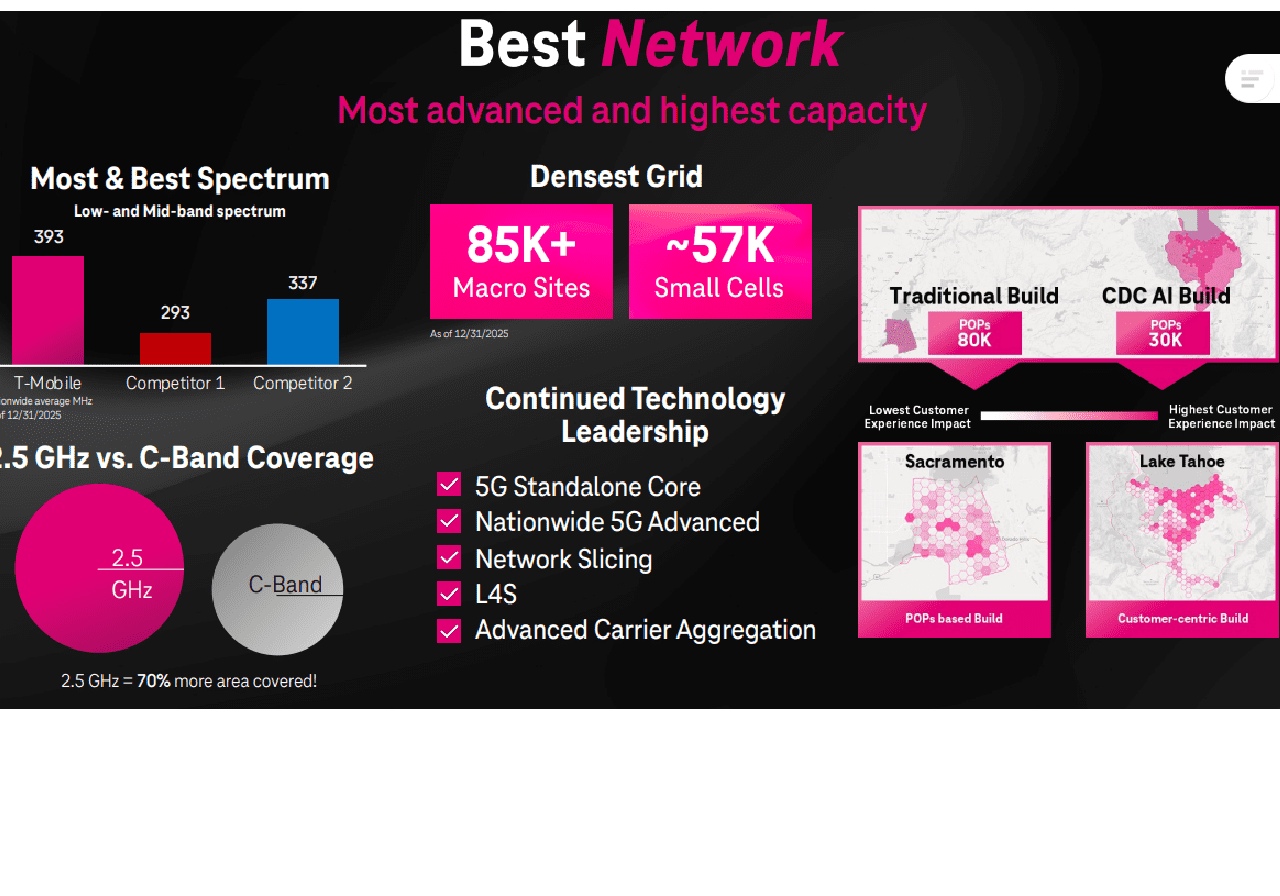
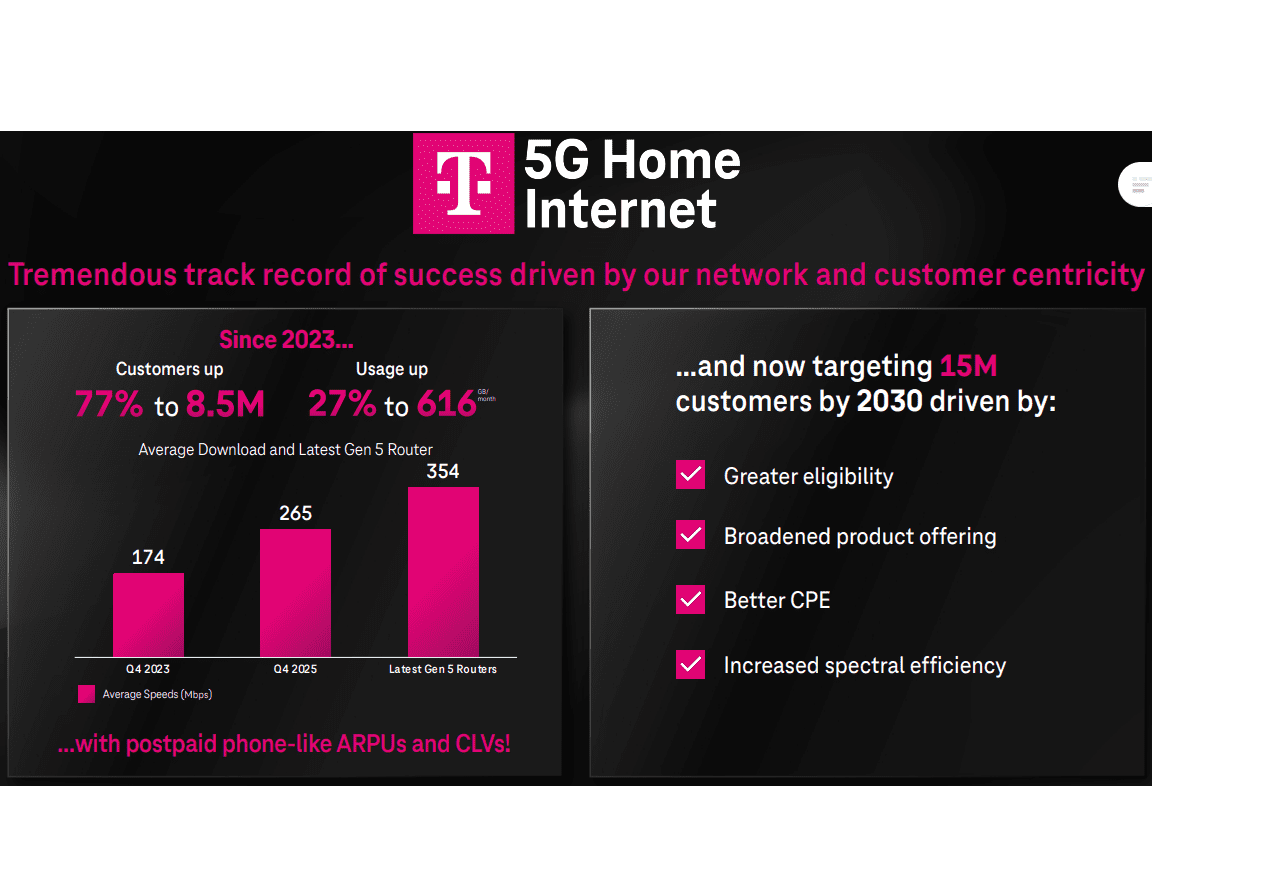
T-Mobile US (the “Un-carrier”) today announced new targets of 15 million 5G broadband customers by 2030, a 25% increase from its previous target of 12 million by the end of 2028, driven by increased spectral efficiency, better CPE technology, increased eligibility including to business customers with complementary usage profiles, and broadened product offerings to continue to meet evolving customer needs. T-Mobile is also leveraging its scale and nationwide 5G Advanced network to expand into new growth areas, including advertising, financial services, and long-term opportunities in edge and physical AI. The top rated U.S. wireless telco is also expecting between 3 and 4 million T-Fiber customers by 2030.
“T-Mobile is raising the bar on what customers, stockholders, and the industry can expect from the Un-carrier. T-Mobile has an unmatched combination of the Best Network, Best Value, and Best Customer Experiences — hallmarks of our unique Un-carrier differentiation — paired with our industry-leading portfolio of assets,” said T-Mobile CEO Srini Gopalan.
“This is why customers bring their connectivity relationship to T-Mobile. Looking ahead, we see an extraordinary runway to further expand this differentiation — through sustained momentum in network perception, digital and AI-driven transformation, and our future-forward innovation in areas like 6G and advanced AI. With this foundation, I’m confident that the future has never been brighter.”
Here are 2 of many impressive slides from T-Mo’s investor presentation referenced below:
The Un-carrier also plans to launch real-time and agentic AI services directly into its 5G-Advanced (5G-A) network by the end of 2026. This initiative, which began with a beta program in early 2026 for postpaid customers, allows for AI-driven features to function natively within the network, meaning users do not need to download specific apps or upgrade their hardware. This 5G-A offering will include live voice call translation in over 50 languages. By integrating AI directly into the 5G-A infrastructure (RAN, core network, and management layers), T-Mobile is enabling features that work on any eligible device, not just smartphones.
New 5G-A Agentic AI Highlights:
- The initial application is a “Live Translation” feature for voice calls, allowing for real-time translation in over 50 languages.
- “Agentic” AI and Automation: The network will use AI to enhance operational efficiency, including predictive optimization and dynamic resource allocation.
- The 5G-Advanced deployment also supports increased data speeds (up to 6.3 Gbps in tests), low-latency applications like XR and cloud gaming, and enhanced location services.
- The forthcoming capability will permit features to be active with only one participant needing to be on the 5G-A network.
- Infrastructure Partners: T-Mobile is collaborating with partners including NVIDIA, Ericsson, and Nokia to build an AI-RAN (Radio Access Network) framework. Telecompaper Telecompaper +3 This move is part of a broader strategy to transition from 5G to 5G-Advanced, with a focus on delivering “intent-driven” AI services and laying the groundwork for 6G (IMT 2030).
……………………………………………………………………………………………………………………………………….
References:
https://www.t-mobile.com/how-mobile-works/innovation/5g-advanced
https://www.t-mobile.com/news/business/t-mobile-capital-markets-day-update-feb-2026
https://www.t-mobile.com/benefits/live-translation
AST SpaceMobile to deliver U.S. nationwide LEO satellite services in 2026
LEO satellite broadband startup AST SpaceMobil Inc. has secured over $1 billion in total contracted revenue commitments from commercial partners, demonstrating strong commercial traction. The company has signed definitive commercial agreements with major telecom operators such as Verizon, AT&T and Saudi Telecom Group (stc) for direct-to-device (D2D) services, thereby expanding its commercial ecosystem. All told, AST has commercial agreements with over 50 mobile network operators with nearly 3 billion subscribers globally.
The company has strengthened its financial position with over $3.2 billion in cash and liquidity, ensuring funding for its satellite constellation and global service expansion. While it has yet to generate revenue from its LEO satellite broadband service, it reported $14.7 million revenue in the third quarter, up from $1.1 million in the previous year, driven by gateway sales to operators and US government contracts.
Importantly, AST said it expects to deliver “intermittent nationwide” LEO satellite service in selected markets in early 2026 with “continuous” service planned for later in 2026 as more satellites are added, according to CEO Abel Avellan, speaking on the company’s third quarter earnings call. In particular:
“We expect to continue scale deployment efforts early next year as we progress activation of an intermittent nationwide service by early 2026 and prepare for continued service later in 2026.”
AST remains committed to its target to have 45 to 60 BlueBird satellites in orbit by the end of 2026, which would enable continuous service across the US, Europe, Japan and “other strategic markets.” Longer-term, the aim is to expand the service to “all targeted” markets with 90 satellites.
Five launches for AST’s next generation BlueBird satellites are planned to take place by the end of the first quarter in 2026, after which launches will be once every one or two months to meet the goal of 45 to 60 satellites in orbit. Of the initial five launches, the first is scheduled for mid-December from India and the remaining four will be from Cape Canaveral with partners SpaceX and Jeff Bezos’ Blue Origin. The latter’s New Glenn rocket can take up to eight BlueBird satellites while SpaceX’s Falcon 9 can carry up to three satellites.
Source: AST SpaceMobile website
……………………………………………………………………………………………………………………………………………………………….
Avellan also said on the call:
“We showcased Canada’s first successful space-based direct-to-cell voice-over LTE call, video call, and other broadband data and video streaming activations. We believe Canada will represent another attractive market for our direct-to-device cellular broadband service. Space-based cellular broadband connectivity is an industry that we invented, and a recent technology milestone with Verizon and Bell follows several breakthroughs using our direct-to-device technology, including the first-ever 4G and 5G voice calls, voice-over LTE calls, live video calls, streaming, full internet access, and tactical non-terrestrial network connectivity for military and defense purposes, from space to modified smartphones.”
“Our direct-to-device cellular broadband network will help our partners deliver on one of their highest priorities, which is extending connectivity for their customers as part of our effort to deliver on those priorities. We are advancing partners and ecosystem network integration as we progress towards service activation in key partner markets.”
AST has ramped up manufacturing capacity so that it will produce six satellites per month from December, adding that these are “the largest satellites ever launched” into low Earth orbit (LEO). “We’re breaking a world record every time that we take a satellite out of the factory,” Avellan said.
The AST CEO is “very confident in the launch campaign.” The company has built 19 satellites so far and will have built 40 by around the end of March next year. “That matches very well with the launches that we had already financially committed and are in the manifest of our launch partners to take them,” Avellan added.
……………………………………………………………………………………………………………………………………………
It should be noted that T-Mobile US started offering Starlink-based D2D services (called T-Satellite) in July this year. Therefore, AT&T and Verizon D2D services with AST will be many months behind their arch rival.
……………………………………………………………………………………………………………………………………………
Andy Johnson, AST’s chief financial officer, described the company’s performance in 2025 as a time of “rapid growth” as it gets closer to its ambition to build its broadband satellite constellation. “The transition from an emerging R&D-focused startup to an operating company on the path to optimizing our manufacturing and launch cadence has been hard yet invigorating and gratifying work for our now nearly 1,800-person worldwide workforce,” he added.
………………………………………………………………………………………………………………………………………………
References:
https://investors.ast-science.com/quarterly-results
https://ast-science.com/spacemobile-network/our-technology/
AT&T deal with AST SpaceMobile to provide wireless service from space
AST SpaceMobile: “5G” Connectivity from Space to Everyday Smartphones
AST SpaceMobile achieves 4G LTE download speeds >10 Mbps during test in Hawaii
AST SpaceMobile completes 1st ever LEO satellite voice call using AT&T spectrum and unmodified Samsung and Apple smartphones
AST SpaceMobile Deploys Largest-Ever LEO Satellite Communications Array
FCC Grants Experimental License to AST SpaceMobile for BlueWalker 3 Satellite using Spectrum from AT&T
T-Mobile’s new CEO Srini Gopalan faces fierce competition from AT&T, Verizon and MVNOs
Today, T-Mobile US promoted Srini Gopalan, from chief operating officer (COO) to CEO. Gopalan is a veteran of parent company Deutsche Telekom as the head of its German home market. He has also held executive roles at Indian telecom company Bharti Airtel, Capital One and Vodafone.
Current CEO Mike Sievert will move into a newly created vice-chairman position. He said in a WSJ interview that he would continue to influence the company’s strategy. “I recruited Srini starting about a year ago with the idea that this day would come,” Sievert said.
T-Mobile has often been recognized for its high-speed 5G network and standalone 5G network capabilities. The “un-carrier” capitalized on the Sprint merger (announced in April 19, 2018; finalized April 1, 2020) to grow its customer base, winning share in both postpaid and prepaid markets and positioning itself as the industry’s fastest-growing carrier. Under Sievert’s tenure, T-Mobile drew millions of broadband customers from cable industry-dominated markets by using its 5G network to beam internet service into homes and businesses. The company is also exploring the wired-broadband business, including through a roughly $5 billion investment in a joint venture with investment company KKR.
Wireless carriers have been grappling with slowing subscriber growth, rising competition and increasingly cautious consumers unwilling to pay for premium plans. T-Mobile’s strongest competitors have been the other two major nationwide mobile carriers Verizon and AT&T. However, the growing market for Mobile Virtual Network Operators (MVNOs), especially from cablecos like Comcast and Charter, has also introduced a new, significant competitive challenge.
Yet both Gopalan and Sievert said the business can keep up the pace as the mobile-phone market matures. “We really like wireless as a neighborhood in the U.S., and we have clearly outperformed everyone else,” Gopalan said in an interview, adding that T-Mobile’s home broadband business has more room to grow. “We’ve shown our hand in fiber. We like pure-play fiber, we like the idea of scaling that business, got two acquisitions already and we’re looking at what other value-creator deals are there.”
Gopalan “brings a wealth of experience a nd is a very impressive leader, and they’ve handled this transition exceptionally well. I don’t expect there to be any fall-off at all in T-Mobile’s performance,” MoffettNathanson analyst Craig Moffett said.
Craig wrote in a research note that a new wholesale deals with Comcast and Charter could give those cable operators an even stronger price edge in business wireless — a market where T-Mobile has been clawing share. “Cable wins. And T-Mobile wins as well,” Moffett wrote, while raising questions about whether the tie-up could lead to deeper partnerships that would reshape the sector. He added that, while T-Mobile is well-positioned in consumer wireless, cable’s entry into enterprise could spark new price wars, making execution under new leadership even more critical.C
T-Mobile has made several acquisitions since it acquired Sprint in 2020. It spent $1.35 billion to acquire Ryan Reynolds’s Mint Mobile in May 2024, giving the company access to more value-conscious phone plan shoppers.
The company has also closed deals for fiber-optic plays Metronet ($4.9 billion), US Cellular ($4.4 billion), and Lumos ($950 million).
References:
https://www.wsj.com/business/telecom/t-mobile-names-telecom-veteran-as-next-ceo-abb4194b
T-Mobile’s growth trajectory increases: 5G FWA, Metronet acquisition and MVNO deals with Charter & Comcast
Evercore: T-Mobile’s fiber business to boost revenue and achieve 40% penetration rate after 2 years
WSJ: T-Mobile hacked by cyber-espionage group linked to Chinese Intelligence agency
T-Mobile posts impressive wireless growth stats in 2Q-2024; fiber optic network acquisition binge to complement its FWA business
T-Mobile to acquire UScellular’s wireless operations in $4.4 billion deal
T-Mobile & EQT Joint Venture (JV) to acquire Lumos and build out T-Mobile Fiber footprint