TÉRAL RESEARCH
6G Architecture and Economics: Core Network Evolution, AI Integration and Business Case
Introduction:
As the telecom industry moves closer to defining 6G features, functions, radio interfaces, and core network architecture, the questions become more demanding: What must change? Who will pay for it? How much of the investment in 5G can be preserved? Discussions at the recent RCR Wireless 6G Forum exposed the tension between introducing new capabilities and protecting operator investment. Although participants described broad support for an evolutionary approach, migration paths and the extent of architectural change remain unresolved.
Keysight’s Stephen Douglas described a standalone 6G architecture with a dedicated core [1.] from the outset, with potential initial commercial systems in mid-to-late 2029. That represents a prospective deployment timeline—not an agreed architecture or guaranteed commercial launch. Ericsson’s Marie Hogan outlined a different emphasis: standalone-style operation from day one, but with an evolutionary core that reuses components of the 5G standalone core while adding new functionality. Ericsson also advocates reusing existing spectrum and introducing a new air interface to deliver improved radio performance. These positions illustrate why “standalone 6G” does not, by itself, establish how much existing infrastructure operators would need to replace.
Note 1. 3GPP has sole responsibility for defining the 6G Core Network Architecture and associated specifications, which will surely be rubber stamped by ETSI (their host entity). Just like in IMT 2020/5G, ITU-T will not publish any IMT 2030 (6G) non-radio standards/recommendations.
Image: 123rf
…………………………………………………………………………………………………………………………………………………………………………………………………………………………………
The role of AI in the 6G core network remains equally unsettled in 3GPP. Approaches under discussion include incorporating AI into network functions, establishing a separate AI domain, and adopting more extensive agent-based architectures. These alternatives imply different requirements for interfaces, control, observability, and interoperability. Consensus is developing, but the 6G core architecture and its network functions have not been agreed.
Traffic forecasts are not investment cases:
Network operators are understandably wary of another capital-investment cycle without a clear path to acceptable returns, following the substantial investment required for 5G. As BT’s Rana Kamill cautioned, “Technology adoption doesn’t guarantee business success by default.” For 6G, commercial requirements must guide technology development from the outset, rather than serve as an after-the-fact justification. The industry should not repeat the mistake of treating a technical capability—such as ultra-reliable low-latency communications (URLLC)—as a business case in itself.
In the lead-up to 5G deployment, network equipment vendors and operators heavily promoted 5G/IMT-2020 URLLC as the foundation for new latency-critical applications, presenting prospective capabilities as commercially imminent. Yet when Release 16 was frozen in 2020, the relevant URLLC RAN enhancements remained incomplete and their targeted performance had not been validated, as documented in our contemporaneous reporting. The lesson for 6G/IMT-2030 is clear: proponents must demonstrate both the required performance across the complete service path and a commercially viable customer proposition—not treat a radio-interface target or a staged demonstration as proof of either.
Ericsson argues that AI-enabled devices and applications will increase uplink demand and eventually require capabilities beyond those of 5G and 5G-Advanced. However, the reported figures are not directly comparable. RCR’s headline describes a sixfold increase, while the article quotes Hogan forecasting a threefold increase followed by a further threefold increase. Separately, the Ericsson Mobility Report presents scenarios projecting twofold, threefold, or fivefold uplink traffic growth by 2031, depending on AI-device adoption and usage. These figures should not be combined into a single settled forecast.
The scale and timing of AI-driven uplink growth therefore remain uncertain. The incremental investment case for 6G depends on where that demand materializes, which capacity, latency, and other performance requirements it imposes, and whether 5G-Advanced can satisfy those requirements more economically.
The vitally important operator 6G investment question is therefore not simply whether AI agents, connected sensors, and physical AI systems generate more traffic. It is which workloads require additional uplink capacity, tighter latency bounds, or new network functionality—and whether those requirements can be met economically through 5G-Advanced rather than a generational replacement. Ericsson itself acknowledges that substantial scope remains to evolve 5G SA and 5G-Advanced before 6G becomes available.
Téral on 6G Standards (ITU-R & 3GPP):
Stéphane Téral, founder and chief analyst at Téral Research, told RCR Wireless 6G Forum 2026 that broad support for an evolutionary 6G does not amount to an agreement on its implementation. He expects continued use of OFDM and 5G channel-coding schemes, helping preserve ecosystem scale and device affordability. However, spectrum choices (from ITU-R- NOT 3GPP) and 5G-to-6G migration paths—including overlay and dual-connectivity options—remain unresolved. The takeaway: agreement on continuity is not yet an agreed deployment blueprint.
Téral also challenged the assumption that 6G requires a dedicated new core (3GPP responsibility), arguing that existing 5G network functions could be sufficient. He identified competing approaches to AI integration: a separate AI domain, AI embedded in network functions, and network-integrated AI agents. Importantly, he distinguished AI-based network optimization, already used for more than a decade, from the requirements of a new mobile generation. The architectural test should therefore be what demonstrably requires 6G—not simply what incorporates AI.
Geopolitical competition adds another obstacle to consensus. “6G leadership is a proxy for future economic and military superiority,” Téral said, warning that competing national and industry priorities could fracture the global standard. Spectrum harmonization, with ITU-R’s WRC-27 an important milestone, remains part of that challenge. His warning highlights the tension between preserving a globally interoperable, affordable ecosystem and pursuing national technological advantage.
His strongest commercial challenge concerned sensing applications: “I see many use cases, but I just don’t see the money, because somebody has to pay for it.” Potential applications, including agricultural weather sensing, do not establish paying customers or sustainable operator returns. The central takeaway is that 6G needs more than technical consensus: proposals must identify what existing infrastructure can be retained, which capabilities justify additional investment, and who will pay for the resulting services. Efficiency gains and new service revenues are distinct economic propositions; neither should be assumed from technical feasibility alone.
Use cases must identify paying customers:
Integrated sensing and communications (ISAC) illustrates the distinction between technical opportunity and commercial demand. AT&T and Ericsson have published a white paper on ISAC, but the fundamental monetization question remains. As cellular industry analyst Stéphane Téral put it at the forum: “I see many use cases, but I just don’t see the money, because somebody has to pay for it.” Identifying a sensing application does not establish who will purchase the service, what they will pay, or whether operator revenue will justify deployment and operating costs.
Incremental improvements can still have economic value: greater capacity, improved spectrum efficiency, and lower operating costs may justify investment without a new “killer application.” But those benefits must be quantified, and claims of new service revenue require a separate commercial case. Hogan acknowledged that distinction, arguing that 6G must deliver measurable monetization or efficiency benefits rather than merely a new generation indicator on a handset.
Conclusions:
The burden of proof rests with each proposed 6G architectural change: what requirement cannot be met economically by 5G-Advanced, what deployed assets can be retained, and what measurable benefit justifies the transition? Capacity expansion and operating-cost reductions can support investment without a “killer application,” but they should not be conflated with new service revenue. A credible 6G strategy must establish those economic cases separately.
The crucial test will be use cases and economics: which business and/or residential customer problems require 6G, what existing assets can be retained, and whether incremental revenue or cost savings justify the transition. The lesson for 6G is not to confuse technical deployment with commercial success. Architecture proposals, traffic forecasts, and application demonstrations must ultimately support a credible investment case—not substitute for one.
References:
https://rcrwireless.com/20261016/6g/6g-standards-teral
https://www.business.att.com/content/dam/attbusiness/briefs/att-ericsson-isac-whitepaper.pdf
Warning: 6G core network must not repeat the 5G SA 3GPP architecture specs vs lack of interoperable standards
Sept 2026 3GPP meeting updates for 5G Advanced and 6G planning (with timeline for submisson to ITU-R WP 5D via ATIS)
Roles of 3GPP and ITU-R WP 5D in the IMT 2030/6G standards process
3GPP approves timelines for Release 21 which will specify 6G RAN, Core and 5G Advanced
Dell’Oro: RAN Market Stabilized in 2025 with 1% CAG forecast over next 5 years; Opinion on AI RAN, 5G Advanced, 6G RAN/Core risks
SK Telecom, Intel develop low-latency technology for 6G core network
IMT-2030/6G Spectrum Sharing: The Roles of WRC-27, NTIA and ITU-R WP 5D
Téral Research: 5G SA core network deployments accelerate after a very slow start
5G deployments started with the non-standalone (NSA) mode (using a 4G core network) and are now gradually migrating to Stand Alone (SA) core network to unleash a plethora of use cases. 5G SA offers improved latency and bandwidth, enabling advanced services and applications. 5G SA features a new sophisticated service-based architecture (5G SBA) developed by the 3GPP. Although many of the network functions (NFs) featured in the 5G SBA come from existing ones currently active in 2G/3G and 4G networks, novel functions such as the network slice selection function (NSSF) are being introduced.
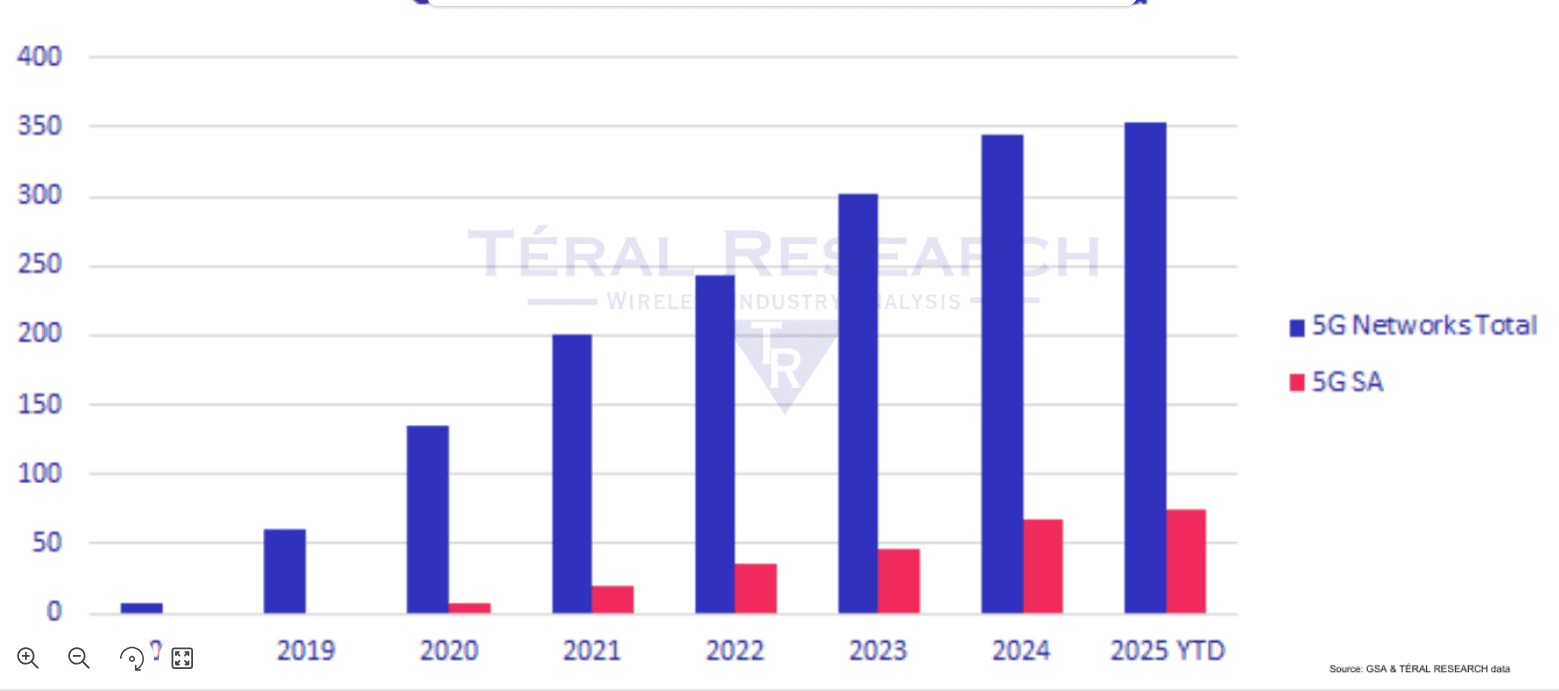
After a very slow start during the past five years, Téral Research [1.] says the migration to 5G SA has increased. Of the total 354 commercially available 5G public networks reported at the end of 1Q25, 74 are 5G SA – up from 49 one year ago. This growth is being driven by the success of fixed wireless access (FWA), a wider range of 5G SA-compatible devices, and the rise of voice over new radio (VoNR). Téral is also seeing increased adoption of private cloud for SA core deployments, with data sovereignty concerns shaping CSP strategies. Network slicing, which requires 5G SA, is moving from theory to practice—now extending to critical use cases like military applications.
Huawei, Ericsson, Nokia, and ZTE Corporation continue to lead the vendor landscape, but with more than 550 networks yet to migrate, the 5G SA Core market is only beginning to scale. With 20% growth expected this year, the next phase of 5G is officially underway.
Note 1. Based on a communications service provider (CSP) survey and discussions with many vendors, Téral Research’s 5G SA report analyzes several of the 5G Core SBA functions and provides global and regional market sizes and forecasts by focusing on the NFs implemented by CSPs (e.g., UDM, UDR, AUSF, NRF, NEF and NSSF, PCF, BSF, CHF) to enable use cases beyond enhanced mobile broadband (eMBB), fixed wireless access (FWA), and private 5G.
……………………………………………………………………………………………………………………………………………………………………..
2024 had the highest number of 5G SA commercial launches: 21 networks went live to offer commercial 5G SA services last year. The success of FWA services, the introduction of smartphone plans enabled by the increasing number of available 5G SA devices, and the rise of VoNR drove this SA migration.
Key findings include:
-
Network slicing is taking off for various services, including for military use cases.
-
The single vendor approach remains predominant for each domain.
-
67% of 5G SA core deployment are cloud-based but due to data sovereignty concerns,
CSPs favor private cloud infrastructures.
-
The global 2024 market for 5G SA Core + SDM + Policy & Charging grew 12% YoY and hit $3.8B, slightly below our forecast.
-
Sustained by its domestic market, Huawei leads global 2024 sales for 5G SA Core + SDM + Policy & Charging, followed by Ericsson and Nokia, respectively. However, Nokia leads the global commercial 5G SA footprint. ZTE comes in fourth place for global total sales and second for 5G SA core sales behind Huawei.
In the meantime, technical challenges related to 5G network architecture complexity, 3GPP methods for exchanging information across 4G vs. 5G, policy orchestration and enforcement, real-time analytics and insights and data analytics are still lingering but being solved.
Built on a solid CSP pipeline of 559 cellular networks in the world that have yet to be migrated to 5G SA, Téral’s model produced a forecast that shows the global 5G SA Core/5G Data Management/5G Policy market to cross the $4B bar by year-end, which is 20% YoY growth. Last year’s downward revision put our forecast on track and therefore we have not made any significant change in this forecast update.
……………………………………………………………………………………………………………………………………
Editor’s Note: In 2025, about a dozen more mobile network operators (MNOs) are expected to deploy 5G Standalone (SA) networks, according to Fierce Network and Moniem-Tech. This will include some major CSPs like AT&T and Verizon, who have previously deployed 5G SA on a limited basis. ……………………………………………………………………………………………………………………………………
In the long run, Teral foresees a significant ramp up in CSPs’ migration to 5G SA that adds to the ongoing activity continuously fueled by the emergence of new use cases going beyond eMBB, FWA, and private 5G. Therefore, Téral expects the market to grow at a 2025-2030 CAGR of 11%. Asia Pacific will remain the largest market throughout the forecast period and 5G SA core the most important domain to start with, followed by 5G Data Management.
Finally, the disaggregated multi-domain nature of 5G core SBA brings a broad range of contenders that include the traditional telecom network equipment vendors, a few mobile core specialists, a handful of subscriber data management (SDM) specialists, a truck load of policy and charging rules function (PCRF) players, the OSS/BSS providers and the system integrators and providers of IT services.
References:
Téral Research :: June 2025 5G SA Core, SDM and Policy
Ookla: Europe severely lagging in 5G SA deployments and performance
Vision of 5G SA core on public cloud fails; replaced by private or hybrid cloud?
GSA: More 5G SA devices, but commercial 5G SA deployments lag
Building and Operating a Cloud Native 5G SA Core Network
Latest Ericsson Mobility Report talks up 5G SA networks and FWA
Global 5G Market Snapshot; Dell’Oro and GSA Updates on 5G SA networks and devices
Dell’Oro: Mobile Core Network market has lowest growth rate since 4Q 2017
5G SA networks (real 5G) remain conspicuous by their absence
TÉRAL Research: Sharp declines in Wireless Infrastructure Market 1Q-2024
The global wireless infrastructure market, including 2G/3G/4G/5G RAN and core networks, experienced significant declines both sequentially (-31%) and YoY (-26%) in 1Q-2024. However, these declines are not unprecedented.
“Such decline has happened before in 2002 and 2003 due to a sharp decrease in TDMA and PDC systems shipments, as well as in the post-LTE peak era from 2016 to 2019, when each year’s first quarter posted a 20%+ YoY decline. And that’s not all, looking at bellwether Ericsson’s networks sales historical data, 1Q was also down 20%+ sequentially during the 5G boom,” said Stéphane Téral, Founder and Chief Analyst at TÉRAL RESEARCH.
Huawei continues to be the largest wireless network infrastructure vendor, Nokia and ZTE Corporation’s lost market share, while Samsung Networks position was steady.
Téral states that 2024 marks the third consecutive year of a wireless disinvestment cycle yet the market is poised for a slight rebound in 2H2024 driven by open RAN and 5G upgrades.
………………………………………………………………………………………………………………..
Stéphane attended Oracle’s Applications & Industries Analyst Summit at the Oracle Conference Center in Redwood Shores, California. This two-day event showcased how Oracle is integrating Generative AI into its Fusion Data Intelligence Platform, enhancing ERP, EPM, SCM, HCM, and CX applications with AI-powered updates. Oracle’s industry verticals, particularly their 5G CSP monetization and digital experience strategies, promise to end the 5G monetization drought. With Oracle migrating databases to its cloud and leveraging AI, CSPs can expect increased efficiency and growth.
References:
https://www.linkedin.com/pulse/whats-new-t%C3%A9ral-research-t-ral-research-qsmec/
https://www.teralresearch.com/resources
Dell’Oro: RAN revenues declined sharply in 2023 and will remain challenging in 2024; top 8 RAN vendors own the market
Dell’Oro & Omdia: Global RAN market declined in 2023 and again in 2024
Dell’Oro: Optical Transport, Mobile Core Network & Cable CPE shipments all declined in 1Q-2024
Global 5G Market Snapshot; Dell’Oro and GSA Updates on 5G SA networks and devices
Dell’Oro: Mobile Core Network market has lowest growth rate since 4Q 2017
What is 5G Advanced and is it ready for deployment any time soon?