Optical Network Architecture
Toshiba Wins UK Contract to Advance Commercial Quantum Networking: Can It Leverage Existing Optical Fiber Infrastructure?
Disclaimer: ChatGPT was used extensively to research and analyze the references cited in this article. The author provided editorial guidance and direction, reviewed the material, and is 100% responsible for the article’s final content.
…………………………………………………………………………………………………………………………………………………………………………………………………………………………………….
Introduction:
Toshiba Europe has been awarded a contract by Innovate UK, part of UK Research and Innovation (UKRI), to develop technologies intended to accelerate the commercial deployment of quantum networks. The Innovate UK-funded project targets scalable, multi-user quantum networks, but specialized Physical-layer requirements and deployment economics could limit their integration with conventional carrier optical networks. The project will focus on technologies for long-distance quantum links and multi-user quantum networks, with prototype subsystems evaluated under realistic operating conditions.
The contract was awarded through Innovate UK’s Enabling Commercial Quantum Networking competition, which supports UK companies developing components and subsystems for quantum networks. The competition represents a combined £20 million investment in the UK’s quantum technology ecosystem and aims to strengthen domestic capabilities across the emerging quantum networking supply chain.
The project supports the UK’s National Quantum Strategy, which includes an ambition to deploy advanced quantum networks at scale by 2035 and establish foundations for a future quantum internet. Such networks could eventually enable quantum information to be distributed among geographically separated quantum computers and other quantum systems.
Toshiba will develop and evaluate prototype subsystems designed to make quantum networks easier and more economical to expand using the UK’s existing optical fiber infrastructure. The work will investigate more efficient utilization of network resources and management of connectivity as the number of connected users and sites increases. Improved resource utilization could reduce infrastructure requirements and capital expenditures while making quantum networking services more accessible to telecommunications operators and customers.
UK network operators BT and Colt Technology Services will collaborate on validating the technology against practical network deployment and operational requirements.
Quantum networking and telecommunications infrastructure:
A significant longer-term application of quantum networking is connecting quantum processors located in separate data centers so that they can potentially work together on distributed computational tasks. Interconnecting quantum processors could expand the computational resources available to researchers and organizations and contribute to advances in areas such as pharmaceutical discovery and materials science. However, scaling quantum networks presents substantial engineering challenges. Unlike conventional optical communications, which transmit classical information using light, quantum networks must distribute and preserve fragile quantum states. This introduces requirements for specialized optical components, quantum-state management, synchronization and, ultimately, quantum repeaters capable of extending quantum communications over longer distances.
Integration with existing carrier fiber infrastructure is another important consideration. Network operators must address fiber loss, optical signal coexistence, routing, resource allocation and operational management while accommodating the specialized requirements of quantum communications.
One potential approach is to multiplex quantum and conventional data channels over the same optical fiber using wavelength-division multiplexing (WDM). This could avoid the expense of deploying entirely separate fiber networks. However, conventional optical signals can introduce noise and other impairments that degrade quantum channels. Raman scattering, optical power levels, fiber attenuation and losses introduced by multiplexers and other optical components all require careful engineering.
Furthermore, conventional optical amplifiers cannot simply be used to amplify unknown quantum states because of the quantum no-cloning principle. Quantum repeaters, which are needed to extend quantum communications over longer distances without relying on conventional amplification, remain a significant technology-development challenge.
Consequently, sharing existing fiber infrastructure does not necessarily mean that quantum networks can use conventional carrier optical equipment, transmission systems and operational procedures without substantial modification.
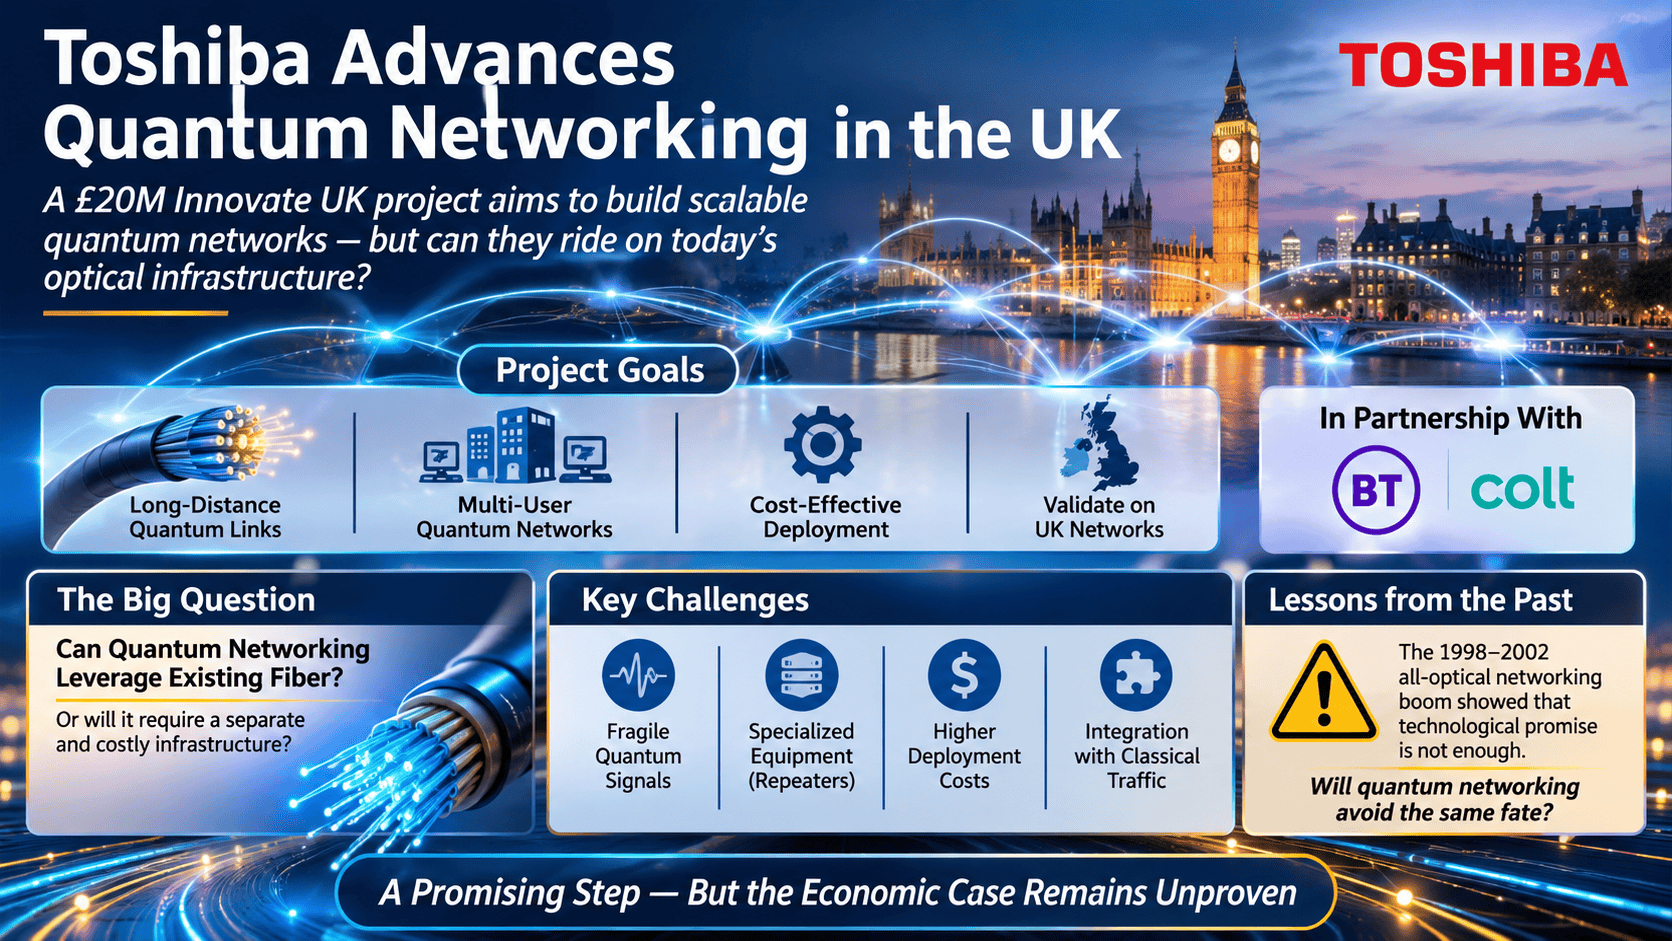
Image Created by ChatGPT
……………………………………………………………………………………………………………………………………………………………
Can quantum networking become an economically viable extension of carrier optical networks?
This is arguably the most important commercial question surrounding Toshiba’s project. The telecommunications industry has a long history of investing in promising optical networking technologies that did not achieve their anticipated commercial potential. During the 1998–2002 optical networking boom period, substantial investment went into photonic switching and all-optical networking. The vision was to eliminate repeated optical-electrical-optical (O-E-O) conversions, allowing data to remain in the optical domain throughout the network. That was supposed to usher in ultra-long-haul, repeater-less optical transmission. Photonic switches were expected to deliver enormous capacity improvements, reduce equipment complexity and lower network costs.
Despite considerable technical development and industry investment, all-optical switching did not become the dominant architecture envisioned by its proponents. Although optical circuit switches, MEMS-based photonic switches and ROADMs achieved commercial deployment in carrier networks, the broader vision of entirely photonic networking—with switching logic and control performed optically and without electronic processing—never became a commercially viable mainstream architecture. Conventional optical transport networks instead evolved through improvements in WDM, coherent optics, optical amplification, electronic switching and increasingly sophisticated optical-electrical-optical interfaces. The telecommunications industry ultimately favored hybrid optical-electronic networks.
Quantum networking could face a comparable commercialization problem. The ability to demonstrate quantum communication over existing fiber does not establish that a scalable, economically competitive carrier network can be built using conventional optical infrastructure.
There have been encouraging demonstrations of quantum and classical communications sharing the same fiber. For example, Toshiba and KDDI reported in March 2025 a demonstration carrying 33.4 Tbps of conventional data traffic alongside quantum key distribution (QKD) over an 80-kilometer fiber. This is an important proof of technical feasibility, but it does not establish the economics of a nationwide, multi-user quantum network.
There are also fundamental differences among quantum networking applications. QKD distributes cryptographic keys, while entanglement-based networking and distributed quantum computing require additional capabilities and substantially different performance characteristics. Success in multiplexing QKD with conventional traffic does not automatically demonstrate that geographically distributed quantum computers can be interconnected economically.
My assessment is that quantum networking is more likely, at least initially, to require specialized infrastructure and equipment than to become a straightforward extension of today’s carrier optical transport networks. Existing fiber may be reusable in selected applications, particularly metropolitan links and carefully engineered WDM deployments. But specialized quantum transmitters, detectors, synchronization systems, quantum memories, repeaters and associated control systems could impose substantial additional capital and operating expenses.
The economics become even more challenging when dedicated fiber, trusted intermediate nodes, environmental controls and specialized maintenance are required. Carrier operators will need to justify these costs against the actual revenue-generating applications and the alternatives available to customers.
The US and European quantum networking research communities have demonstrated that coexistence with conventional optical traffic is possible. Nevertheless, practical quantum repeaters, long-distance entanglement distribution, multi-vendor interoperability and scalable network management remain important obstacles.
It is therefore premature to assume that quantum networking will develop into a broadly deployed carrier service simply because existing fiber can be used in selected demonstrations.
The photonic switching experience of 1998–2002 is a useful cautionary precedent: technically impressive demonstrations and substantial R&D investment do not necessarily translate into commercially successful network architectures.
Toshiba’s quantum technology background:
The project builds on more than 25 years of Toshiba research and development in quantum technologies. The company recently introduced its Quantum-Safe Networking (QSN) Platform, designed to help organizations integrate quantum-safe protection into existing communications networks with reduced complexity, equipment footprint and cost.
It is important to distinguish these two technology areas. Quantum networking seeks to distribute quantum information and connect geographically separated quantum systems. Quantum-safe networking, by contrast, protects conventional communications against current and anticipated future cryptographic threats, including those posed by sufficiently powerful quantum computers.
Although related through their use of quantum technologies, these are distinct applications with different architectures, infrastructure requirements and deployment objectives.
Conclusions:
Toshiba’s collaboration with BT and Colt is a worthwhile technology-development effort addressing a genuine challenge: how to scale quantum networking without incurring the prohibitive cost of building entirely new fiber infrastructure. However, the critical test is not whether quantum signals can coexist with conventional data traffic over selected fiber links. It is whether the complete quantum networking architecture—including its specialized optical components, repeaters, control systems, maintenance requirements and operating costs—can deliver sufficient commercial value to justify deployment by telecommunications operators. Until that economic and technical case is demonstrated at meaningful scale, expectations for quantum networking as a natural extension of existing carrier optical infrastructure should remain guarded.
The historical lesson from the 1998–2002 photonic switching and all-optical networking boom is not that optical switching failed altogether. Rather, the ambitious vision of an entirely optical network, eliminating electronic switching and processing throughout the network, never materialized. Commercial optical switching did succeed, particularly at the wavelength and circuit layers, through technologies such as MEMS switches and reconfigurable optical add/drop multiplexers (ROADMs). However, electronic switching, processing and control remained essential components of commercial carrier networks. The industry ultimately adopted hybrid optical-electronic architectures rather than the fully photonic networks originally envisioned.
Quantum networking faces a similar commercialization challenge. Will it establish economically viable applications as a specialized extension of conventional optical networks, leveraging existing fiber wherever technically feasible? Or will its unique physical-layer requirements—including quantum repeaters, specialized transmitters and detectors, synchronization and stringent signal-management requirements—necessitate largely separate infrastructure with substantially higher deployment and operating costs? The ability to demonstrate quantum communications over existing fiber is encouraging, but does not establish that a scalable, commercially competitive carrier-network architecture is achievable. Ultimately, as with photonic switching, technical feasibility must translate into compelling economics and sustainable customer demand.
……………………………………………………………………………………………………………………………………………………………………………………………………………………
References:
Toshiba awarded contract to advance commercial quantum networking in the UK
UK Government – Quantum Key Distribution Research Report
https://www.gov.uk/government/publications/quantum-key-distribution-research-report/quantum-key-distribution-research-report
GSMA – Quantum Technologies and Telecom Use Cases (PDF)
https://www.gsma.com/solutions-and-impact/technologies/quantum-technologies/wp-content/uploads/2026/02/IG.19-Quantum-Technologies-Telcom-Use-Cases.pdf
CNAS – The Entanglement Edge (May 2026)
https://www.cnas.org/publications/reports/the-entanglement-edge
Nature – Quantum and Classical Coexistence over Hollow-Core Fiber
https://www.nature.com/articles/s41534-025-01125-7
ARCEP – Quantum Technologies and Their Impact on Networks (June 2026, PDF)
https://en.arcep.fr/uploads/tx_gspublication/futur-networks-briefing-note-quantum-technologies_june2026.pdf
PsiQuantum Targets AI Data Center Networks with Silicon-Photonic Optical Switching
2026 OCP Summit: Full-Stack AI Networking Silicon from Nvidia/Cisco and Broadcom; Ethernet vs InfiniBand Interconnects
Goldman Sachs report: Optical Networking is the next mega trend in AI infrastructure
2026 Fiber Connect Keynote: “The Future of Fiber Optics: AI and the Quantum”
IBM to Build World’s First Large-Scale, Fault-Tolerant Quantum Computer – Starling
Countdown to Q-day: How modern-day Quantum and AI collusion could lead to The Death of Encryption
Ultra-secure quantum messages sent a record distance over a fiber optic network
Google’s new quantum computer chip Willow infinitely outpaces the world’s fastest supercomputers
Quantum Computers and Qubits: IDTechEx report; Alice & Bob whitepaper & roadmap
Bloomberg on Quantum Computing: appeal, who’s building them, how does it work?
Impact of optical component shortages & bottlenecks explained + Hyperscaler’s CAPEX
LightCounting’s August 2026 market and component report highlights how severe physical supply shortages for high-speed optical components are reshaping data-center architectures and forcing cloud builders to expand their vendor pools from the traditional 2-3 suppliers up to 5-7 specialized hardware manufacturers. Qualifying and managing all of them is a new challenge.
- Applied Optoelectronics, Macom, and MaxLinear have already reported accelerating growth in Q2 2026 and we expect to see more examples in the upcoming earnings reports.
- Coherent and Lumentum have also reported improvements in growth rates for the last quarter, catching up with Eoptolink and Innolight (reporting at the end of August). Eoptolink has already disclosed a sharp increase in the profits expected for Q2. Accelink and CIG also report sharply higher profits.
- Tower Semiconductor reported triple-digit growth (y-o-y) in silicon photonics revenue in Q2-2026.
- GlobalFoundries plans to double its silicon photonics business in 2026.
- Cisco reported “a remarkable 28% y-o-y increase” in the networking segment revenues, up from 25% in Q1. Cisco reported three new hyperscale AI design wins and 40% growth in orders during the quarter. The company also reported record orders for campus networking – up 20% y-o-y.
- Arista Networks reported Q2 2026 revenue of $3.04 billion, marking its first-ever $3 billion quarter. This represented a roughly 38% year-over-year increase. Management also raised its full-year 2026 revenue growth outlook to 40%.
- Calix reported 21% y-o-y growth in Q2 and guided for another 15% in the current quarter. Growth in company’s revenue is attributed to sales of broadband equipment and AI-enhanced software to telecom operators.
- Extreme Networks reported 14% y-o-y growth in product sales, in part driven by success of its agentic AI networking platform.
Surging data-center traffic driven by AI queries has created acute optical component shortages, fundamentally altering supply chain qualifications for hyper-dense network switches and interconnects. The primary optical component bottleneck is a severe production shortage of Indium Phosphide (InP) laser chips and EML (Electro-Absorption Modulated Laser) components, which are failing to keep pace with a projected 53% surge in total optical transceiver and hardware demand, reaching $39 billion. Current demand for high-speed datacom optics is outstripping available supply by roughly 30%, forcing hyperscalers and system vendors to fundamentally restructure their supply chains. More details in the Addendum at the end of this article.
………………………………………………………………………………………………………………………………………………………………………………………………
Dell’Oro Group says that the rise of agentic AI and inference workloads is driving new demand and introducing network requirements that differ from those associated with training workloads. This shift is leading to significant expansion of front-end networks to support the broader buildout of AI infrastructure. We estimate that more than half of the growth in Front-end Data Center Switch sales over the next few years will be driven by AI-related opportunities. These deployments represent net-new expansion opportunities for both established vendors and new market entrants.
Accton, Arista, Celestica, Cisco, HPE/Juniper, H3C, Huawei, NVIDIA and others—emerge as the primary beneficiaries of this growth, according to the market research company.
“As AI infrastructure shifts from large-scale training to inference and agentic workflows, there is an increasing demand for general-purpose infrastructure, and expanded front-end network requirements,” said Sameh Boujelbene, Vice President at Dell’Oro Group. “The traditional assumption of a 10-to-1 ratio of XPU to CPU no longer applies across all deployments, with some environments moving closer to a 1-to-1 ratio. CPUs are becoming increasingly important for workloads orchestration and data movement. Additionally, networking for KV caching storage rack is also needed for inferencing applications,” added Boujelbene.
……………………………………………………………………………………………………………………………………………………………………………………….
As for the network providers/ISPs:
- Verizon announced a dark-fiber deal with Google to support the hyperscaler’s data center traffic growth. The deal is valued at over $1 billion and Verizon said there will be other deals announced before year-end.
- Deutsche Telekom said its AI factory for Germany’s public institutions and businesses that opened in February, has already sold the site’s 10,000 Blackwell GPUs capacity. DT is now looking at increasing capacity by another 20,000 GPUs.
- Comcast cites that its upstream broadband traffic is growing at 2.5x the rate of downstream data, which it links to AI-driven queries.
- AT&T is seeing rapid increases in large-scale data traffic requiring high-capacity metro and intercity fiber infrastructure.
Capex of Telecom Service Providers is still expected to be flat (or down 1%) in 2026, but AT&T and Comcast reported 16% and 20% y-o-y growth in capex for Q2, respectively. Both companies are investing more in broadband access. Verizon’s capex was also up, but only by 5% in Q2.
……………………………………………………………………………………………………………………………………………………………………………………….
Hyperscaler CAPEX:
The chart below illustrates the capital intensity of the TOP 4 Cloud companies. It is up sharply: Meta is already at 51% and Microsoft is at 46% in Q2. Oracle (not included in the figure) would have been off the chart at above 80% in Q1. The company reports earnings in early September and the key question is how it intends to finance future investments. Some moderation in spending growth is well needed. Amazon is the largest spender with $54.2 billion for the quarter, up 73% y-o-y. Amazon also increased guidance for 2026 capex from $200 billion to $220 billion.

Recent $ Trillion fundraising activities of Anthropic and OpenAI, supported by Nvidia, were widely covered yet both companies continue to lose money. Some financial experts refer to these activities as the “future for financial engineering.” Any innovation comes with some risk, but we all hope for the best.
………………………………………………………………………………………………………………………………………………………………………………………
Addendum: Optical Network Bottlenecks Explained:
-
- InP Epitaxial Production Limits: The primary physical constraint lies in the fabrication and epitaxy capacity for Indium Phosphide wafers used to build high-frequency lasers, where specialized manufacturing equipment (such as MOCVD systems) remains heavily backordered.
- Electrical Trace and Power Walls: Inside massive AI clusters, traditional pluggable optical modules face severe latency, thermal, and signal-integrity walls due to long copper electrical traces running from switch ASICs to the optical engine.
- Packaging and Testing Complexities: Shifting from legacy designs to dense 800G, 1.6T, and co-packaged optics (CPO) introduces intricate multi-die integration and hybrid bonding hurdles that slow down final module validation and packaging yields.
- Expanding Vendor Pools: Cloud builders are aggressively expanding their sourcing lists, moving from a concentrated pool of 2–3 legacy optical vendors out to 5–7 specialized component manufacturers to secure allocation.
- Ecosystem Pivot to Photonics: Major semiconductor players (such as Marvell’s acquisition of Celestial AI) and optical fabricators are pouring capital into silicon photonics and optical interconnect architectures to bypass standard copper and discrete laser constraints.
-
- Mechanism: LPO removes the power-hungry Digital Signal Processor (DSP) and clock/data recovery (CDR) chips directly from inside the optical transceiver module.
- The Fix: Raw, linear analog signals are driven straight from the switch or network interface card (NIC) ASIC.
- Benefits: Slashes module power consumption by 50% or more and cuts latency while preserving the hot-swappable, multi-vendor front-panel pluggable form factor.
- Trade-off: Requires host ASICs with advanced analog front-end and signal-equalization capabilities to process the raw electrical signals.
- Mechanism: CPO moves the optical engine (which converts electrical signals into light) off the front-panel cage and places it directly onto the same substrate or interposer as the switch or accelerator ASIC.
- The Fix: Electrical traces shrink from centimeters down to mere millimeters, completely bypassing lossy copper-clad circuit boards and high-power SerDes requirements.
- Benefits: Reduces optical-interface power consumption by up to 75% and maximizes bandwidth density for ultra-dense GPU scale-up fabrics.
- Trade-off: Reworks serviceability—if an optical engine fails, the repair domain shifts from a simple two-minute transceiver swap to board- or switch-level replacement
………………………………………………………………………………………………………………………………………………………………………
References:
Agentic AI and Inference to Supercharge Front-End Networks Growth, According to Dell’Oro Group
Networking chips and modules for AI data centers: Infiniband, Ultra Ethernet, Optical Connections
Goldman Sachs report: Optical Networking is the next mega trend in AI infrastructure
Cisco Execs: New “Network Supercycle” as Agentic AI Workloads Reshape Telecom Infrastructure
Cisco report: Agentic AI to reshape WAN traffic, AI inference will be ~25% of total traffic by 2035
Meta’s “Iris” AI Chip for MTIA: Implications for Telecom-Grade Optical Networking, DCI and High Capacity Ethernet Fabrics
Oriole Networks photonic networking platform to be integrated with AMD GPUs/CPUs for next-gen AI data center fabrics
Cheap Chinese AI Models: Unappreciated Threat to U.S. Hyperscaler AI Dominance
Verizon’s $1 Billion Google Dark Fiber Deal Highlights Importance of Optical Networks
Executive Summary:
Verizon CEO Dan Schulman said on Friday the company had secured a more-than-$1 billion dark fiber agreement with Google. It underscores how hyperscale AI growth is elevating dark fiber, route diversity, and high-capacity optical engineering into core industry priorities and is evidence that the network layer is becoming a central enabler of AI-scale computing. The deal, disclosed during Verizon’s Q2 2026 earnings call, is intended to connect Google data centers and support the transport demands of AI workloads.
“We have other deals that we expect to announce by year end that taken together are expected to be worth multiple billions of dollars in revenue over the next several years,” Schulman said on Verizon’s post-earnings call.
From a telecom perspective, the significance lies in the shift from best-effort connectivity toward engineered optical infrastructure with explicit performance objectives. As hyperscalers expand distributed AI training and inference, the requirements for capacity, latency, route diversity, and operational control increasingly favor dark fiber over shared transport models.blogs.cisco+2
Why This Matters for Network Architecture:
Dark fiber gives the customer direct control over the optical layer, enabling custom design choices for line rates, protection schemes, and traffic engineering. That flexibility is especially relevant for large data-center interconnect environments, where traffic growth can quickly outpace conventional managed services.blogs.cisco+1
The Verizon-Google transaction also reinforces the role of long-haul and metro fiber as strategic infrastructure rather than commodity bandwidth. In practice, this places greater emphasis on fiber route resilience, diverse path design, and the ability to scale toward higher-capacity optical systems as AI clusters expand.blogs.cisco+1
Standards and Industry Implications:
While the deal itself is commercial, its implications touch several standards-adjacent concerns that are increasingly important to operators and vendors. These include high-capacity optical transport, inter-domain coordination, deterministic latency for distributed workloads, and the operational models needed to support AI-driven traffic growth.blogs.cisco+1
For IEEE ComSoc readers, the broader signal is that future network evolution may be shaped as much by AI infrastructure economics as by traditional access or mobility growth. The value proposition is moving toward fiber-based transport layers that can support hyperscale interconnect, cloud adjacency, and resilient backhaul for distributed computing environments.benton+1
Conclusions:
Verizon’s reported dark fiber deal with Google suggests that optical connectivity is no longer a passive enabler but a competitive differentiator in the data-center supply chain. It highlights a broader shift in network economics: AI growth is elevating fiber infrastructure from a supporting asset to a strategic enabler. For carriers, the message is clear — the winners in the AI era may be those that can pair scale, route control, and transport engineering with the capacity demands of hyperscale cloud buildouts.
Text & Images from Sebastian Barros:
Verizon’s billion dollar agreement with Google shows that the AI infrastructure boom is moving beyond chips, data centers and electricity. The next constraint is connecting everything together. Verizon will use existing fiber where possible and construct new routes where necessary. It can provide either dark fiber or managed, lit capacity, depending on what the customer wants.
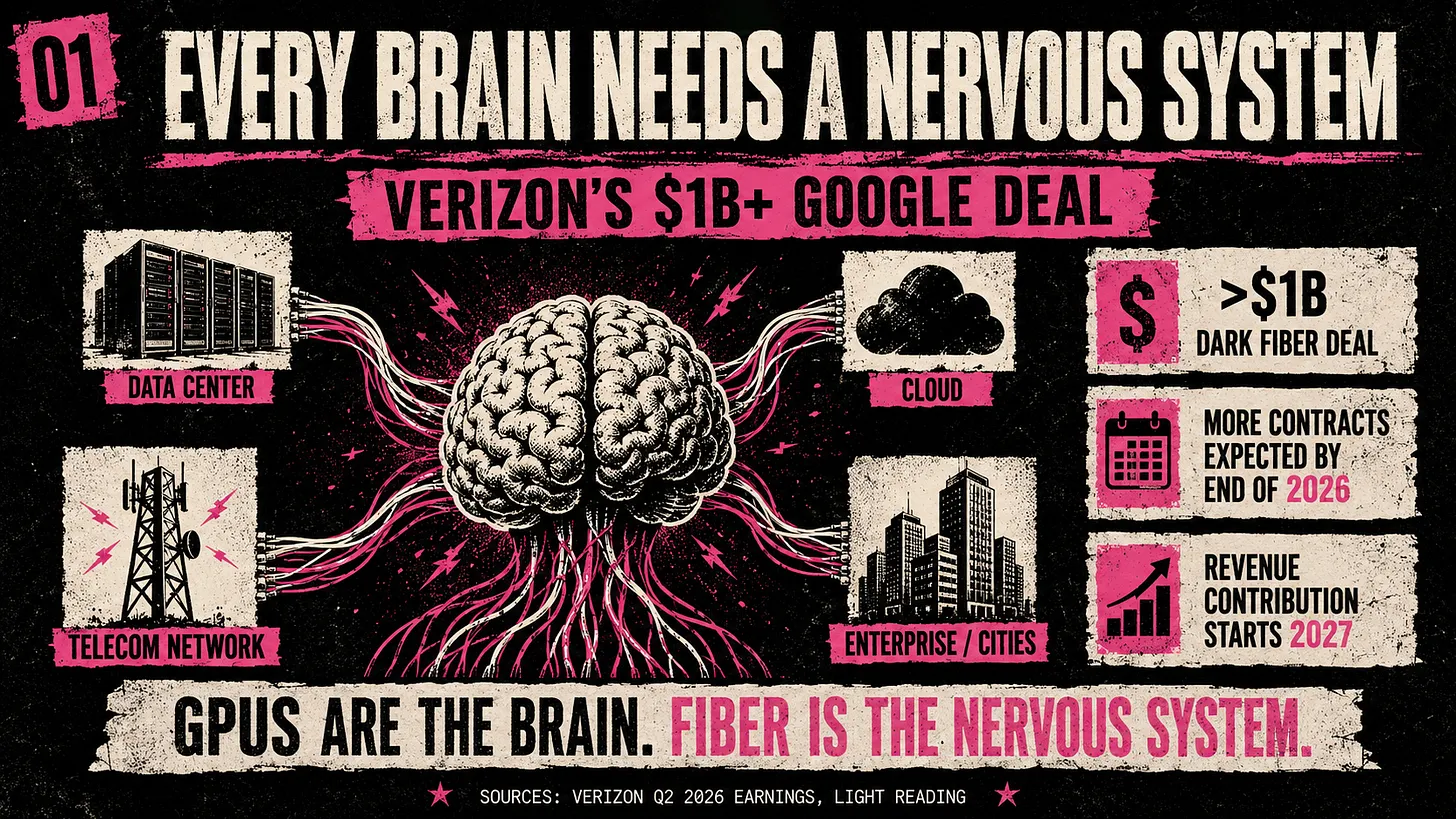
Google already operates one of the most advanced private networks in the world. Its infrastructure spans more than two million miles of lit fiber, 33 subsea cable investments, more than 200 network edge locations, and thousands of content delivery sites. Yet Google still needs Verizon to provide additional routes.
The (hyperscaler) companies building the largest AI brains cannot build every nerve themselves, as the pace is too fast. The telco opportunity begins when data needs to leave the campus.
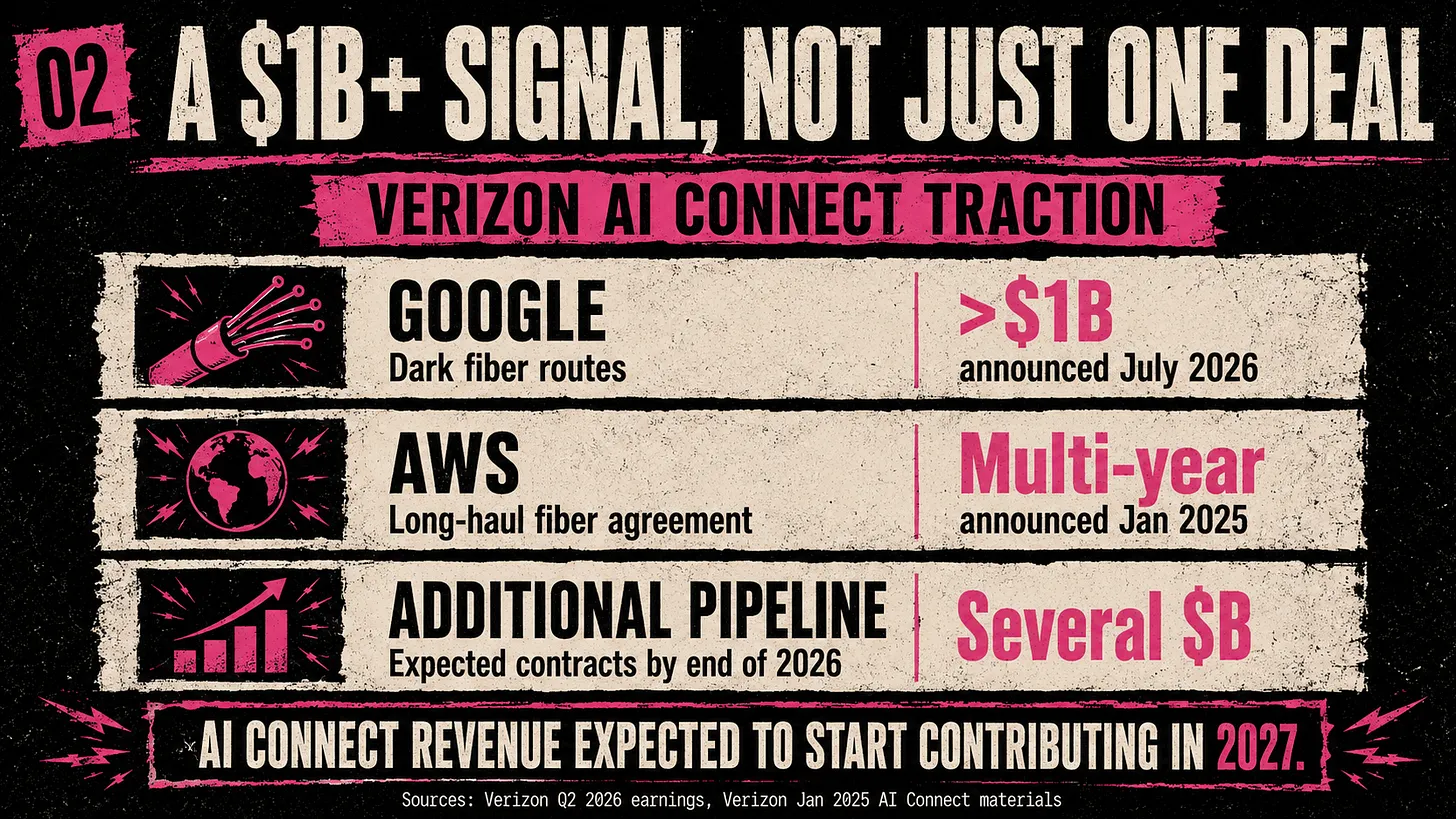
Models must be copied between regions; training datasets must be moved from storage locations to computing clusters; companies need private connections to cloud platforms; AI applications must retrieve enterprise information stored across different data centers. Inference results must reach factories, vehicles, hospitals, stores, offices, and consumers.
AI therefore requires two different networks. The first connects processors inside the brain. The second connects different brains with the outside world, and Telcos have a much stronger position in the second.
References:
https://sebastianbarros.substack.com/p/every-brain-needs-a-nervous-system
Verizon to build new, long-haul, high-capacity fiber pathways to connect AWS data centers
Hyper Scale Mega Data Centers: Time is NOW for Fiber Optics to the Compute Server
S&P Global Market Intelligence Surveys: Fiber Deployments in U.S. and Europe + AI Infrastructure Causes Market Shift
Amazon and Corning in Multi-Billion-Dollar Fiber Infrastructure Deal in North Carolina
2026 Fiber Connect Keynote: “The Future of Fiber Optics: AI and the Quantum”
Big Fiber’s $250M financing deal to buildout dark fiber routes for AI Data Center expansion
Oriole Networks photonic networking platform to be integrated with AMD GPUs/CPUs for next-gen AI data center fabrics
London, England based Oriole Networks today announced continued progress in its collaboration with AMD in support of the UK’s Advanced Research & Invention Agency (ARIA) Scaling Inference Lab. The initiative integrates Oriole’s photonic interconnect architecture with AMD Instinct GPUs and AMD EPYC CPUs to evaluate next-generation data center fabrics capable of addressing the performance, latency, and energy constraints inherent in large-scale AI workloads.
The multi-year collaboration is advancing toward deployment of what is positioned as the first production-scale, all-photonic AI network fabric. The system is designed to deliver ultra-low latency and deterministic transport characteristics at the system level, leveraging optical circuit switching to optimize east-west traffic flows across accelerator clusters. The primary objective is to demonstrate how optical interconnect technologies can support large-scale inference and distributed AI processing under stringent performance and energy constraints.
Oriole’s PRISM photonic networking platform [2.] replaces conventional electronic switching in the network core with nanosecond-scale optical circuit switching. In contrast to packet-switched electronic fabrics, this approach is intended to reduce forwarding overhead, lower core power consumption, and improve end-to-end transport efficiency for accelerator-dense workloads. AMD is contributing compute hardware and technical collaboration to support modeling and execution of large-scale network workloads relevant to frontier AI systems. However, PRISM is not built for any single chip vendor. It works across any accelerator platform, giving the wider industry a path to frontier-scale system-wide performance without the need for proprietary stacks.
Note 1. Oriole Networks is a photonic networking company, developing disruptive technologies for AI/ML and HPC networking that will revolutionize data centers. These technologies address AI’s biggest challenges – speed, latency, and sustainability. Our holistic approach replaces energy-hungry electrical switching with photonic switching. By using only light to move data in the network, our solution will increase the efficiency of LLM training and inference to unprecedented levels while dramatically reducing the energy consumption of data centers, currently putting a huge strain on energy grids. We can offer faster, more efficient, and more sustainable AI without sacrificing the planet.
Note 2. Oriole’s PRISM is a fully photonic network system designed to provide port-level, all-to-all connectivity, eliminating the need for electrical switches and dramatically reducing the number of optical transceivers needed in the network. This evolution greatly reduces power consumption and latency, increases bandwidth, and strengthens network resilience by eliminating single points of failure.

Image Credit: Oriole Networks
…………………………………………………………………………………………………………………………………………………………………………………………………………………………………………..
The deployment also represents the first commercial implementation of Oriole’s technology following an R&D-to-production transition completed in approximately three years. The company states that its xPU-agnostic architecture is intended to support heterogeneous accelerator environments and broader industry rollout beginning in 2027.
Photonic networking architecture:
PRISM is designed to route data optically rather than electrically, using photonic circuit paths in place of conventional electronic switching elements. As AI training and inference workloads scale, data center interconnect requirements increasingly exceed the efficiency limits of traditional switch-based architectures, particularly in terms of power dissipation, thermal load, and communication latency.
By eliminating electronic switching in the fabric core, the PRISM architecture seeks to reduce core network power consumption and limit buffering- and queuing-related delay. The use of optical circuit switching is consistent with ongoing industry interest in photonic interconnects, co-packaged optics, and optical disaggregation as potential enablers of high-density AI clusters.
The company reports that the architecture can substantially reduce GPU idle time and improve system-level utilization by shortening data movement paths between compute nodes. It also indicates potential reductions in cooling demand and associated water usage due to lower network power dissipation.
Quotes:
James Regan, CEO of Oriole, said: “A year ago, we were proving the physics; today, we’re proving the business. Our collaboration with AMD has moved from concept to deployment to a system an order of magnitude larger, and the data proves this is already driving performance increases at pace. This is what it looks like when photonic networking stops being a research curiosity and starts being the foundation of how serious AI infrastructure gets built. There’s a big problem now with electrical switches, which are basically bottlenecking AI traffic, and it’s going to get worse. What we do is we replace all the electrical switches.”
“AMD is excited to collaborate with Oriole on the ARIA Scaling Inference Lab cluster,” said Madhu Rangarajan, corporate vice president, Compute and Enterprise AI business, AMD. “Oriole’s AI backend networking with nanosecond optical circuit switching represents a fundamentally different way to connect accelerators at scale. We are helping to validate how photonic fabrics can work alongside AMD compute to deliver the low-latency, high-bandwidth connectivity that AI Inference workloads demand.”
“Meeting the demands for modern AI requires rapidly identifying ways to improve the performance and cost-efficiency of large-scale AI clusters. ARIA is thrilled to collaborate with Oriole and AMD to demonstrate the benefits of this new technology and it’s exactly the type of collaboration, between innovative startups and industry leaders, that the Scaling Inference Lab was designed to foster,” said Suraj Bramhavar, Program Director at ARIA
Standards and interoperability context:
From a standards perspective, photonic AI fabrics remain an active area of industry development rather than a fully mature architectural class. Relevant technical domains include IEEE 802.3 optical Ethernet interfaces, ITU-T optical transport frameworks such as G.694 and G.709, and ecosystem work in optical interconnect and co-packaged optics initiatives.
A vendor-neutral, accelerator-agnostic photonic fabric may be of interest to standards and industry groups evaluating future data center interconnect models for AI and high-performance computing. The Oriole–AMD collaboration therefore provides an early reference point for assessing the operational characteristics, integration constraints, and interoperability implications of optical circuit-switched AI infrastructure.
……………………………………………………………………………………………………………………………………………………………………………………………………………………….
References:
Oriole to Deploy World’s First AI System with Pure Photonic Network to Supercharge Data Centers
https://www.fierce-network.com/cloud/oriole-networks-pushes-pure-photonic-networking-ai-data-centers
NTT’s IOWN is (finally) evolving to an All Photonics Network (APN); Physics based AI for enterprise OT
Goldman Sachs report: Optical Networking is the next mega trend in AI infrastructure
Hyperscaler design of networking equipment with ODM partners
Technavio: Silicon Photonics market estimated to grow at ~25% CAGR from 2024-2028
Amazon and Corning in Multi-Billion-Dollar Fiber Infrastructure Deal in North Carolina
Introduction:
The surge in optical fiber demand is intensifying as hyperscale cloud providers accelerate infrastructure buildouts to support AI-driven workloads and high-density data center interconnect (DCI). Corning [1.] today announced a multi‑billion‑dollar investment from Amazon to expand fiber manufacturing capacity in North Carolina—incremental to its previously announced $10 billion regional cloud infrastructure expansion—reflects a broader structural shift in how optical supply chains are being secured and scaled.
Note 1. Corning’s fiber-optic infrastructure uses highly pure strands of optical glass thinner than a human hair to transmit massive amounts of data as pulses of light. These networks serve as the backbone for modern communications, connecting everything from rural broadband rollouts to hyperscale data centers driving generative AI. In hyperscale cloud and AI data centers, Corning provides high-density optical hardware and cables, such as their GlassWorks AI™ solutions. These large setups feature massive fiber-optic trunk cables containing hundreds to thousands of individual fibers bundled together to link powerful processors and servers. For outdoor networks running underground or on utility poles, you will see ruggedized cables protected by thick jackets and aramid yarn. These cables are designed to withstand weather, crushing, and extreme temperatures.
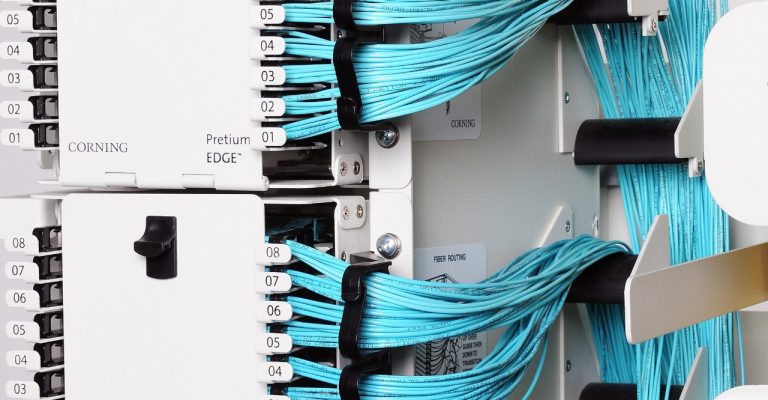
Corning’s structured cable solutions for internal data center connectivity. Image Credit: Corning
…………………………………………………………………………………………………………………………………………………………………………………….
This trend is not isolated. Hyperscalers including Meta, Microsoft, and wireline network operator Lumen are proactively entering long-term supply and co-investment agreements with fiber and cable manufacturers, effectively reshaping the upstream optical ecosystem.
Recent Fiber Supply Agreements with Corning:
-
May 2026: NVIDIA committed $500 million to Corning to support construction of three new optical manufacturing facilities in North Carolina and Texas. This investment is expected to increase Corning’s U.S.-based optical connectivity manufacturing capacity by approximately 10× and expand domestic fiber production by over 50%, targeting AI cluster interconnect requirements characterized by high fiber count and low-latency links aligned with IEEE 802.3 Ethernet and emerging co-packaged optics ecosystems.
-
January 2026: Meta finalized a $6 billion agreement with Corning to secure fiber supply for large-scale data center fabrics. These fabrics increasingly rely on high-fiber-density architectures consistent with leaf-spine topologies and standards such as IEEE 802.3bs/ck (400G/800G Ethernet), as well as parallel single-mode fiber (PSM) and wavelength-division multiplexing (WDM) approaches defined in ITU-T G.694.x.
-
September 2025: Microsoft entered a manufacturing agreement with Corning and Heraeus focused on hollow-core fiber (HCF), a technology aligned with ITU-T G.650 characterization frameworks. HCF offers lower latency (reduced group index) and improved performance for latency-sensitive AI workloads and inter-data center transport.
-
August 2024: Corning and Lumen established a supply agreement for next-generation fiber optic cable to support AI-driven traffic growth. This aligns with ITU-T G.652.D and G.657 fiber standards for bend-insensitive and high-capacity terrestrial deployments, as well as evolving requirements for high-count ribbon fiber cables in dense metro and campus environments.
Structural Implications for the Optical Supply Chain:
Hyperscalers are transitioning from passive consumers of optical components to active participants in manufacturing scale-up, including:
-
Anchor tenancy models: As seen with Meta’s backing of Corning’s North Carolina facility, hyperscalers are underwriting capacity expansion, effectively securing preferential access to supply.
-
Vertical influence: Direct investments and long-term offtake agreements allow hyperscalers to influence fiber specifications, manufacturing roadmaps, and deployment architectures (e.g., optimized fiber types for short-reach vs. long-haul DCI).
-
Workforce development: Amazon and Corning’s collaboration with Catawba Valley Community College to expand fiber technician training reflects a strategic effort to address labor constraints in optical manufacturing and deployment, reinforcing domestic supply chain resilience.
Implications for Telecom Operators:
These developments introduce non-trivial risks and strategic considerations for telecom operators:
-
Supply prioritization: Hyperscaler-backed agreements may shift allocation dynamics, potentially constraining availability for traditional telecom buyers during periods of tight supply.
-
Pricing pressure: Long-term, high-volume contracts could influence pricing benchmarks, potentially disadvantaging operators without comparable scale or capital flexibility.
-
BEAD timing mismatch: U.S. operators anticipating fiber expansion funded by BEAD (Broadband Equity, Access, and Deployment) may face supply bottlenecks if hyperscaler demand absorbs near-term manufacturing output.
-
Architectural divergence: Hyperscaler-driven requirements—optimized for short-reach, ultra-high-capacity intra-data-center and DCI links—may skew innovation toward their use cases, potentially misaligning with traditional access network needs governed by ITU-T G.984 (GPON), G.9807 (XGS-PON), and emerging 25G/50G PON standards.
A useful analogy is the semiconductor industry, where hyperscaler influence has already reshaped foundry capacity allocation and advanced node prioritization. A similar dynamic is now emerging in optical fiber and connectivity, with hyperscalers effectively acting as quasi-industrial planners for next-generation optical infrastructure.
Quotes:
“Amazon’s investments in North Carolina have created more than 26,000 jobs across the state. This multibillion-dollar agreement with Corning continues that commitment, channeling investment into American manufacturing and creating 1,000 new jobs at their facilities near our data centers,” said Matt Garman, CEO of AWS. “We’re also partnering to train North Carolinians for highly skilled roles in fiber optics and fusion splicing. These long-term investments create long-term careers and real opportunity in the communities where we operate.”
“This agreement with Amazon represents a significant milestone for Corning and for American manufacturing,” said Wendell Weeks, chairman, CEO, and president of Corning. “For 175 years, Corning has pioneered the technologies that connect people and transform industries. Amazon’s investment will help us expand production, create 1,000 new advanced manufacturing jobs at our facilities, and lead the way toward building a resilient U.S. manufacturing base.”
Clearfield CEO Cheri Beranek told Fierce Network at Fiber Connect that supply chain issues are re-emerging, particularly around high-count fiber. “There’s absolutely a shortage of ribbon fiber,” she said, referring to a conversation with Hawaii Telecom, a Clearfield customer. “The high count for the ribbon fiber … everything over 432 is tough to get,” she said. “The fiber companies want to tell you that there’s enough American‑made fiber… but there can’t be.”
“In talking to fiber optic suppliers, they all say one thing, ‘It’s nice to finally be the cool kid on the block.’ Hyperscalers are finally realizing that they not only need compute, storage, chips, power, water and real estate, they also need fiber optic connectivity,” said Fierce Network’s Chief Analyst Linda Hardesty.
The net effect is a tightening coupling between AI infrastructure demand and optical supply chain strategy—one that telecom operators will need to actively manage through procurement strategy, vendor diversification, and potentially deeper participation in supply-side partnerships.
End Note:
Amazon’s long-term commitment to North Carolina goes beyond direct investments and jobs created in the state. Through workforce development, Career Choice, and upskilling programs, Amazon has already provided practical training for nearly 7,000 people in North Carolina, helping to open new pathways for higher-paying jobs and fulfilling careers.
In the last decade, Amazon has contributed more than $72 million to charities and organizations supporting local needs across North Carolina, with $10 million provided in 2025 alone to 26 local community partners. This includes contributions like $1.5 million to enhance public safety services for southeastern Hamlet and surrounding Richmond County communities by funding a new fire substation that is expected to lower emergency response times and homeowner insurance premiums.
References:
https://www.corning.com/data-center/au/en/home/applications/enterprise-private-data-center.html
https://www.aboutamazon.com/news/company-news/amazon-corning-fiber-optics-1000-jobs-north-carolina
Fiber Optic Boost: Corning and Meta in multiyear $6 billion deal to accelerate U.S data center buildout
Corning to Build New Fiber Optic Plant in Phoenix, AZ for AT&T Fiber Network Expansion
Calix and Corning Weigh In: When Will Broadband Wireline Spending Increase?
Verizon-Corning $1.05B fiber deal part of larger build-out or buy program
Goldman Sachs report: Optical Networking is the next mega trend in AI infrastructure
Goldman Sachs analysts forecast a $154billion opportunity in optical networking driven by skyrocketing capacity demands from hyperscale cloud and AI workloads. Carriers and vendors are integrating 10GbE edge networking and AI-RAN (Artificial Intelligence Radio Access Network) trials on live 5G networks.
Goldman argues that AI infrastructure is creating a networking bottleneck phase, where optical interconnects become essential to connect more chips, keep latency low, and let AI clusters scale efficiently. The total optical networking market forecast 9x increase to $154 billion is due to both scale-up and scale-out AI data center architectures grow.
AI compute gains are no longer just about faster GPU and HBM chips; they depend on moving data fast enough between chips, racks, and super-nodes. Goldman Sachs emphasizes that networking now “unlocks computing capability” by enabling seamless exchange across multiple AI chips, which is exactly where copper-based links start to fall short. That makes fiber-optic connectivity, pluggable optics, and co-packaged optics central to the next phase of AI build-out. The report splits opportunity across scale-up and scale-out networking, plus component categories such as copper cables, pluggable optical modules, CPO, and PCB midplanes.
External coverage of this report says Goldman Sachs sees scale-up as the larger pool, about $106 billion or 69% of the $154 billion TAM, while CPO could represent about $91 billion or 59% of the total, assuming 29% penetration in scale-out networking. In practical terms, the report is signaling that the highest-value optical opportunity sits inside tightly coupled AI systems, not just in long-haul or metro transport.
………………………………………………………………………………………………………………………………………………………………………………………….
Goldman projects the following:
- Dollar content increase by 16x / 45x in Scale Out / Scale Up per computing unit from GB300 NVL72 (per computing unit means 72 GPUs per rack to reach NVL72) to Rubin Ultra NVL576 (per computing unit means 72 GPUs per rack, and 8 racks together to reach NVL576), with opportunities across pluggable optical modules, optical engines in CPO, copper cables, and PCB midplanes.
- A 13x larger addressable market for optical modules / optical engines expanding from scale out (e.g. GB300 NVL72) to scale up (e.g. Nvidia Rubin Ultra [1.] NVL576 level 2 scale up via CPO) per computing unit. n
- A 10x larger value market for pluggable optical modules in scale out per computing unit from GB300 NVL72 to Rubin Ultra NVL576, even with a 29% CPO penetration rate. The numbers of pluggable optical module (1.6T equivalent) per computing unit would increase from 216 units in GB300 NVL72 to 2.5k units in Rubin Ultra NVL576.
Note 1. Nvidia Rubin Ultra is a flagship, next-generation AI and high-performance computing (HPC) processor succeeding the standard Rubin architecture. Scheduled to debut in late 2027, it utilizes massive multi-die chiplet designs and unprecedented memory configurations to power the next wave of generative and agentic AI.
………………………………………………………………………………………………………………………………………………………………………….
Market Forecasts:
The investment bank expects the aggregate dollar content per computing unit across scale up and scale out to increase by 29x from US$315k in GB300 NVL72 to US$9.4bn in Rubin Ultra NVL576, and assuming the numbers of racks through the full product cycle are 48k racks for GB300 NVL72, and 16.5k computing units for Rubin Ultra NVL576, the aggregate value TAM across scale up and scale out would increase by 9x from US$15bn in GB300 NVL72 (mainly in 2026) to US$154bn in Rubin Ultra NVL576 (mainly in 2028).
Among the US$154bn value TAM, 69% goes to scale up, or US$106bn, and CPO contributes US$91bn, or 59% of the US$154bn value TAM, assuming CPO at 29% penetration rate in scale out.
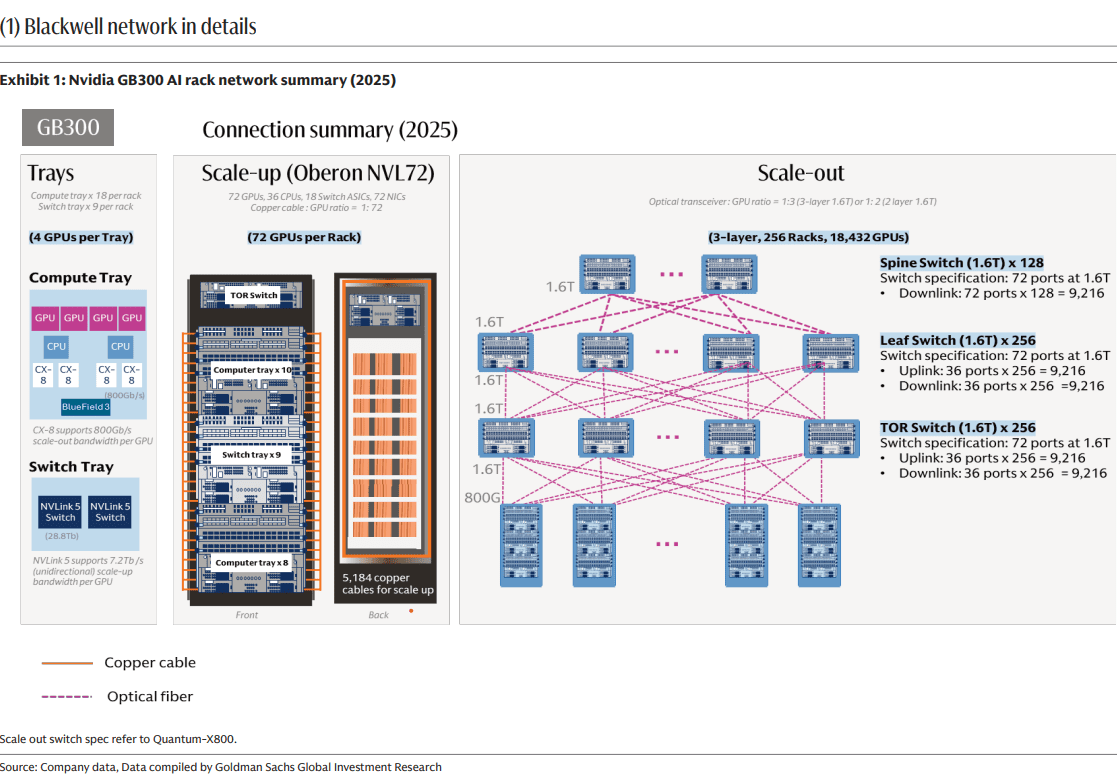
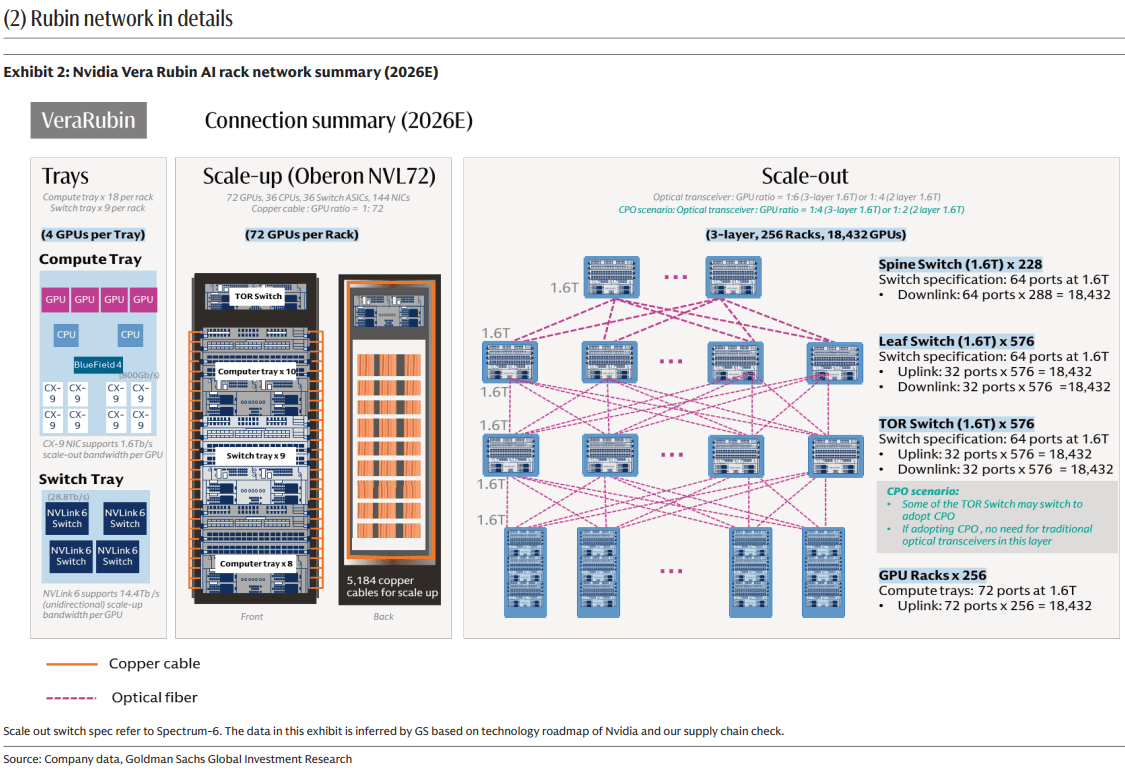
For network architects, the important takeaway is that AI clusters are becoming optics-heavy at more layers of the network stack, not just at the edge of the rack. The likely winners are suppliers that can reduce power, improve density, and simplify packaging for very high-bandwidth links, especially around CPO and advanced pluggables. This is less a story about traditional telecom optics and more about datacenter interconnects optimized for GPU fabrics and AI training/inference throughput.
The most consistently cited “top beneficiaries” are Coherent, Lumentum, and Fabrinet. These companies sit close to the core optical component modules and manufacturing layers that scale with higher AI interconnect demand. That makes them the most straightforward proxies for the forecasted optics expansion. The report’s thesis favors companies with strong exposure to high-end optical transport, coherent optics, and data-center interconnect rather than the broader optical networking/PON equipment companies like Ciena, Nokia/Infinera, Cisco/Acacia, ADVA, or Calix.
Conclusions:
Strategically, Goldman Sachs maintains that optical networking is no longer a niche enabling layer; it is becoming a core enabler of AI capex scaling. That shifts investor attention toward optical component vendors, silicon photonics, transceiver suppliers, and adjacent packaging ecosystems. The report’s core message is simple: as AI clusters grow, the network fabric becomes a first-order constraint, and optics are the most likely answer.
References:
2026 Fiber Connect Keynote: “The Future of Fiber Optics: AI and the Quantum”
How will fiber and equipment vendors meet the increased demand for fiber optics in 2026 due to AI data center buildouts?
Big Fiber’s $250M financing deal to buildout dark fiber routes for AI Data Center expansion
Analysis: Fiber Broadband Association (FBA) whitepaper: Upgrading MSO Networks to Fiber to the Home (FTTH): A Technical Perspective
Fiber Optic Boost: Corning and Meta in multiyear $6 billion deal to accelerate U.S data center buildout
Fiber Optic Networks & Subsea Cable Systems as the foundation for AI and Cloud services
AI infrastructure investments drive demand for Ciena’s products including 800G coherent optics
DriveNets and Ciena Complete Joint Testing of 400G ZR/ZR+ optics for Network Cloud Platform
2026 Fiber Connect Keynote: “The Future of Fiber Optics: AI and the Quantum”
Dr. Michio Kaku’s 2026 Fiber Connect keynote, “The Future of Fiber Optics: AI and the Quantum,” kicked off the inaugural AI & Emerging Technology Infrastructure Summit on Wednesday, May 20,2026.

As a theoretical physicist and futurist, Dr. Kaku delivered a high-altitude roadmap framing fiber optic networks not merely as faster telecom pipes, but as the mandatory foundation for a world defined by concurrent, multi-cloud AI infrastructure and quantum mechanics.
Kaku described the convergence of AI, quantum computing, and fiber infrastructure as a critical shift toward an AI-native, quantum-enabled internet essential for national competitiveness. Kaku emphasized that fiber optics are necessary to facilitate “quantum AI” by handling high-density, low-latency data movement, moving beyond traditional networking to support exponential computing advancements.
Key Takeaways:
- Fiber as the Foundation for AI: Dr. Kaku explained that massive data sets and hyperscale AI computations cannot run efficiently over wireless or legacy networks. Fiber’s near-limitless bandwidth and sub-millisecond latency are required to process these workloads in real-time.
- The Quantum Computing Leap: He detailed how quantum networks—which compute at the atomic level—will redefine security and processing power. He emphasized that quantum data requires the stability, security, and bandwidth that only fiber optics can provide.
- National Competitiveness: Dr. Kaku framed fiber broadband as a strategic national asset. He argued that a region’s ability to evolve into an AI-native economy depends directly on robust fiber infrastructure to secure future healthcare, financial, and climate innovations.
- The “Thinking Economy”: He projected that networks are evolving to do more than just transport data. They will increasingly support “thinking economies” where intelligence moves instantly between edge computing centers, end-points, and the cloud.
The presentation and subsequent fireside chat with quantum computing firm IonQ offered several critical technological dimensions and actionable industry analysis:
The Physics of the “AI Triad” (Compute, Quantum, & Photonics):
Kaku mapped out how classical silicon-based computing is approaching its physical limits (thermodynamics and transistor gating). He explained that the future relies on a three-pronged convergence:
-
- AI Models: The brain processing the logic.
- Quantum Computing: The hyper-accelerator solving atomic, chemical, and multi-variable optimization issues.
- Optical Fiber: The unified nervous system. Quantum and distributed AI workloads cannot scale on traditional copper networks because they require absolute determinism, zero-jitter latency, and near-limitless bandwidth.
Upgrading to a Quantum-Ready Internet:
Drawing from themes in his book Quantum Supremacy, Kaku noted that the move toward a quantum-enabled web alters the physical network topology. Operators must plan for physical security layers (like Quantum Key Distribution) and data transmission methods that preserve quantum entanglement across distances.
–>Fiber is the only media capable of transporting light photons over vast geographies without disrupting these states.
The Power and Cooling Crisis:
A significant focus of the analysis was the staggering energy footprint of next-generation AI factories and hyper-scale data centers. Kaku noted that moving data electronically creates heat resistance. Shifting toward all-optical (photonic) networks and in-rack fiber interconnects removes electronic bottlenecks, drastically reducing the power required to pass massive datasets between distributed data centers
Strategic Implications for Network Operators:
During the fireside chat, the discussion moved from theoretical physics to immediate business strategy and tactics:
-
- National Competitiveness: Bandwidth, latency, and optical infrastructure are the new benchmarks for a country’s economic power.
- Capacity Planning: Network planners must shift from estimating consumer download speeds to calculating the throughput required for real-time, stateful AI agents and machine learning inference workloads operating at the network edge.
FBA Panel and Summit Sessions:
Following Kaku’s opening address, the Fiber Broadband Association (FBA) hosted deep-dive industry panels that put these physics concepts into operator terms:
- The Open Compute Project (OCP): Discussed open-source hardware standards for in-rack photonics to support massive AI clustering.
- Multi-Data-Center Architectures: Network engineers mapped out how dense dark fiber rings are being laid to link secondary edge facilities, allowing enterprises to run heavy inference closer to end-users without overwhelming backbone networks.
- AI data center speed and power requirements are transitioning towards 800 Gbps–1.6 Tbps node-to-node networking and gigawatt-scale power to handle distributed generative AI workloads.
- High rack densities up to 240 kW require advanced liquid or immersion cooling, with optical technologies being introduced to reduce heat generation.
…………………………………………………………………………………………………………………………………..
References:
https://fiberconnect.fiberbroadband.org/about/whats-new/
Analysis: Fiber Broadband Association (FBA) whitepaper: Upgrading MSO Networks to Fiber to the Home (FTTH): A Technical Perspective
Fiber Broadband Association Middle Mile WG: how to use “Digital Infrastructure Networks” for coordinated fiber backbone investments
Analysis: AT&T 1Q-2026 results: increased fiber penetration, FWA momentum, D2D deals, and mobile/home internet bundles
Fiber Optic Boost: Corning and Meta in multiyear $6 billion deal to accelerate U.S data center buildout
Fiber Optic Networks & Subsea Cable Systems as the foundation for AI and Cloud services
How will fiber and equipment vendors meet the increased demand for fiber optics in 2026 due to AI data center buildouts?
Automating Fiber Testing in the Last Mile: An Experiment from the Field
AI wireless and fiber optic network technologies; IMT 2030 “native AI” concept
Analysis: Nokia’s strong growth in Optical Networks and AI network infrastructure
Executive Summary:
While Nokia’s first-quarter profitability improved across all reported metrics, year-over-year comparisons were significantly affected by a €120 million ($140 million) non-recurring charge recorded in the Mobile Networks business in the prior-year period. On a comparable basis, net profit increased 93% to approximately €295 million ($345 million). Despite ongoing cost restructuring initiatives, the company’s comparable operating margin remained at 6.2%, well below the ~11% levels observed in the corresponding quarters of 2021 and 2022, indicating continued margin compression relative to earlier cycle peaks.
Optical networking has emerged as Nokia’s primary growth engine, significantly outpacing the company’s overall performance. At the group level, Nokia reported first-quarter comparable revenue growth of 3% year-over-year (4% in constant currency) to €4.5 billion ($5.3 billion). The acquisition of Infinera, which was completed in March last year, surely helped. As did massive investments by AI data center companies because Nokia’s optical gear is used for both intra and inter data center connectivity.
The company said Thursday that first-quarter sales of optical network infrastructure rose 12% on year, driven by demand from AI and cloud customers in the Americas. It booked 1 billion euros ($1.17 billion) of orders from AI & Cloud customers in the quarter and now sees overall sales in the network infrastructure business growing 12%-14% this year, having previously expected 6%-8%. The company had previously announced it was investing in additional manufacturing capacity to support growth and maximize the opportunity in this accelerating market.
When Nokia held its capital markets day last November, the company expecting hyperscalers to invest about $540 billion in total capital expenditure this year. That number has now been raised to more than $700 billion, Nokia CEO Justin Hotard told reporters. As part of that flows into Nokia’s order book, first-quarter optical sales grew 56% year-over-year, to €821 million (US$959 million).
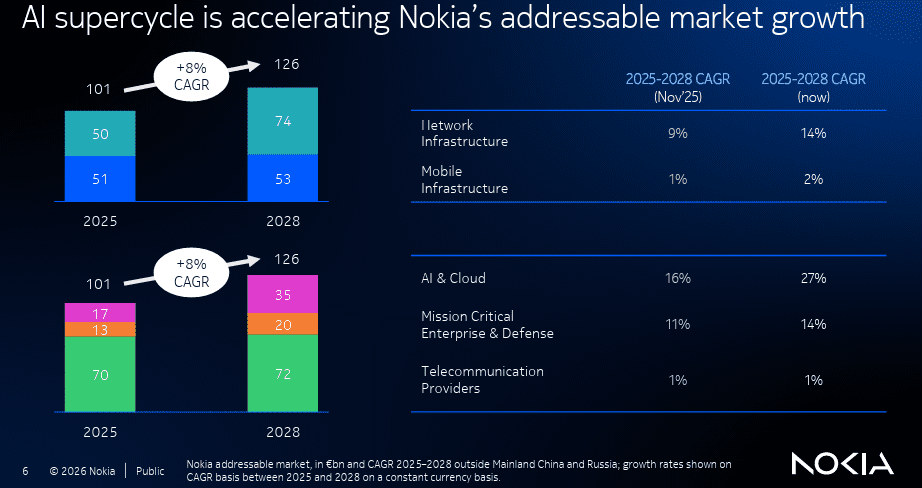
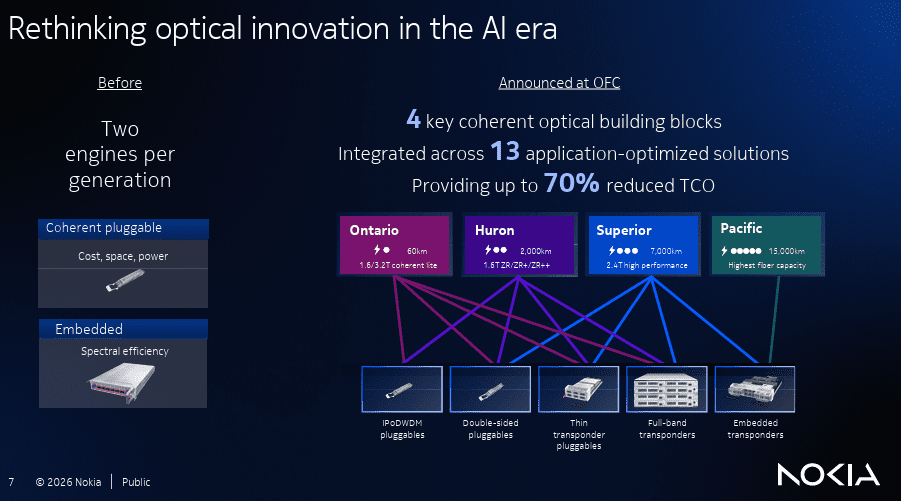
Image Credits: NOKIA
……………………………………………………………………………………………………………………………………………………………………………………………………….
Performance across segments remains uneven. Key drags included the fixed broadband segment within Network Infrastructure (NI)—which also encompasses optical—as well as the Mobile Networks (MN) radio access business. Despite these headwinds, CEO Justin Hotard is positioning NI, particularly its optical and IP routing units, as the core drivers of near-term growth. The company has raised its full-year NI growth outlook to 12–14%, up from the 6–8% range communicated in January, reflecting stronger momentum in high-capacity transport and IP networking demand.
Nokia is also guiding for full-year comparable operating profit in the range of €2.0–2.5 billion ($2.3–2.9 billion). At the midpoint, this would represent approximately 11% year-over-year growth relative to 2025, indicating improving operational leverage as higher-growth segments scale. The strongest momentum remains in optical and IP networking, while the legacy radio access business is still working through margin pressure, mix shifts, and the higher capital intensity of next-generation RAN evolution.
Within this context, the Mobile Infrastructure (MI) segment remains the principal source of performance uncertainty. Following internal reorganization, the “radio networks” unit—comprising the majority of the former Mobile Networks business—accounts for 63% of MI revenue. While constant-currency performance was broadly stable, reported radio networks revenue declined 5% year-over-year to €1.58 billion ($1.85 billion), contributing to a 3% decline in total MI revenue to approximately €2.5 billion.
Segment-level profitability metrics require careful normalization. MI reported operating profit of €222 million ($259 million), representing a 68% year-over-year increase. However, adjusting for the absence of the prior-year €120 million charge, operating profit would have declined by approximately 12%. On a normalized basis, operating margin would have decreased from ~9.8% to ~8.9%, rather than increasing from the reported 5.1%, indicating underlying margin pressure in the radio access portfolio.
Additional analytical complexity arises from the inclusion of Nokia Technologies within MI reporting. This licensing-driven business has historically exhibited operating margins exceeding 70%. Assuming a comparable margin profile in the current quarter, its implied operating contribution (~€270 million / $316 million) exceeds the total reported MI operating profit. This suggests that the combined radio networks and associated software activities may be operating at or near breakeven when disaggregated from licensing revenues, highlighting the importance of segment-level transparency in assessing the underlying economic performance of Nokia’s RAN portfolio.
A restructuring program, initiated under Pekka Lundmark and continued by CEO Justin Hotard, is designed to deliver approximately €1.2 billion ($1.4 billion) in annualized cost savings by the end of 2026. This is primarily driven by a planned reduction of approximately 14,000 positions from a September 2023 baseline of ~84,000 employees (excluding subsequently divested businesses). As of year-end 2025, Nokia reported 74,100 employees, excluding Infinera, implying that the majority of targeted reductions have been completed and that approximately 4,000 additional reductions remain. Management has indicated that future efficiency gains are expected to be incremental rather than driven by further large-scale restructuring.
…………………………………………………………………………………………………………………………………………………………………………………………
Analysis:
From a systems perspective, the key signal is that transport and aggregation layers are gaining strategic weight relative to the traditional macro-RAN hardware layer. Optical growth reflects the continued densification of metro and backbone networks, driven by higher east-west traffic, AI and cloud interconnect demand, and the need for lower-latency transport to support distributed radio and edge workloads. That makes optical and IP less of a “supporting cast” and more of the enabling fabric for cloudified telecom architectures.
The RAN market is moving toward software-defined, cloud-native, and increasingly AI-assisted architectures, which raises the bar for vendor differentiation. Nokia has been emphasizing AI-RAN and anyRAN work with NVIDIA and operators including BT, NTT Docomo, T-Mobile, and others, positioning itself around AI-for-RAN, AI-on-RAN, and AI-and-RAN use cases. Architecturally, this suggests the company is trying to move beyond a pure radio-box supplier model toward a compute-centric platform strategy tied to 5G-Advanced and AI-native 6G.
This transition intensifies competition with vendors pursuing virtualized RAN, Open RAN, and multi-vendor disaggregation strategies. In that environment, the critical battleground shifts from integrated proprietary base stations to software portability, orchestration, open interfaces, cloud infrastructure integration, and accelerator support. For Nokia, the commercial challenge is that the economics of vRAN and AI-RAN depend not only on technical readiness, but also on whether operators can justify new compute and orchestration layers without eroding total cost of ownership.
The broader networking trend is convergence between mobile, optical, IP, and cloud infrastructure. The same traffic growth that pressures RAN capacity also increases demand for optical transport, IP routing, and security-aware automation across the transport and service layers. In that sense, Nokia’s segment mix highlights a wider industry direction: radio access is becoming only one part of a larger distributed compute and transport system, rather than the dominant center of gravity.
In conclusion, Nokia is benefiting as telecom architecture is becoming more horizontal and software-driven, while still facing friction in the vertically integrated legacy RAN model. Optical and IP are scaling nicely with increased high speed data center traffic; RAN is being redefined by cloud (vRAN), AI, and disaggregation; and the vendor that can best align silicon, software, orchestration, and transport will be better positioned for 5G-Advanced and early 6G/IMT 2030 transitions.
…………………………………………………………………………………………………………………………………………………………………………………………
References:
https://www.nokia.com/about-us/investors/results-reports/
Nokia in major pivot from traditional telecom to AI, cloud infrastructure, data center networking and 6G
Nokia’s AI Applications Study: “Physical AI” may require RAN redesign to support high‑volume, low‑latency uplink traffic
Nokia to showcase agentic AI network slicing; Ericsson partners with Ookla to measure 5G network slicing performance
Australia’s NBN and Nokia demonstrate multi-generation optical technologies concurrently over existing FTTP infrastructure
China’s telecom industry rapid growth in 2025 eludes Nokia and Ericsson as sales collapse
Dell’Oro: Analysis of the Nokia-NVIDIA-partnership on AI RAN
Indosat Ooredoo Hutchison, Nokia and Nvidia AI-RAN research center in Indonesia amongst telco skepticism
Nokia Bell Labs and KDDI Research partner for 6G energy efficiency and network resiliency
Fiber Broadband Association Middle Mile WG: how to use “Digital Infrastructure Networks” for coordinated fiber backbone investments
The Fiber Broadband Association (FBA) today released guidance from its Middle Mile Working Group (WG) which outlines how states can strengthen digital infrastructure through coordinated fiber backbone investment. Fiber is the foundation of AI, powering the high-capacity, low-latency, secure connectivity that links data centers, cloud infrastructure, and the communities that depend on them. To meet rising national demand, the U.S. must scale fiber deployment 2.3x by 2029. This goal requires accelerated infrastructure builds and strong coordination among states, utilities, and industry partners.
Digital Infrastructure Networks are strategic fiber optic systems that connect the core internet backbone to last-mile broadband providers. By strengthening these middle-mile connections, states can reduce the cost of broadband deployment, improve network resiliency, and expand connectivity to unserved and underserved communities.
“Middle-mile infrastructure is what allows broadband networks to scale,” said Sachin Gupta, Chair of the Middle Mile Working Group and Vice President of Business and Technology Strategies at Centranet. “When high-capacity fiber backbones are located closer to underserved communities, providers can extend last-mile networks more affordably, reach more locations, operate more efficiently, and better serve communities across the state.”
Among the recommendations:
- Coordinate infrastructure projects across agencies to streamline deployment and reduce unnecessary construction
- Implement “dig once” policies that install conduit or fiber whenever roads or utility corridors are opened for construction
- Leverage state-owned assets, including rights-of-way, existing fiber routes, and utility infrastructure
- Modernize permitting and coordination processes to accelerate broadband builds
FBA will further explore these strategies during two Middle Mile Working Group breakout sessions at Fiber Connect 2026, taking place Tuesday morning. The sessions include:
- Rural Collaboration, Infrastructure Planning, and Sustaining Affordable, High-Performance Middle Mile Broadband
- Unlocking New Middle Mile Opportunities for ISPs and Community Networks
……………………………………………………………………………………………………………………………………………………………………………………………………………………………………
Technical Topology: The DWDM Advantage:
- Massive Spectral Efficiency: Multiplexing up to 96+ channels onto a single fiber, with each wavelength supporting 100G, 400G, or 800G data rates.
- Scalable Architecture: Capacity can be increased incrementally by lighting new wavelengths without forklift upgrades or additional trenching.
- Resilient Topologies:
- Ring Networks: Often preferred for regional backhaul, utilizing Optical Add/Drop Multiplexers (OADMs) to provide self-healing 1+1 protection and sub-50ms failover.
- Mesh Networks: The gold standard for reliability, offering multiple diverse paths to ensure uptime even during multiple fiber cuts.
- Long-Haul Performance: Utilizing Erbium-Doped Fiber Amplifiers (EDFAs) and Raman amplification to maintain signal integrity over spans exceeding 1,000 km without electronic regeneration.


References:
Learn more; fiberconnect.fiberbroadband.org. Learn more about FBA’s research here or subscribe to FBA’s Fiber Forward Weekly newsletter here to stay updated.
Digital Infrastructure Networks: Meeting the Broadband Challenge for State Governments
Australia’s NBN and Nokia demonstrate multi-generation optical technologies concurrently over existing FTTP infrastructure
Automating Fiber Testing in the Last Mile: An Experiment from the Field
U.S. fiber rollouts now pass ~52% of homes and businesses but are still far behind HFC
Highlights of FiberConnect 2024: PON-related products dominate
Fiber Broadband Association: 1.4M Fiber Miles Needed for 5G in Top 25 U.S. Metros
AT&T expands its fiber-optic network amid slowdown in mobile subscriber growth
Australia’s NBN and Nokia demonstrate multi-generation optical technologies concurrently over existing FTTP infrastructure
NBN Co, in collaboration with Nokia, has successfully conducted a laboratory demonstration of multiple generations of optical access and coherent transmission technologies operating concurrently over its existing Fiber‑to‑the‑Premises (FTTP) network. The technical trial validates the long‑term scalability of NBN Co’s national full‑fibre infrastructure and its capacity to accommodate the sustained growth of residential, enterprise, and industrial data demand anticipated over the coming decades.
The “Supercharging Fibre” trial, presented at the Broadband Forum Spring Member Meeting—held in Australia for the first time and hosted by NBN Co—demonstrated aggregate transmission rates exceeding 230 Gbit/s using multiple optical technologies over a single physical fiber link in a controlled laboratory environment. The experimental setup also established a pathway toward achieving terabit‑class capacities in future trials through the evolution of optical modulation formats and channel aggregation techniques.
A key outcome of the trial was the successful integration of coherent optical transmission with multiple generations of passive optical network (PON) technologies—GPON, XGS‑PON, and 50G‑PON—operating simultaneously over the same fiber infrastructure currently in service across Australia. Coherent optics, traditionally deployed within metropolitan, core, and data center interconnect networks, employ advanced modulation and digital signal processing to deliver extended reach, low latency, and high spectral efficiency. Their introduction into the access network domain represents a significant step toward the convergence of access and transport technologies, offering an efficient route to enhanced capacity and service flexibility without extensive physical network replacement.
The demonstration (see illustration below) underscores the technical viability of leveraging existing passive optical infrastructure to support future bandwidth requirements driven by the proliferation of cloud computing, immersive digital experiences, artificial intelligence applications, and industrial IoT systems. The results further illustrate the potential of FTTP systems to evolve into a highly scalable, future‑ready broadband platform capable of sustaining national connectivity objectives.
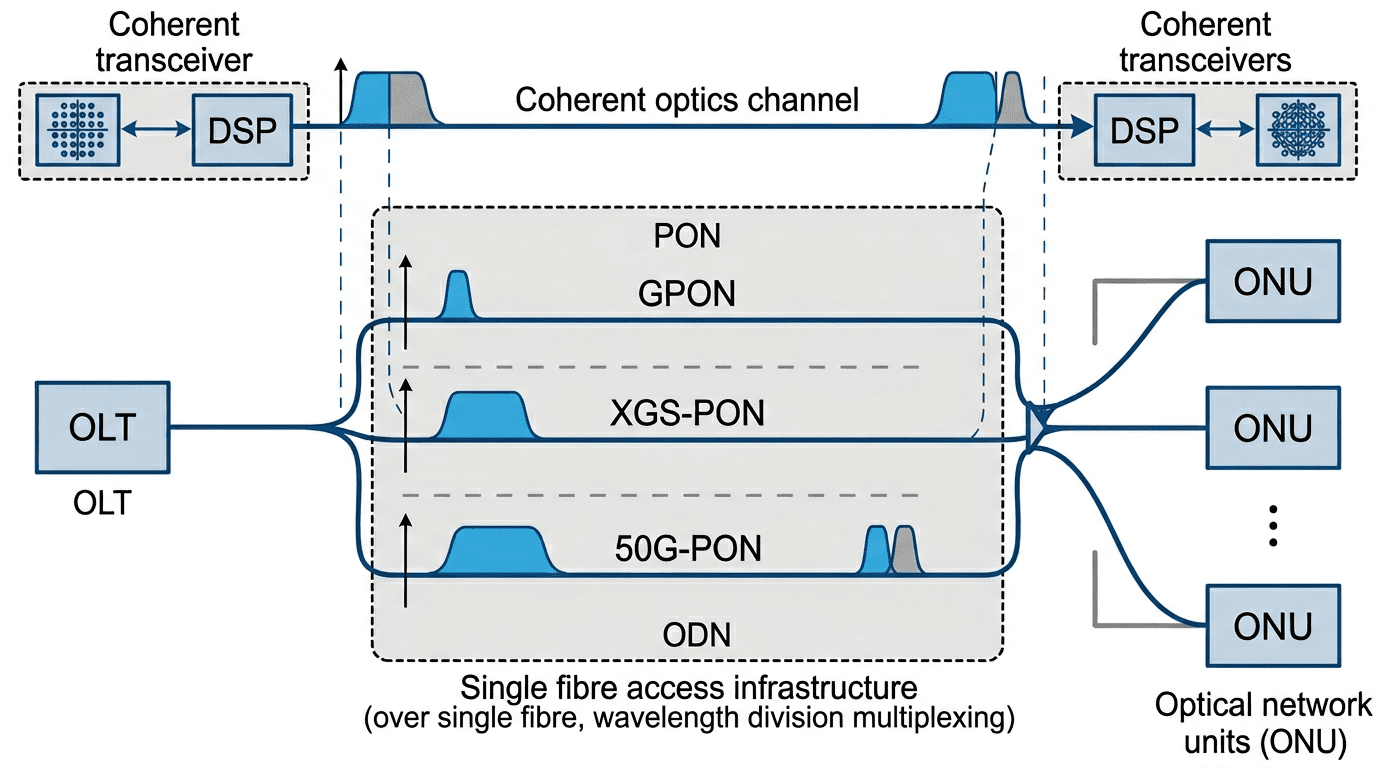
Image Credit: Perplexity.ai
…………………………………………………………………………………………………………………………………………………………………………………………………………………………………………..
By 31 December 2025, more than 1 million customers had transitioned from copper‑based services to high‑speed full‑fiber connections, positioning FTTP as NBN Co’s dominant fixed‑line technology at approximately 35% of total connections. The company achieved its commitment to enable 10 million premises, representing about 90% of the NBN fixed‑line footprint, to order multi‑gigabit‑capable wholesale broadband services. Ongoing upgrade activities encompass over 228,000 premises, as part of an initiative to extend full‑fiber access to 95% of the remaining ~622,000 copper‑served locations by 2030.
These developments reflect NBN Co’s strategic focus on access network modernization and underscore the continuing evolution of optical access technologies toward achieving the performance, flexibility, and resilience required to support Australia’s transition to a digital and cloud‑centric economy.

NBN Co. was established in 2009 by the Commonwealth of Australia as a Government Business Enterprise (GBE) with a clear direction – to design, build and operate a wholesale broadband access network for Australia.
And we’ve done just that – creating a network that criss-crosses a country, and allowing internet retailers to provide reasonably priced broadband services to consumers and businesses.
The network is the digital backbone of Australia and is constantly evolving to keep communities and businesses connected and our nation productive.
References:
https://www.nbnco.com.au/corporate-information/about-nbn-co
https://www.broadband-forum.org/events/spring-2026-member-meeting/
Dell’Oro: Optical Transport Systems market +15% year-over-year in 3Q2025 driven by Cloud Service Providers
AI wireless and fiber optic network technologies; IMT 2030 “native AI” concept
Point Topic: FTTP broadband subs to reach 1.12bn by 2030 in 29 largest markets
Nokia and Hong Kong Broadband Network Ltd deploy 25G PON
Nokia’s launches symmetrical 25G PON modem
Google Fiber planning 20 Gig symmetrical service via Nokia’s 25G-PON system