Private 5G
Nokia’s ECE Divestiture: Impact on Private 5G Market & Disaggregation
Executive Summary:
On October 13th, Nokia said it will sell its Enterprise Campus Edge (ECE) business to AURELIUS, a private-equity investor focused on corporate carve-outs. The planned transaction is expected to close in the first half of 2027, subject to customary closing conditions. Financial terms were not disclosed.
ECE is a substantial part of Nokia’s enterprise private-wireless franchise. Its portfolio spans private LTE and 5G networking through the Digital Automation Cloud, industrial edge and micro-edge computing, industrial devices, and software applications for AI-enabled industrial use cases.
Nokia’s ECE business serves nearly 900 enterprise customers in manufacturing, mining, logistics, airports, ports, and power generation. Its digitalization platform connects industrial assets and processes operational-technology (OT) data on premises, positioning data security, sovereignty, automation, worker safety, and sustainability as core value propositions. The unit reportedly employs about 1,000 people and generates more than €170 million in annual revenue, yet Nokia concluded that its enterprise-campus economics did not fit its post-restructuring priorities in fixed networks, mobile infrastructure, defense, data centers, and AI.
Strategic Rationale:
For Nokia, the sale is consistent with its stated objective of concentrating capital and resources on businesses where it believes it can achieve the greatest long-term differentiation and value creation. Nokia Chief Corporate Development Officer Konstanty Owczarek characterized the divestment as portfolio sharpening, while emphasizing continuity for ECE customers and employees during the transition.
For AURELIUS, the attraction is a globally deployed private-5G and industrial-edge platform with an established enterprise customer base, including Fortune 500 accounts. Fabian Steger, Managing Director of AURELIUS Funds IV and V, said the firm sees scope to expand ECE’s position in private 5G and industrial edge, particularly in AI-powered industrial automation.
Operational implications:
ECE will operate as a standalone company under AURELIUS ownership. Nokia said ECE employees are expected to transfer with the business at closing, in accordance with applicable local employment processes, and that the two companies will cooperate to preserve customer and employee continuity.
The carve-out removes a business with meaningful enterprise exposure from Nokia’s portfolio, but it does not signal an exit from enterprise connectivity altogether. Rather, it reflects Nokia’s broader restructuring under CEO Justin Hotard: prioritizing fixed and mobile network infrastructure, defense, and AI-oriented network opportunities, while shedding or reviewing non-core units.
Nokia’s earlier strategic review encompassed ECE alongside FWA CPE, site implementation and outside plant, and microwave radio units—businesses that collectively generated approximately €900 million in revenue and a €100 million operating loss over the preceding 12 months.
Why It Matters:
The transaction underscores a widening split in the private-networks market between diversified infrastructure vendors and specialist operators focused on industrial digitalization. ECE’s on-premises OT edge, private 5G, and industrial AI software assets give AURELIUS a platform positioned for manufacturing automation, mission-critical campus connectivity, and sovereign data processing.
For Nokia, the deal further advances its pivot toward network infrastructure aligned with AI-driven traffic growth, data-center interconnect, optical and IP networking, and defense communications. The company has set a target of raising annual operating profit to €2.7 billion–€3.2 billion by 2028, from €2 billion in 2024.
Private 4G/5G Market Assessment:
Private cellular remains a real and growing market: industry estimates cited by TelecomTV value 4G/5G private networks at about $4 billion in 2025, rising to $7.2 billion by 2028, while Berg Insight projects growth from $2.4 billion in 2025 to $12 billion by 2030. The issue is not demand for deterministic, licensed-spectrum industrial connectivity; it is the cost and complexity of selling, integrating, and supporting highly customized campus networks at scale.
Nokia’s move therefore removes a major end-to-end competitor from the broad enterprise campus segment, but not from private wireless altogether. Nokia says it will continue selling radios for private deployments with Nokia and third-party cores, while retaining mission-critical capabilities in defense, rail, and utility-grid communications.
Market Impact:
The deal should intensify competition among vendors that can deliver private 5G as a repeatable product rather than a systems-integration project. It’s summarized in this table:
| Market segment | Likely effect of Nokia’s ECE sale |
|---|---|
| Enterprise private-5G specialists | Celona, Kajeet, Anterix-adjacent ecosystem players, and similar vendors gain a larger addressable base as ECE becomes a standalone competitor rather than part of a diversified Nokia portfolio. Omdia’s 2026 assessment already treats Celona, Ericsson, HPE, Nokia, Samsung, and ZTE as leading end-to-end private-5G vendors. |
| Mobile operators | Nokia’s reduced direct enterprise engagement may reduce channel conflict with operators selling private 5G to the same factories, ports, and campuses—an issue Fierce Network identifies as part of Nokia’s rationale. |
| Systems integrators |
A private-equity-owned ECE is likely to be more open to third-party radios, cores, edge compute, and integration partners, expanding routes to market for component and software suppliers.
|
| Industrial OT and AI vendors | ECE’s emphasis on on-premises OT data, sovereignty, and AI-enabled automation validates the shift from “private 5G as connectivity” toward private 5G as an industrial automation platform. |
| Hyperscalers and cloud providers | The sale reinforces the view that enterprise edge value is migrating toward application orchestration, data pipelines, and AI workloads—areas where cloud-native entrants can compete without owning the RAN. |
Conclusions:
Nokia’s sale of ECE will likely make the private-5G market more fragmented, more multi-vendor, and more focused on industrial outcomes rather than network equipment alone. That favors AI wireless specialists such as Celona, systems integrators like Kyndryl, and silicon innovators such as EdgeQ—but only if they can convert openness into lower total cost of ownership, faster deployment, and proven operational reliability.
The ECE sale removes one major integrated competitor from the enterprise campus. It does not remove the requirement that private 5G operate with industrial-grade determinism, security, and lifecycle assurance. The near-term risk for ECE is transition uncertainty. Its customers will want assurance that product roadmaps, support arrangements, and contractual commitments survive the ownership change.
Longer term, however, AURELIUS’s stated plan to expand ECE into AI-powered industrial automation could make it a more focused, and potentially more aggressive, competitor in manufacturing, logistics, mining, ports, and energy.
References:
https://www.nokia.com/newsroom/nokia-to-sell-enterprise-campus-edge-business-to-aurelius/
https://www.telecoms.com/telecoms-infrastructure/nokia-sells-off-enterprise-campus-edge-business
SNS Telecom & IT: Private 5G for the Defense Sector to hit $2.5 Billion by 2029
SNS Telecom & IT: Private 5G Market to Reach $6.6 Billion as Physical AI Takes Hold
GSA: Global private mobile networks exceed 2,000 worldwide; Ericsson Private 5G from Verizon Business extends beyond U.S.
Private 5G networks move to include automation, autonomous systems, edge computing & AI operations
OneLayer Raises $28M Series A funding to transform private 5G networks with enhanced security
Verizon partners with Nokia to deploy large private 5G network in the UK
EdgeQ’s breakthrough demos and partnerships showcased at MWC 2024 & MWC 2023
EdgeQ Samples World’s 1st Software-Defined 5G Base Station-on-a-Chip
SoC start-up EdgeQ comes out of stealth mode with 5G/AI silicon for 5G private networks/IIoT
SNS Telecom & IT: Private 5G for the Defense Sector to hit $2.5 Billion by 2029
SNS Telecom & IT’s latest research report indicates that cumulative spending on private 5G networks in the defense sector will reach $2.5 billion between 2026 and 2029. The military has a longstanding history of leveraging wireless communications, and some of the most significant wireless-related innovations of the 20th century originated in the defense sector. With significant advances in COTS (Commercial Off-the-Shelf) technology over the past two decades, there has been a growing focus on complementing proprietary solutions with 3GPP standards-based networks to deliver both local and wide area coverage for capabilities extending from smart base operations and tactical networking to ISAC (Integrated Sensing & Communications)-enabled sensing for counter-drone protection.
Although public networks running over national mobile operator-owned RAN and core infrastructure are widely utilized for personal connectivity and non-sensitive IoT applications, defense sector stakeholders are increasingly turning their attention to exclusive-use, private 5G networks tailored to specific operational requirements in terms of security, access control, customization and specialized feature support.
Spearheaded by initiatives such as the United States DOW’s (Department of War) FutureG program, South Korean Ministry of National Defense’s private 5G project for unmanned and remote operations, United Kingdom MOD’s (Ministry of Defence) Project Morpheus, German Army’s D-LBO (Digitalization of Land-Based Operations), Spanish Air & Space Force’s BACSI (Connected, Sustainable & Intelligent Air Base), Italian Ministry of Defense’s DII (Defense Information Infrastructure), EU-funded 5G COMPAD 2.0 (5G Communications for Peacekeeping & Defense), NATO’s MN5G (Multinational Collaboration on 5G) and DIANA (Defence Innovation Accelerator for the North Atlantic), armed forces around the globe are actively investing in both permanent and transportable private 5G networks for warfighters at the tactical edge, military bases and training facilities. The U.S. military, for instance, has multiple deployments across the continental United States and overseas, including operational networks for the Indo-Pacific and Africa Commands. Canada, Germany, United Kingdom, France, Belgium, Netherlands, Switzerland, Spain, Portugal, Italy, Sweden, Norway, Denmark, Finland, Estonia, Latvia, Czech Republic, Hungary, Greece, Türkiye, Ukraine, Russia, China, Australia, Japan, South Korea, Singapore, India, Pakistan, Saudi Arabia, United Arab Emirates, Qatar, Jordan, Egypt, Israel and Brazil are among the other countries where experimental and operational networks have been deployed, operating in spectrum ranging from sub-1 GHz frequencies to bands n78 (3.5 GHz), n77 (3.7 GHz) and n79 (4.4-5 GHz), as well as mmWave bands.
The expanding influence of private networks is also evident from the recent use of rapidly deployable cellular systems for enhanced communications in military exercises such as the JIFX (Joint Interagency Field Experimentation) program hosted by the Naval Postgraduate School; Washington Air National Guard’s Exercise Phoenix Dawn; Italian Navy’s OPEX (Operational Experimentation) 2-25 in the Gulf of Taranto; German Army’s urban warfare training drills; Norwegian military’s Joint Viking exercise in the Arctic Circle; SABAK, a joint exercise of the Philippine Army and USARPAC (U.S. Army Pacific) forces; U.S. Marine Corps’ Steel Knight and ITX (Integrated Training Exercise); JGSDF’s (Japan Ground Self-Defense Force) Nankai Rescue disaster response training drill; and REPMUS, an unmanned systems experimentation exercise led by the Portuguese Navy.
SNS Telecom & IT’s “Private 5G/4G Cellular Networks for Defense: 2026 – 2030” report projects that global spending on private 5G and 4G LTE networks in the defense sector will grow at a CAGR of 24% over the next three years, collectively accounting for nearly $2.5 billion in cumulative investments between 2026 and 2029. For more information, please visit: https://www.snstelecom.com/
About SNS Telecom & IT
SNS Telecom & IT is a global market intelligence and consulting firm with a primary focus on the telecommunications and information technology industries. Developed by in-house subject matter experts, our market intelligence and research reports provide unique insights on both established and emerging technologies. Our areas of coverage include but are not limited to 6G, 5G, LTE, Open RAN, vRAN, small cells, mobile core, xHaul transport, network automation, mobile operator services, FWA, neutral host networks, private 4G/5G cellular networks, public safety broadband, critical communications, MCX, IIoT, V2X communications and vertical applications.
………………………………………………………………………………………………………………………………………………………………………………..
References:
https://www.snstelecom.com/
SNS Telecom & IT: Private 5G Market to Reach $6.6 Billion as Physical AI Takes Hold
GSA: Global private mobile networks exceed 2,000 worldwide; Ericsson Private 5G from Verizon Business extends beyond U.S.
Private 5G networks move to include automation, autonomous systems, edge computing & AI operations
SNS Telecom & IT: Private 5G Market Nears Mainstream With $5 Billion Surge
Verizon partners with Nokia to deploy large private 5G network in the UK
SNS Telecom & IT: Private 5G and 4G LTE cellular networks for the global defense sector are a $1.5B opportunity
SNS Telecom & IT: Private 5G Market to Reach $6.6 Billion as Physical AI Takes Hold
Private 5G networks are transitioning from limited-scale deployments to a more material segment of the wireless infrastructure market. SNS Telecom & IT estimates that annual spending on private 5G networks will exceed $6.6 billion by 2029, driven by multi-site and multi-national enterprise rollouts supporting industrial automation, “physical AI” systems, and mission-critical communications across both commercial and public-sector domains.
Historically, private cellular deployments remained a niche market during the 2G/3G era, with notable exceptions such as GSM-R for railway communications. The introduction of private LTE in the early 2010s established a foundation for dedicated enterprise connectivity; however, adoption remained constrained by performance limitations and ecosystem maturity. The evolution to 3GPP-defined 5G NPN architectures—both standalone (SNPN) and public network-integrated (PNI-NPN)—is now enabling broader applicability across industrial verticals, with a trajectory that exceeds prior-generation adoption levels. Concurrently, legacy systems such as GSM-R are expected to transition toward 5G-based FRMCS implementations aligned with 3GPP specifications.
From a technical perspective, 5G introduces capabilities that are better aligned with industrial communication requirements than LTE. Enhanced mobile broadband (eMBB), ultra-reliable low-latency communications (URLLC), and massive machine-type communications (mMTC) collectively support higher throughput, sub-10 ms latency targets, improved reliability, and significantly greater device densities. These characteristics enable 5G NPNs to address use cases traditionally served by wired Ethernet or deterministic industrial networks, particularly in scenarios requiring mobility and flexible topology. Additional attributes—including improved coverage per radio node, network slicing, time-sensitive networking (TSN) integration, and enhanced security mechanisms—position private 5G as a viable alternative to interference-prone unlicensed technologies in dense IIoT environments.
Deployment momentum is increasingly visible across manufacturing, logistics, energy, and transportation sectors. Production-grade implementations have demonstrated measurable operational benefits, including reduced downtime, improved safety, and expanded coverage in previously unconnected areas. A common pattern involves the migration of AGV and AMR connectivity from Wi-Fi to private 5G, enabling more deterministic performance and reduced susceptibility to interference. In parallel, private 5G is extending connectivity to challenging industrial zones where wired infrastructure is cost-prohibitive or operationally restrictive. Emerging use cases also include coordinated robotics and edge-controlled automation systems, often described as “physical AI,” where low-latency and reliable connectivity are critical for closed-loop control.
In the public-sector domain, private 5G is gaining traction for mission-critical communications. Applications span defense, public safety, railways, and utilities, where requirements include high availability, secure communications, and support for MCX services (mission-critical push-to-talk, video, and data). The evolution toward 5G-Advanced, as defined in 3GPP Releases 18 through 20, introduces further enhancements relevant to these deployments, including support for reduced channel bandwidth operation in dedicated spectrum, expanded frequency bands, and specific feature sets aligned with FRMCS and mission-critical service requirements.
Geographically, adoption is concentrated in markets with established industrial bases and supportive regulatory frameworks, including North America, Europe, and parts of Asia-Pacific. As enterprises scale digitalization initiatives—encompassing automation, AI-driven operations, and connected workforce applications—private 5G deployments are increasingly moving beyond pilot phases to multi-site, production-grade networks.
SNS Telecom & IT projects a compound annual growth rate of approximately 34% for private 5G investments between 2026 and 2029. Growth is expected to be led by localized enterprise and campus networks, alongside parallel expansion in mission-critical infrastructure. The combination of maturing 3GPP standards, improving device ecosystems, and demonstrated operational benefits is positioning private 5G as a foundational connectivity layer for next-generation industrial and public-sector systems.
References:
https://www.snstelecom.com/private5g
GSA: Global private mobile networks exceed 2,000 worldwide; Ericsson Private 5G from Verizon Business extends beyond U.S.
Private 5G networks move to include automation, autonomous systems, edge computing & AI operations
SNS Telecom & IT: Mission-Critical Networks a $9.2 Billion Market
SNS Telecom & IT: Private 5G Market Nears Mainstream With $5 Billion Surge
SNS Telecom & IT: Private 5G and 4G LTE cellular networks for the global defense sector are a $1.5B opportunity
OneLayer Raises $28M Series A funding to transform private 5G networks with enhanced security
Verizon partners with Nokia to deploy large private 5G network in the UK
GSA: Global private mobile networks exceed 2,000 worldwide; Ericsson Private 5G from Verizon Business extends beyond U.S.
The number of worldwide private mobile networks that are worth more than €100,000 exceeds 2,000, according to the Global mobile Suppliers Association (GSA). Demand is being driven by the growing data, security, digitization and mobility requirements of modern enterprise and government entities. GSA said that at the end of 1Q2026, it had identified 2,003 organizations in 88 countries worldwide that had deployed one or more private mobile networks. The private mobile networks it counted had contract values of more than €100,000 (~$116,000). A further 178 private mobile networks are worth between €50,000 and €100,000, GSA said.
4G-LTE remains the dominant technology, accounting for 1,369 of the customers catalogued by the GSA, but 5G is inching up; 5G is deployed in 974 of the networks, often in conjunction with LTE, but 5G-only networks increased by one percentage point on Q4 2025 to account for 30.3% of customers. GSA said that 76% of the references are non-public and unique. Some industries are cagier than others– in sectors like military and defense, maritime, and the power plants space more than 80% of references are not in the public domain.
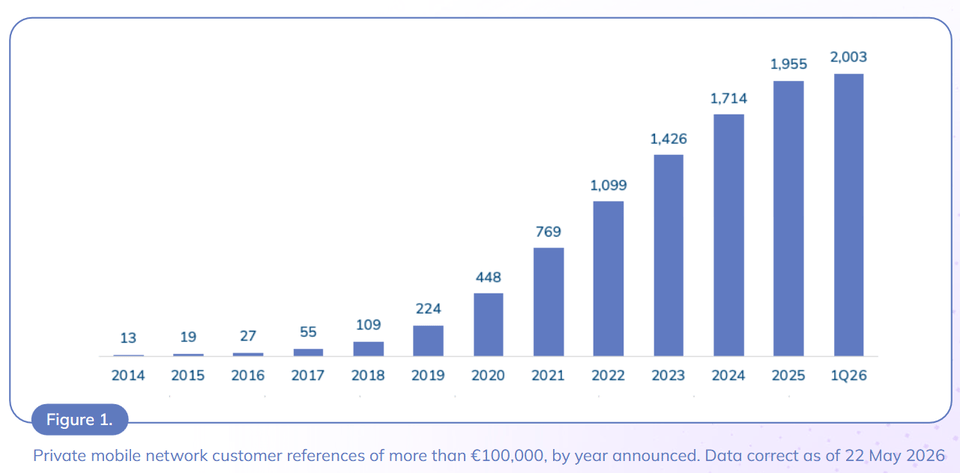
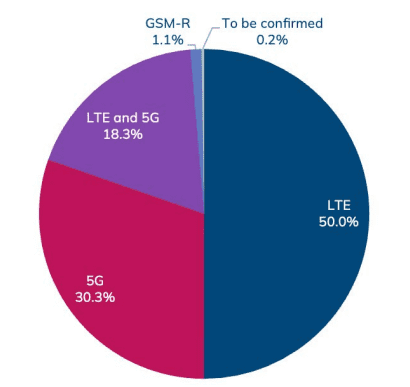
Image Source: GSA
Although the proportion of 5G only deployments makes up a significant number of references (30.3%), it must be noted that this number skews toward long-term trials and deployments within educational and test-bed or validation facilities, with a limited number running real operation in industrial situations.
………………………………………………………………………………………………………………………………………………………………………………………………………….
The top five markets are currently the US, Germany, the UK, China and Japan, but those markets were exceeded in growth terms in the first quarter of 2026 by another market in the top 10; Canada saw the number of customers of private mobile networks grow by 5% in Q1. The UK had the next-highest growth rate at 4%, followed by the US at 2% and Germany at 1%.
China is often reported to have a high number of private networks at more than 40,000, the GSA said. But it believes that many of those networks actually use public mobile networks and therefore do not meet its definition for inclusion in its report.
“As the report clearly shows, a large number and varied range of market participants are actively engaged in developing and delivering solutions for private mobile networks,” said GSA president Joe Barrett, in a statement accompanying the group’s latest Private Mobile Networks publication.
“With so much opportunity, and so many regulators planning initiatives to make spectrum available for LTE and 5G private usage, we expect significant market developments over the next couple of years,” Barrett said. Naturally, there is a strong correlation between the number of private mobile networks in a country and the availability of dedicated spectrum there. In addition, private mobile network deployments are mainly in high-income and upper-middle-income countries, according to the GSA.
The GSA did not specifically mention the high-income Middle Eastern markets in its report summary, but it’s probably safe to assume that countries like Oman will help to drive growth going forward. Port of Salalah in the south of Oman announced the launch of the country’s first fully managed private 5G network in partnership with incumbent telecoms operator Omantel. The network will support automation and accelerate the port’s digital transformation, boosting the efficiency of its logistics operations, it said. And both parties indicated that they expect the deal to kick-start the wider use of private enterprise 5G networks in Oman, looking specifically at ports, logistics and industry.
…………………………………………………………………………………………………………………………………………………………………………………………………………………………………
Ericsson Private 5G is now available through Verizon Business beyond U.S. borders. It’s targeted at global enterprises already using Ericsson technology in Verizon Business Private 5G Networks in the U.S., allowing them to extend it to international campuses. It offers a dual mode 4G and 5G network with global spectrum support
“Verizon Business can offer more optionality and flexibility to its private wireless customers who operate across international borders,” states the press release.
Hannes Ekström, Senior Vice President and Head of Customer Unit Verizon, Ericsson Americas, says: “Enterprises are rapidly embracing digital transformation, leveraging secure and high-performing private 5G networks as a key driver of innovation and efficiency. Our multinational customers in the U.S. have already unlocked significant growth through 5G-enabled private networks, and now they seek to replicate this success globally.”
“Through our collaboration with Verizon, we are expanding the reach of our Ericsson Private 5G solution to support Verizon Business’s international deployments, enabling seamless global operations. By simplifying 5G adoption and enhancing reliability, low latency, and security, we are empowering industries to harness next-generation connectivity and drive innovation on a global scale.”
“Verizon Business is proud of our expanding private wireless portfolio, and we’re committed to providing the best possible private wireless experience to our customers around the world,” said Robb Juliano, Vice President of 5G Acceleration, Verizon Business. “By extending the availability of Ericsson Private 5G outside of the U.S., we’re offering enterprises more flexibility in driving innovation, enhancing security, and optimizing operations with private wireless networks on a global scale.”
References:
https://gsacom.com/technology/private-mobile-networks/
https://gsacom.com/paper/private-mobile-networks-june-2026/
https://www.telecoms.com/5g-6g/private-mobile-networks-exceed-2-000-worldwide
https://www.ericsson.com/en/press-releases/2026/6/ericsson-private-5g-for-verizon-business
Private 5G networks move to include automation, autonomous systems, edge computing & AI operations
SNS Telecom & IT: Private 5G Market Nears Mainstream With $5 Billion Surge
SNS Telecom & IT: Private LTE & 5G Network Ecosystem – CAGR 22% from 2025-2030
SNS Telecom & IT: Mission-Critical Networks a $9.2 Billion Market
Verizon partners with Nokia to deploy large private 5G network in the UK
SNS Telecom & IT: Private 5G and 4G LTE cellular networks for the global defense sector are a $1.5B opportunity
HPE Aruba Launches “Cloud Native” Private 5G Network with 4G/5G Small Cell Radios
SNS Telecom & IT: Private 5G Network market annual spending will be $3.5 Billion by 2027
SNS Telecom & IT: Private 5G and 4G LTE cellular networks for the global defense sector are a $1.5B opportunity
Ericsson integrates Agentic AI into its NetCloud platform for self healing and autonomous 5G private networks
Private 5G networks move to include automation, autonomous systems, edge computing & AI operations
A new report from PrivateLTEand5G.com analyzes the rapid evolution and expansion of global private cellular networks. The market research firm states that organizations worldwide shifted decisively from Private 5G feasibility trials to large-scale, operationally-integrated deployments. The defining theme is no longer just connectivity, but intelligent automation, with private 5G – often in 5G Standalone (SA) configurations – powering sophisticated applications including autonomous vehicle fleets, AI-driven quality control, remote machinery operation, and comprehensive digital twins.
“The year 2025 marked a significant acceleration in the private cellular network market,” said Ashish Jain, Co-founder of KAIROS Pulse and PrivateLTEand5G.com. “Private network deployments are increasingly focused on enabling intelligent automation rather than simply providing connectivity. We’re seeing autonomous haulage systems in complex mining environments, AI-powered video analytics for safety, and private networks actively replacing legacy systems like Wi-Fi, DECT, and pagers in mission-critical healthcare and utilities operations.”
The report documents 70+ verified private network deployments across tens of countries, providing the granular intelligence your organization needs to navigate this rapidly evolving landscape in 2026. Industry-specific insights on key private cellular use cases:
- Manufacturing & Industrial: Smart factories deploying 5G for AI-driven quality control, digital twins, and autonomous logistics
- Ports & Logistics: Real-time cargo tracking, autonomous vehicle coordination, and crane digitalization at the world’s busiest terminals
- Transportation Infrastructure: Airports, railways, and smart mobility deploying mission-critical connectivity
- Healthcare & Education: Private networks enabling telemedicine, campus safety, and immersive learning
- Energy & Mining: Remote operations, predictive maintenance, and worker safety in extreme environments

Featured deployments span dozens of countries and showcase groundbreaking implementations such as:
- •Autonomous Operations: Aker BP’s fully autonomous private 5G on North Sea oil platforms; Air New Zealand’s drone-based automated inventory management
- AI-Driven Manufacturing: BMW’s Debrecen facility with AI quality control and 1,000 industrial robots; Hyundai’s RedCap wireless vehicle inspection technology
- Mission-Critical Replacement: Austria’s Gesundheit Burgenland replacing pagers and DECT across five hospitals; Memphis utility’s CBRS network modernizing grid operations
- Broadcast Innovation: BT’s multiple network slicing deployment for Emirates Sail Grand Prix; T-Mobile’s dedicated 5G for MLB All-Star Game
- Transportation Transformation: Deutsche Bahn’s first commercial 5G railway network; Maersk’s fleet-wide LTE across 450 ships
“While industrial sectors like manufacturing, mining, and logistics continue to lead adoption, the use cases have evolved substantially,” Jain noted. “The rise of Neutral Host networks is solving connectivity challenges for public-facing venues like stadiums and airports, while advanced 5G features like network slicing enable demanding applications such as live 4K broadcast production.”
The report emphasizes that the availability of dedicated spectrum – from CBRS in the United States to licensed bands in Europe and Asia – remains a critical enabler, providing the deterministic reliability required for autonomous and mission-critical systems being deployed.
The complete report is available for download at PrivateLTEand5G.com. The company says “it offers essential insights for enterprise technology leaders, telecom operators, system integrators, and innovation teams planning private cellular network strategies.”
………………………………………………………………………………………………………………………………………………………………………………………………………………..
Here’s what Google Gemini has to say about recent Private 5G network developments:
- Intelligent Automation & AI Operations: The focus has moved beyond simple connectivity. Private 5G, often in Standalone (SA) configurations, is now the backbone for sophisticated applications like autonomous vehicle fleets, remote-controlled machinery, and AI-driven quality control in industries such as manufacturing and mining. AI and Machine Learning (ML) are also being used for predictive maintenance and real-time network orchestration.
- Edge Computing Integration: To support the massive data generated by IoT devices and AI applications, data processing is moving closer to the source (the edge) to reduce latency and improve efficiency. This synergy is crucial for real-time decision-making in critical operations.
- 5G-Advanced Features (3GPP Release 18): Commercialization of 5G-Advanced is underway and introduces critical industrial features, including:
- URLLC (Ultra-Reliable, Low-Latency Communications): Essential for replacing wired connections in mission-critical control systems (achieving millisecond response times).
- 5G RedCap (Reduced Capability): A cost-efficient technology for lower-power IoT and industrial sensors, bridging the gap between basic IoT needs and full 5G capabilities.
- Network Slicing: This allows enterprises to create multiple virtual networks on a single physical infrastructure, each tailored with specific performance parameters (e.g., bandwidth, latency) for different applications.
- Open RAN and Virtualization: The adoption of Open Radio Access Network (Open RAN) and virtualized RAN solutions is increasing, reducing infrastructure costs, preventing vendor lock-in, and allowing for greater vendor diversity.
- Hybrid Networks: Enterprises are increasingly combining private 5G with existing Wi-Fi 6/7 networks and public cellular coverage (neutral host systems) to provide seamless indoor and outdoor connectivity across large campuses and remote areas.
- Enhanced Security: Private 5G inherently offers better security than public networks through dedicated, isolated environments and SIM-based authentication. New solutions from companies like Palo Alto Networks and Trend Micro are focusing on extending security visibility across both IT and operational technology (OT) domains.
- Market Growth: The private 5G market is experiencing rapid acceleration, projected to grow at a CAGR of over 40% through the rest of the decade.
- Key Industries: Manufacturing, logistics, mining, utilities, and healthcare are leading the adoption, leveraging private 5G for use cases such as factory automation, connected robotics, remote patient monitoring, and autonomous vehicles.
- Regional Markets:
- North America: Dominates the market in spending and innovation, driven by spectrum access like CBRS (Citizens Broadband Radio Service).
- Asia-Pacific: The fastest-growing region, with China leading in large-scale deployments due to state-funded initiatives.
- Europe: Seeing significant interest, with countries like Germany, the UK, and Sweden allocating dedicated local spectrum for industrial use.
- Simplified Deployment: To overcome the complexity and skill shortages associated with deployments, vendors are offering “network-in-a-box” solutions and “5G-as-a-service” (5GaaS) models, which shift costs from capital expenditures (CapEx) to operational expenditures (OpEx).
………………………………………………………………………………………………………………………………………………………………………………………………………………………..
References:
https://www.privatelteand5g.com/reports/private-cellular-network-deployments-report-2026/
SNS Telecom & IT: Private 5G Market Nears Mainstream With $5 Billion Surge
SNS Telecom & IT: Private 5G and 4G LTE cellular networks for the global defense sector are a $1.5B opportunity
SNS Telecom & IT: Private 5G Network market annual spending will be $3.5 Billion by 2027
OneLayer Raises $28M Series A funding to transform private 5G networks with enhanced security
Verizon partners with Nokia to deploy large private 5G network in the UK
HPE Aruba Launches “Cloud Native” Private 5G Network with 4G/5G Small Cell Radios
Tata Consultancy Services: Critical role of Gen AI in 5G; 5G private networks and enterprise use cases
SNS Telecom & IT: Private LTE & 5G Network Ecosystem – CAGR 22% from 2025-2030
SNS Telecom & IT’s latest research report, “Private LTE & 5G Network Ecosystem: 2025 – 2030” indicates that the private LTE and 5G network market is estimated to be worth $7.2 billion by the end of 2028 and continues to grow as private 5G deployments overtake LTE across many vertical industries. This steady, strong growth stands in contrast to the tepid pace of infrastructure spending in the much larger but relatively stagnant public mobile network market, where standalone 5G core investments are growing but RAN (Radio Access Network) sales remain flat following a sharp decline last year.
Against this backdrop, the real-world impact of private networks – spanning both facility/campus-based and wide area deployments – is clearly visible across a diverse range of customers, from manufacturers, port operators, and airlines to sports clubs and public sector organizations.
Among many other impactful examples, Tesla, LG Electronics, and Hyundai have eliminated connection-related AGV (Automated Guided Vehicle) stoppages at their production facilities; Peel Ports Group has experienced a tenfold increase in network performance at the Port of Liverpool’s metal-heavy environment, which previously hindered Wi-Fi connectivity; Lufthansa has achieved a 75% improvement in operational process speed at its LAX cargo facility; partially sighted fans are able to experience football matches in exceptional detail using private 5G-connected headsets at Crystal Palace Football Club’s Selhurst Park stadium; and police forces in Ontario’s Peel-Halton Region have had uninterrupted in-vehicle data access – especially during outages affecting public mobile operator services – since adopting their independent public safety broadband network, which has recently undergone a 5G core upgrade.
While these practical and tangible benefits are already compelling, another sign of the market’s positive momentum is how customers are increasingly incorporating private 5G networks as a key component of their new facilities. A recent case in point is GDC’s (Georgia Department of Corrections) new state prison project, which also involves the implementation of a secure and physically isolated private 5G network using Band n48 (3.5 GHz) CBRS spectrum to provide indoor and outdoor coverage at a greenfield prison campus with 13 buildings covering 800,000 square feet across 200 acres. Examples of other facilities where private 5G networks have been or are being deployed from the outset include Hitachi Rail’s Hagerstown factory, Hyundai Motor’s HMGMA electrified vehicle plant, Los Angeles Chargers’ El Segundo training facility, Formula 1’s Las Vegas complex, Cleveland Clinic’s Mentor Hospital, CHI’s (Children’s Health Ireland) New Children’s Hospital, Port of Aberdeen’s South Harbour, NEC’s Kakegawa plant; Pegatron’s Batam smart factory, PATTA’s low-carbon Renwu factory, and Jacto’s Paulópolis production facility.
SNS Telecom & IT’s “Private LTE & 5G Network Ecosystem: 2025 – 2030” report projects that global spending on private LTE and 5G network infrastructure for vertical industries will grow at a CAGR of approximately 22% between 2025 and 2028, eventually exceeding $7.2 billion by the end of 2028. More than 70% of these investments – an estimated $5.1 billion – will be directed towards the buildout of standalone private 5G networks, which are well-positioned to become the predominant wireless connectivity medium for Industry 4.0 applications in manufacturing and process industries, as well as critical communications over mission-critical broadband networks for sectors such as public safety, defense, utilities, and transportation. This unprecedented level of growth is likely to transform the private RAN, mobile core, and transport network segments into an almost parallel equipment ecosystem to public mobile operator infrastructure in terms of market size by the late 2020s. By 2030, private networks could account for as much as a fourth of all mobile network infrastructure spending.
About SNS Telecom & IT:
SNS Telecom & IT is a global market intelligence and consulting firm with a primary focus on the telecommunications and information technology industries. Developed by in-house subject matter experts, our market intelligence and research reports provide unique insights on both established and emerging technologies. Our areas of coverage include but are not limited to 6G, 5G, LTE, Open RAN, vRAN, small cells, mobile core, xHaul transport, network automation, mobile operator services, FWA, neutral host networks, private 4G/5G cellular networks, public safety broadband, critical communications, MCX, IIoT, V2X communications, and vertical applications.
………………………………………………………………………………………………………………………………………………………………………………………………………
References:
https://www.snstelecom.com/private-lte
Private 5G networks move to include automation, autonomous systems, edge computing & AI operations
SNS Telecom & IT: Private 5G Market Nears Mainstream With $5 Billion Surge
SNS Telecom & IT: Private 5G and 4G LTE cellular networks for the global defense sector are a $1.5B opportunity
SNS Telecom & IT: $6 Billion Private LTE/5G Market Shines Through Wireless Industry’s Gloom
SNS Telecom & IT: Private 5G Network market annual spending will be $3.5 Billion by 2027
SNS Telecom & IT: Q1-2024 Public safety LTE/5G report: review of engagements across 86 countries, case studies, spectrum allocation and more
SNS Telecom & IT: Shared Spectrum 5G NR & LTE Small Cell RAN Investments to Reach $3 Billion
SNS Telecom & IT: CBRS Network Infrastructure a $1.5 Billion Market Opportunity
SNS Telecom & IT: Private LTE & 5G Network Infrastructure at $6.4 Billion by end of 2026
SNS Telecom & IT: Open RAN Intelligent Controller, xApps & rApps to reach $600 Million by 2025
SNS Telecom & IT: Shared Spectrum to Boost 5G NR & LTE Small Cell RAN Market
Challengers & Leaders in Gartner’s Magic Quadrant for 4G and 5G Private Mobile Network Services?
Here’s the chart from the Gartner report:

This author is astonished and perplexed that Gartner lumped service providers, network equipment makers and systems integrators into the same set of leaders and challengers. That’s like comparing apples to oranges to pineapples?
Steve Saunders strongly criticized the report, noting that “Five companies lead the private 5G network (equipment/software) market: Ericsson, Huawei, Nokia, Samsung, and ZTE. Challengers include Cisco, IBM, Juniper, and Mavenir (though none of them make their own 5G chips or have the same level of 5G juju as the 5G Big 5). Gartner’s new Magic Quadrant omits six (!) of these vendors, including Huawei, whose technology underlies literally hundreds of private 5G networks.”
…………………………………………………………………………………………………………………………….
Inclusion and Exclusion Criteria:
-
At least 20 direct, deployed commercial contracts or 20 direct, deployed commercial sites (excluding POCs) for 4G and 5G private mobile network services managed by the vendor, where it is the prime contractor with the enterprise (end user)
-
At least 25% of commercial contracts (excluding POCs) for 4G and 5G private mobile
-
Commercial contracts in two or more regions where the vendor is the prime contractor, (excluding POCs) for 4G and 5G private mobile network services provided by the vendor. Regions are defined as follows:
-
North America
-
Latin America
-
Western Europe
-
Eastern Europe
-
Eurasia
-
Greater China
-
Emerging Asia/Pacific
-
Mature Asia/Pacific
-
Middle East and North Africa
-
Sub-Saharan Africa
-
Other
-
-
At least two or more commercial contracts won where the vendor is the prime contractor, (excluding POCs) for 4G and 5G private mobile network services managed by the vendor in the last 12 months
-
Provide the following capabilities defined in this Magic Quadrant as prime contractor or through a third party:
-
Network end-to-end sourcing
-
Network design
-
Implementation and integration
-
Service management and support
-
……………………………………………………………………………………………..
-
Scope of the offering, and planned or ongoing investments in the following segments in terms of capabilities covered in this Magic Quadrant and specific offerings per segment, preintegrated functions with ecosystem partners, productized versus project-based offering for each segment, and geographical availability of each of the offerings (global/regional/local):
-
Dedicated/stand-alone
-
Hybrid PMN
-
PMN with core network slicing
-
Campus and level of integration with WLAN solutions
-
PMN for industrial sites including OT security capabilities and compliance
-
Multisite, including management capabilities to provide a centralized life cycle management experience for all included sites
-
PMN offering for small and midsize businesses
-
-
PMN-related acquisitions or strategic partnerships to add capabilities to the PMN offering
-
Radio planning and site survey capabilities
-
Modularity of the offer
-
Flexibility to offer an open partner ecosystem for core PMN elements (radio, core network, monitoring and life cycle management, edge/cloud computing infrastructure stack, SIM management)
-
Public network integration (private/public handover features)
-
Service management options (self-service, co-managed, fully managed service)
-
API capabilities
-
Bundling capabilities with other related prepackaged technologies and services such as IoT, MEC, managed mobility, cloud, security, industry-edge application
-
The design, logic and execution of the vendor’s business proposition to achieve continued success
-
The value proposition, revenue models, customer segmentation, distribution channels, etc.
-
Appropriate use of build/buy/partner options to maximize profitability
-
Management of customization costs
-
Use of automation to improve cost-efficiency
-
Scope of the spectrum offered: regulated and industrial spectrum (CBRS type)
-
Proof of concept models
-
Flexibility offering capex and opex models
-
Flexibility to bring your own partners
References:
https://www.gartner.com/doc/reprints?id=1-2J9ZQDL4&ct=241105&st=sb
https://www.fierce-network.com/wireless/op-ed-gartner-biffs-its-new-4g5g-magic-quadrant
https://www.cisco.com/c/en/us/solutions/private-5g-networks.html
https://www.celona.io/the-state-of-private-wireless
SNS Telecom & IT: Private 5G and 4G LTE cellular networks for the global defense sector is a $1.5B opportunity
SNS Telecom & IT: Private 5G Network market annual spending will be $3.5 Billion by 2027
Highlights of GSA report on Private Mobile Network Market – 3Q2024
Highlights of GSA report on Private Mobile Network Market – 3Q2024
According to GSA, the private mobile network market (PMNM) continued to grow in 3Q2024, as the number of unique customer references for deployments reached 1,603. The market is being driven by sectors like manufacturing, education, and mining, which use these networks for enhanced data, security and mobility needs.
On average, 71% of references included in the GSA database are non-public and unique to this database, submitted by members of the GSA Private Mobile Networks Special Interest Group (SIG). This number can be higher for certain industries, with more than 80% of sectors such as military and defense, maritime and power plants not visible in the public domain. The referenced SIG includes 16 companies: 450Alliance, 5G-ACIA, AI-Link, Airspan, Celona, Dell, Ericsson, GSMA, JMA Wireless, Keysight Technologies, Mavenir, Nokia, OnGo Alliance, OneLayer, PrivateLTEand5G.com and TCCA. GSA would like to thank its members 450Alliance, Airspan, Celona, Ericsson, Keysight Technologies, Mavenir, Nokia and OneLayer for sharing general information about their network deployments to enable this report and data set to be produced. New data has resulted in a significant uplift in this update.
Other PMNM highlights in the 3rd quarter 2024 include:
• There are 80 countries around the world with at least one private mobile network.
• Of the top 10 reporting countries, the United States reported growth of 24%, followed by the United Kingdom, up 11%, Sweden by 9% and Japan and Australia by 5% each. Finland and the Republic of Korea grew by 4% each
• Seaports and oil and gas were the fastest-growing industries, up 9%. Manufacturing, education and academic research and mining remain the top three sectors for customer references, although this does not represent the actual size and scale of deployments, which vary by user type.
• There are 80 countries around the world with at least one private mobile network.
• There is typically a strong, positive correlation between the number of private mobile network references and countries with dedicated spectrum. Private mobile networks are mainly in high- and upper-middle-income regions so far, with the United States, Germany, the United Kingdom, China and Japan having the most references. It is sometimes reported that China has a high number of networks, reaching up to 30,000, but GSA believes a large portion use the public network and therefore do not meet our definition.
Notes:
The definition of a private mobile network used in this report is a 3GPP-based 4G LTE or 5G network intended for the sole use of private entities, such as enterprises, industries and governments. They can use only physical elements, RAN or Core, or a combination of physical and virtual elements — for example hosted by a public land mobile network — but as a minimum, a dedicated network core must be implemented. The definition includes MulteFire or Future Railway Mobile Communication System. The network must use spectrum defined in 3GPP, be generally intended for business-critical or mission-critical operational needs, and where it is possible to identify commercial value, the database includes contracts worth more than €50,0000 and between €50,000 and €100,000 to filter out small demonstration network deployments. Private mobile networks are usually not offered to the general public, although GSA’s analysis does include the following: educational institutions that provide mobile broadband to student homes; private fixed wireless access networks deployed by communities for homes and businesses; city or town networks that use local licenses to provide wireless services in libraries or public places (possibly offering Wi-Fi with 3GPP wireless backhaul), which are not an extension of the public network.
Non-3GPP networks such as those using Wi-Fi, TETRA, P25, WiMAX, Sigfox, LoRa and proprietary technologies are excluded from the data set. Network implementations using solely network slices from public networks or placement of virtual networking functions on a router are also excluded. Where identifiable, extensions of the public network (such as one or two extra sites deployed at a location, as opposed to dedicated private networks) are excluded. These items may be described in the press as a type of private network.
References:
SNS Telecom & IT: Private 5G and 4G LTE cellular networks for the global defense sector is a $1.5B opportunity
SNS Telecom & IT: $6 Billion Private LTE/5G Market Shines Through Wireless Industry’s Gloom
SNS Telecom & IT: Private 5G Network market annual spending will be $3.5 Billion by 2027
Dell’Oro: Private RAN revenue declines slightly, but still doing relatively better than public RAN and WLAN markets
Pente Networks, MosoLabs and Alliance Corp collaborate for Private Cellular Network in a Box
HPE Aruba Launches “Cloud Native” Private 5G Network with 4G/5G Small Cell Radios
SNS Telecom & IT: Private 5G and 4G LTE cellular networks for the global defense sector are a $1.5B opportunity
SNS Telecom & IT says that private 5G in the global Defense Sector is a $1.5 Billion opportunity. The market research firm’s latest report indicates that cumulative spending on private 5G networks in the defense sector will reach $1.5 Billion between 2024 and 2027.
Private 5G and 4G LTE cellular networks – also referred to as NPNs (Non-Public Networks) in 3GPP terminology – are rapidly gaining popularity across a diverse range of vertical industries. The defense industry is no exception to this trend, with private cellular network solutions in the sector extending from permanent 5G networks at military bases and training facilities to satellite-backhauled portable cellular systems for warfighters at the tactical edge.
Alongside their use of specialized, proprietary communication systems, armed forces around the world are increasingly turning to adapted COTS (Commercial-off-the-Shelf) network solutions – especially those built on 3GPP specs – to reduce costs, expedite deployment timelines and support increasingly complex application scenarios. The U.S. DOD (Department of Defense) has recently published its strategy for deploying Open RAN-compliant private 5G networks at military installations in the United States and overseas territories.
- Supported by over $650 Million in funding over the past three years, several U.S. Army, Navy, Marine Corps and Air Force bases already host on-premise 5G infrastructure for both experimental and operational use. 5G private networks have been deployed at over 14 U.S. military bases to date.
- The Spanish Army and Navy have awarded multiple contracts – collectively worth $15 Million – to mobile operator Telefónica to supply standalone private 5G networks for army brigades on the move, armored systems and helicopter maintenance parks, naval bases, ships and marine infantry units.
- The Norwegian Armed Forces are utilizing a combination of defense-specific network slices and tactical private 5G networks to support their future mobile communications needs while the South Korean military is leveraging private 5G installations for smart naval base operations, runway safety management and XR (Extended Reality)-based training, including small unit tactics and firearm disassembly/assembly-related education.
-
The Jordanian Armed Forces and Ministry of Interior are jointly investing over $10 Million to deploy a hybrid TETRA-LTE communications system to support both narrowband voice and broadband data applications.
-
As part of the Qatar MoD’s (Ministry of Defense) LTE-5G program, the Signals Corps of the Gulf country’s armed forces has deployed a nationwide wireless network for mission-critical communications.
-
The ADF (Australian Defence Force) relies on private LTE and 5G-ready networks to support wireless broadband communications for live and synthetic military training environments.
-
The South Korean military is leveraging private 5G installations for smart naval base operations, runway safety management and XR (Extended Reality)-based training, including small unit tactics and firearm disassembly/assembly-related education.
-
The Japanese Ministry of Defense plans to deploy local 5G networks across JSDF (Japan Self-Defense Forces) military installations to digitize rear-area operations, such as base security, and reduce the burden on personnel.
-
The Brazilian Army and state-level military police forces have installed private LTE infrastructure in strategic locations to facilitate high-availability and reliable broadband communications.
- Other examples range from the ZNV (Deployable Cellular Networks) program of the Bundeswehr (German Armed Forces) to the ADF’s (Australian Defence Force) private LTE and 5G-ready networks for live and synthetic military training environments.
SNS Telecom & IT’s “Private 5G/4G Cellular Networks for Defense: 2024 – 2030” report predicts that global spending on private 5G and 4G LTE network infrastructure in the defense sector will grow at a CAGR of 21% over the next three years, collectively accounting for nearly $1.5 Billion between 2024 and 2027.
……………………………………………………………………………………………………………………………………….
Military bases hosting fixed and transportable (rapidly deployable) private 5G network assets include but are not limited to Naval Air Station Whidbey Island (Washington), Naval Base Guam, Joint Base Pearl Harbor-Hickam (Hawaii), Fort Carson (Colorado), Marine Corps Base Camp Pendleton (California), Marine Corps Air Station Miramar (California), Nellis Air Force Base (Nevada), Fort Hood (Texas), Fort Bliss (Texas), Joint Base San Antonio (Texas), Marine Corps Logistics Base Albany (Georgia), Tyndall Air Force Base (Florida), Camp Grayling (Michigan) and Fort Bragg (North Carolina), explained SNS Telecom & IT 5G research director, Asad Khan said in an email to Fierce Network. “We definitely expect more rollouts, particularly Open RAN-compliant networks in line with the DOD’s recently published private 5G deployment strategy,” Khan added.
For more information, please visit: https://www.snstelecom.com/defense
About SNS Telecom & IT:
SNS Telecom & IT is a global market intelligence and consulting firm with a primary focus on the telecommunications and information technology industries. Developed by in-house subject matter experts, our market intelligence and research reports provide unique insights on both established and emerging technologies. Our areas of coverage include but are not limited to 6G, 5G, LTE, Open RAN, vRAN (Virtualized RAN), small cells, mobile core, xHaul (Fronthaul, Midhaul & Backhaul) transport, network automation, mobile operator services, FWA (Fixed Wireless Access), neutral host networks, private 4G/5G cellular networks, public safety broadband, critical communications, MCX (Mission-Critical PTT, Video & Data), IIoT (Industrial IoT), V2X (Vehicle-to-Everything) communications and vertical applications.
References:
https://www.snstelecom.com/defense
FRMCS-Ready 5G/LTE Networks a $1.2 Billion Opportunity, Says SNS Telecom & IT
https://www.fierce-network.com/wireless/private-network-thats-lieutenant-network-you-soldier
SNS Telecom & IT: $6 Billion Private LTE/5G Market Shines Through Wireless Industry’s Gloom
SNS Telecom & IT: Private 5G Network market annual spending will be $3.5 Billion by 2027
SNS Telecom & IT: Q1-2024 Public safety LTE/5G report: review of engagements across 86 countries, case studies, spectrum allocation and more
SNS Telecom & IT: Shared Spectrum 5G NR & LTE Small Cell RAN Investments to Reach $3 Billion
SNS Telecom & IT: CBRS Network Infrastructure a $1.5 Billion Market Opportunity
SNS Telecom & IT: Private LTE & 5G Network Infrastructure at $6.4 Billion by end of 2026
SNS Telecom & IT: Open RAN Intelligent Controller, xApps & rApps to reach $600 Million by 2025
HPE Aruba Launches “Cloud Native” Private 5G Network with 4G/5G Small Cell Radios
HPE Aruba has launched an end-to-end private 5G network platform which is designed to help customers accelerate and simplify the deployment and management of private 5G networks, provide high levels of reliable wireless coverage across large campus and industrial environments, and open new, untapped use cases for private cellular. This integration follows HPE’s 2023 acquisition of private cellular technology provider Athonet.
Highlights:
- HPE Aruba Networking provides a comprehensive solution that removes the complexity of managing, deploying and purchasing enterprise private cellular networks.
- With this expansion of its secure edge-to-cloud portfolio, HPE Aruba Networking becomes the only global enterprise infrastructure vendor to provide comprehensive Wi-Fi and private 5G solutions.
- HPE Aruba Networking Enterprise Private 5G provides high levels of reliable wireless coverage across large campus and industrial environments, opening up new, untapped use cases for private cellular.
“Enterprise and industrial customers are increasingly seeking to deliver wireless coverage in demanding environments, including large outdoor areas, serving fast-moving clients, and providing deterministic access in dedicated spectrum,” said Stuart Strickland, wireless chief technology officer, HPE Aruba Networking.
“The complexity of conventional approaches to private cellular networks has held them back. Building on HPE Aruba’s networking history of wireless innovation and leadership, we have uniquely positioned ourselves to enable new applications for private cellular by integrating Athonet core cellular solutions with our traditional strengths in enterprise networking.”
With the debut of HPE Aruba Networking Enterprise Private 5G, enterprises can increase reliable, secure, high-performance connectivity with a fully integrated private 5G network that features:
- An end-to-end offering that includes a 4G/5G core, HPE ProLiant Gen11 servers, SIM/eSIM cards, 4G/5G small cells, and dashboard.
- New 4G/5G small cell radios from HPE that provide indoor/outdoor coverage, eliminating the need to integrate and use a separate management tool from a 3rd party vendor.
- Simplified cloud-native management and automation for subscriber management, deployment management, core monitoring and radio monitoring, with future plans for integration with HPE Aruba Networking Central.
- Expanded AI data capture and delivery for building AI data lakes and activating inference solutions.
- Interoperability with shared spectrum for private enterprise use: Citizens Broadband Radio Service (CBRS) spectrum in the US, and globally, where regulatory frameworks allow, beginning in 2025.
- Simplified configuration with pre-integrated, tested solution including everything needed to deploy an enterprise private 4G/5G network.
- Ability to deploy solutions in under 30 minutes with zero touch provisioning and configuration wizards that mask the 3GPP cellular complexity.
“HPE Aruba Networking Enterprise Private 5G is a significant step forward to solve for the complexity, cost, control, and management challenges associated with many private network deployments today,” said Patrick Filkins, Senior Research Manager, IoT and Telecommunications, IDC. “HPE Aruba Networking takes a grounded approach focusing on how to most efficiently integrate a private cellular network within an enterprise’s existing IT framework, streamlining network and device management through the use of familiar tools, as well as dynamically assigning and preserving device policy across 4G/5G, Wi-Fi, and wired LAN networks.”
“‘Many private network solutions are too complex, even for large enterprises with internal network expertise,” said Tom Rebbeck, Partner, Analysys Mason. “We expect customers to embrace solutions that can make private networks easier to deploy and manage.”
“For IronYun’s Vaidio Platform to be able to provide AI inferencing at the edge and drive accurate AI video search results, we needed an infrastructure that provided fast, available and reliable bandwidth without any complexity,” said Paul Sun, IronYun CEO. “We found it with HPE Aruba Networking, which provides us with all the components needed to deliver an end-to-end private 5G network for AI. HPE Aruba Networking’s private 5G network is the technical foundation for all Vaidio functions for real-time video analysis and AI inferencing that deliver AI insights to help improve security outcomes.”
“Private cellular, with its wide area, deterministic coverage, is the ideal fit for Disc Golf Network’s global live competition coverage of the Disc Golf Pro Tour,” said Baker Helton, DGPT Vice President of Business Administration. “The new HPE Aruba Networking Enterprise Private 5G offering will make it that much easier for companies to do what we’ve done and meet their requirements for pervasive coverage with an integrated offering using CBRS.”
5 Reasons to adopt HPE Aruba Networking Enterprise Private 5G
HPE completes acquisition of private 5G leader Athonet
HPE acquires private cellular network provider Athonet (Italy) to strengthen HPE Aruba’s networking portfolio
SNS Telecom & IT: Private 5G Network market annual spending will be $3.5 Billion by 2027