AI Debt Wave Implications: Higher interest rates with enormous AI sales required for ROI
Executive Summary:
Artificial Intelligence (AI) debt fueled infrastructure buildouts have become a broad fixed-income-market supply shock. The Wall Street Journal reports that 49% of new investment-grade bond issuance year to date in 2026 has been AI-linked—a figure that underscores how the financing of data centers, compute infrastructure and supporting power systems is reshaping bond market fundamentals and technical factors. As the supply of long-dated bonds rises, prices fall and yields rise until investors are compensated enough to absorb them. The AI buildout is adding enormous corporate debt from hyperscalers, data-center developers, semiconductor and networking suppliers, and utilities—while also driving public borrowing for grid, power, water and transportation infrastructure. This is putting upward pressure on yields across Treasuries, corporate bonds and municipal debt. This heavy concentration of long-dated supply creates a crowding-out effect that forces non-AI issuers to compete against elevated benchmark yields and potentially stifles broader economic growth, especially for companies not involved in circular AI funding deals (see References).
AI is capital intensive (see Table 1. below). Building data-center capacity requires cash not only for GPUs and servers, but also for land, buildings, fiber, networking, cooling, power procurement, backup generation, substations, transmission and water systems. The major hyperscalers can fund part of that investment from cash flow, but they are also issuing lots of new bonds and notes to preserve liquidity and accelerate buildouts. Their suppliers, data-center partners and power providers are doing the same. Much of this borrowing is long dated—exactly where the Treasury is issuing heavily to finance federal deficits.
The result is an expanding pool of long-duration debt competing for the same institutional buyers: insurers, pension funds, mutual funds, banks, foreign investors and asset managers. When those buyers do not increase their allocations at the same pace as supply, issuers must offer higher yields. Here’s the flow chart that loops around indefinitely until there is an AI crash!:
More AI related bond supply→lower prices→higher yields→higher term premium for U.S. Treasuries→higher budget deficits to finance the increased debt→more bond supply→etc.
……………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………….
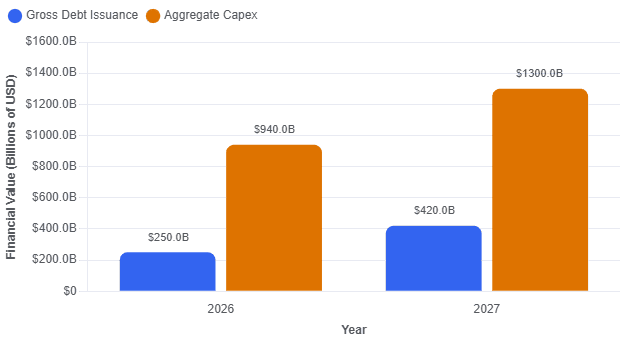
- 2026 Debt Issuance: Projected between $220 billion and $250+ billion for major US hyperscalers (Alphabet / Google, Amazon, Meta, Microsoft, and Oracle), with broader AI-related market debt reaching up to $570 billion.
- 2027 Forecast: Goldman Sachs projects direct hyperscaler debt issuance to nearly double to around $400 billion (Jeff Pu estimates $419 billion) as companies finance over a third of their infrastructure needs.
- Aggregate Capex: Combined capital expenditures are expected to hit roughly $940 billion in 2026 and scale past $1.3 trillion in 2027.
- Market Share: Hyperscaler investment-grade bond sales have jumped from roughly 2% of total US supply (2022–2024) to roughly 9% in 2026.
- Credit Impact: Credit spreads on a 10-year hyperscaler credit basket have widened from historical 40–75bp ranges toward 90bp+, driven by leverage concerns.
- Cash Flow Outlook: S&P Global Ratings expects all major hyperscalers to run negative free operating cash flow through 2026 and 2027, with a cash-flow inflection point not projected until 2028–2029.
Hyperscaler Funding Boom: Debt vs. Capex Projections (2026–2027):
Source: Google Gemini
……………………………………………………………………………………………………………………………………………………………………………………………………………………………………
Corporate Borrowing Negatively Impacted by AI Debt Financing:
Corporate bonds face the most direct effect. When hyperscalers, data-center operators, chip suppliers and utilities all enter the fixed income market at once, they compete for investor capital and dealer balance sheets.
The bond market adjusts through the following mechanisms:
- Larger new-issue concessions, meaning issuers must offer higher yields than comparable bonds already trading.
- Lower prices for outstanding corporate bonds as investors sell them to make room for new issues.
- Wider credit spreads, particularly for lower-rated investment-grade borrowers.
- Higher borrowing costs for non-AI companies that must compete with AI-linked supply for investor allocations.
The pressure is not limited to companies directly building AI agents or systems. A telecom operator, industrial firm, REIT or consumer company will likely pay more to borrow because investors can buy a new, liquid, highly rated hyperscaler bond at a potentially higher and attractive yield. That discourages non-AI corporate borrowing and leads to slower economic growth.
………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………
AI Pain Points Personified:
1. Ares reports, “We documented well more than 100 digital-infrastructure financings from just the past twelve months… Despite different issuers, different structures, different rating agencies and different credit markets, all of the risk converges on just eight (AI tech) names: Meta, Oracle, Microsoft, Amazon, Google, Nvidia, and, on a look-through basis, OpenAI and Anthropic.”
2. Analysts at Goldman Sachs Group and elsewhere have calculated that more than $1 trillion has already been spent on the data center build-out since the launch of ChatGPT in late 2022. Presumably, other large American businesses would need to pay for AI tools to justify all of this investment. That money needs to come from somewhere. but who’s going to pay for those AI tools?
3. From Greg Ip of the WSJ: “Will America Spend 9% of Its GDP on AI? The Industry Is Counting on It“:
“Is it plausible that Americans will spend as much of their income on this one technology as they do on food? Roughly twice what the nation pays for all forms of energy or all computers and software? Seven times what consumers spend on phone, streaming, and internet services combined?”
“You should be skeptical. Even the most transformative inventions eventually run into the law of diminishing returns: each additional dollar a user spends yields less additional productivity (or enjoyment) than the last. That imposes a natural ceiling. The question, of course, is where that ceiling is. Whether or not you think 9% of GDP is right, you have to care, because this figure isn’t some fever dream: it is implicit in the dollars that investors and companies are committing right now.”
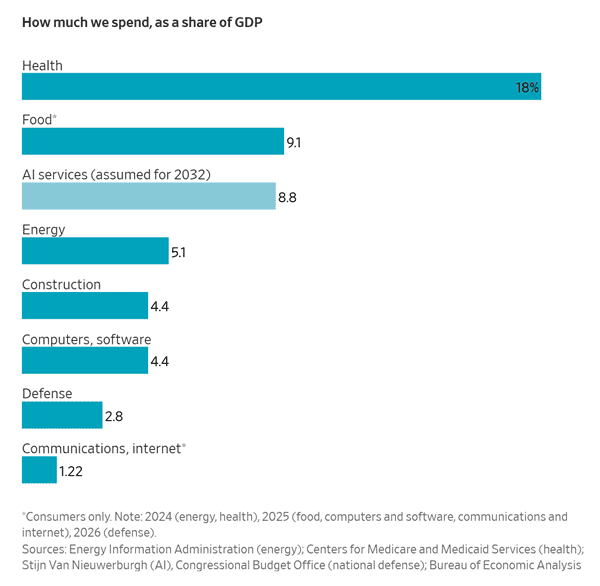
Chart Credit: Greg Ip, Wall Street Journal
………………………………………………………………………………………………………………..
Dire Warnings:
Nobel laureate Daron Acemoglu writes about “Distorted Intelligence at the AI Frontier” (emphasis added):
“The real problem for the frontier AI labs is not that their models are too powerful and already “misaligned” with the goals their creators set for them. Rather, it is that the models are being trained in ways that may be leading to a type of intelligence that will become less predictable. AI frontier labs are training their models in ways that may be leading to a type of distorted intelligence.
“This is what I mean by distorted intelligence. If my suspicion is correct, what we are dealing with is not a model racing toward superintelligence, but a brittle house of cards that becomes more and more likely to malfunction and collapse as we demand more from it.”
……………………………………………………………………………………………………………………..
References:
Curmudgeon: Caveat Emptor: Huge Debt and Circular Financing Deals Dominate AI Build-Outs (07/23)
Broadcom lending Anthropic up to $42 billion in yet another AI circular financing deal
Bain & Co: AI Infrastructure Buildout Will Require $6 Trillion Revenue by 2031 to Support Massive CAPEX
The AI Infrastructure Build-Out: A $10 Trillion Bet on Compute, Power, and Networks
Nvidia CEO Huang: AI is the largest infrastructure buildout in human history; AI Data Center CAPEX will generate new revenue streams for operators
AI risks and backlash increase; Recap of the circular loop of fake AI profits and hyperscaler markups of private AI companies
China vs U.S.: Race to Generate Power for AI Data Centers as Electricity Demand Soars
How will fiber and equipment vendors meet the increased demand for fiber optics in 2026 due to AI data center buildouts?
Expose: AI is more than a bubble; it’s a data center debt bomb
Will billions of dollars big tech is spending on Gen AI data centers produce a decent ROI?
Huge Risks for the proposed $500B AI Investments from Giant Wall Street firms
Can the debt fueling the new wave of AI infrastructure buildouts ever be repaid?