Optical Transceivers
Toshiba Wins UK Contract to Advance Commercial Quantum Networking: Can It Leverage Existing Optical Fiber Infrastructure?
Disclaimer: ChatGPT was used extensively to research and analyze the references cited in this article. The author provided editorial guidance and direction, reviewed the material, and is 100% responsible for the article’s final content.
…………………………………………………………………………………………………………………………………………………………………………………………………………………………………….
Introduction:
Toshiba Europe has been awarded a contract by Innovate UK, part of UK Research and Innovation (UKRI), to develop technologies intended to accelerate the commercial deployment of quantum networks. The Innovate UK-funded project targets scalable, multi-user quantum networks, but specialized Physical-layer requirements and deployment economics could limit their integration with conventional carrier optical networks. The project will focus on technologies for long-distance quantum links and multi-user quantum networks, with prototype subsystems evaluated under realistic operating conditions.
The contract was awarded through Innovate UK’s Enabling Commercial Quantum Networking competition, which supports UK companies developing components and subsystems for quantum networks. The competition represents a combined £20 million investment in the UK’s quantum technology ecosystem and aims to strengthen domestic capabilities across the emerging quantum networking supply chain.
The project supports the UK’s National Quantum Strategy, which includes an ambition to deploy advanced quantum networks at scale by 2035 and establish foundations for a future quantum internet. Such networks could eventually enable quantum information to be distributed among geographically separated quantum computers and other quantum systems.
Toshiba will develop and evaluate prototype subsystems designed to make quantum networks easier and more economical to expand using the UK’s existing optical fiber infrastructure. The work will investigate more efficient utilization of network resources and management of connectivity as the number of connected users and sites increases. Improved resource utilization could reduce infrastructure requirements and capital expenditures while making quantum networking services more accessible to telecommunications operators and customers.
UK network operators BT and Colt Technology Services will collaborate on validating the technology against practical network deployment and operational requirements.
Quantum networking and telecommunications infrastructure:
A significant longer-term application of quantum networking is connecting quantum processors located in separate data centers so that they can potentially work together on distributed computational tasks. Interconnecting quantum processors could expand the computational resources available to researchers and organizations and contribute to advances in areas such as pharmaceutical discovery and materials science. However, scaling quantum networks presents substantial engineering challenges. Unlike conventional optical communications, which transmit classical information using light, quantum networks must distribute and preserve fragile quantum states. This introduces requirements for specialized optical components, quantum-state management, synchronization and, ultimately, quantum repeaters capable of extending quantum communications over longer distances.
Integration with existing carrier fiber infrastructure is another important consideration. Network operators must address fiber loss, optical signal coexistence, routing, resource allocation and operational management while accommodating the specialized requirements of quantum communications.
One potential approach is to multiplex quantum and conventional data channels over the same optical fiber using wavelength-division multiplexing (WDM). This could avoid the expense of deploying entirely separate fiber networks. However, conventional optical signals can introduce noise and other impairments that degrade quantum channels. Raman scattering, optical power levels, fiber attenuation and losses introduced by multiplexers and other optical components all require careful engineering.
Furthermore, conventional optical amplifiers cannot simply be used to amplify unknown quantum states because of the quantum no-cloning principle. Quantum repeaters, which are needed to extend quantum communications over longer distances without relying on conventional amplification, remain a significant technology-development challenge.
Consequently, sharing existing fiber infrastructure does not necessarily mean that quantum networks can use conventional carrier optical equipment, transmission systems and operational procedures without substantial modification.
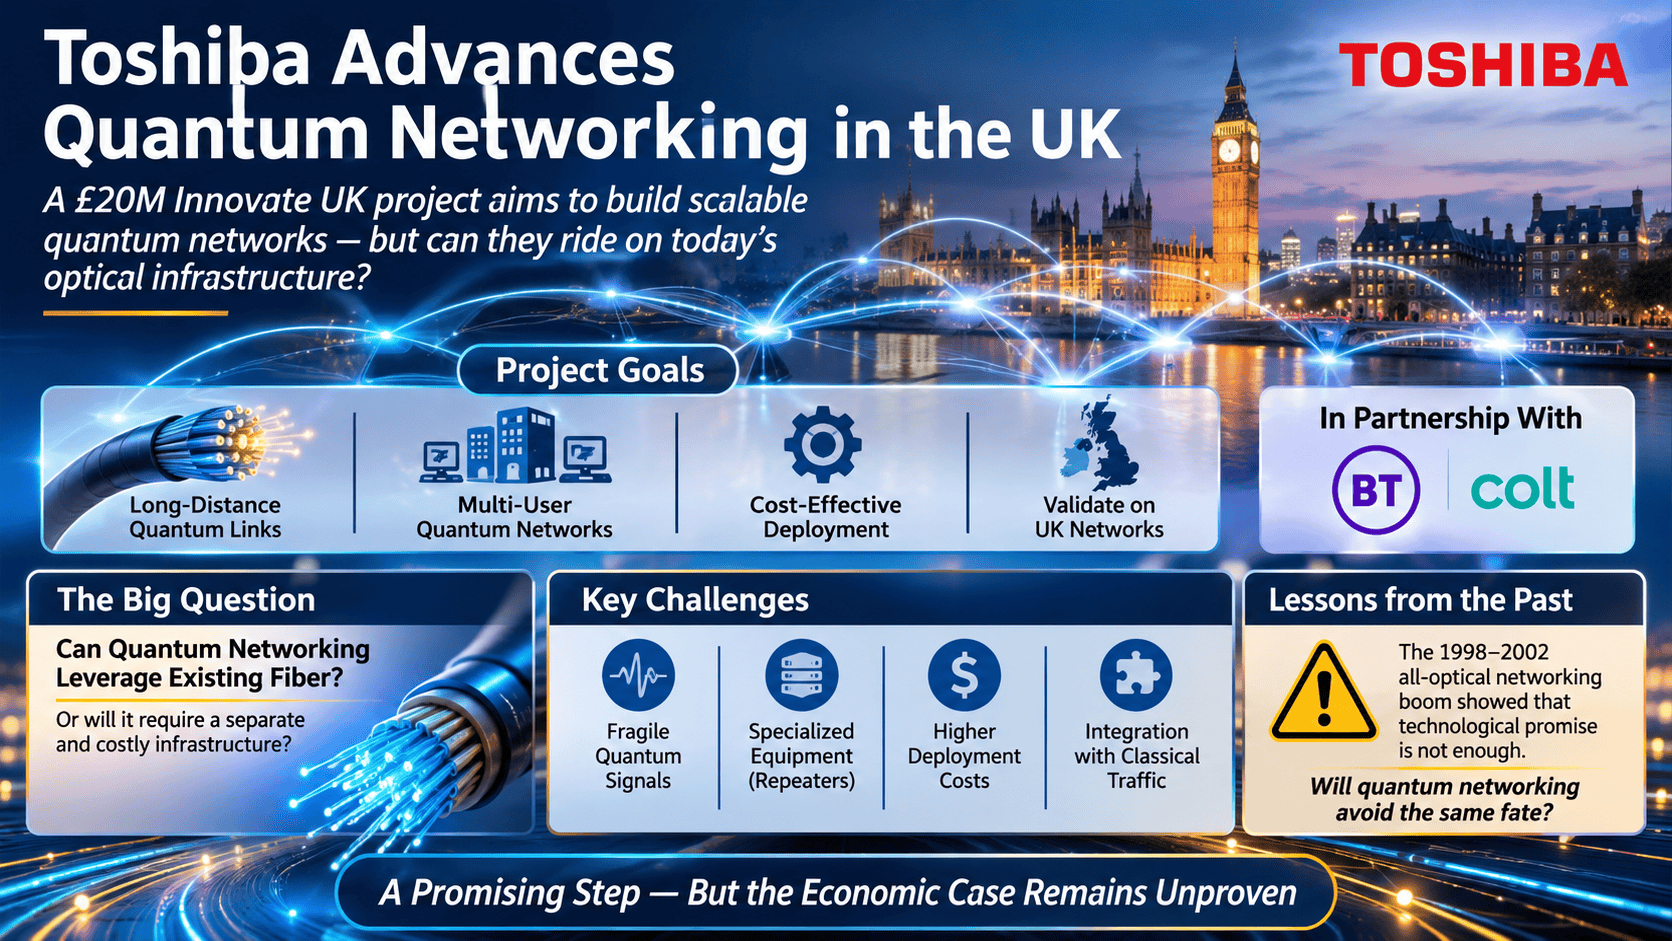
Image Created by ChatGPT
……………………………………………………………………………………………………………………………………………………………
Can quantum networking become an economically viable extension of carrier optical networks?
This is arguably the most important commercial question surrounding Toshiba’s project. The telecommunications industry has a long history of investing in promising optical networking technologies that did not achieve their anticipated commercial potential. During the 1998–2002 optical networking boom period, substantial investment went into photonic switching and all-optical networking. The vision was to eliminate repeated optical-electrical-optical (O-E-O) conversions, allowing data to remain in the optical domain throughout the network. That was supposed to usher in ultra-long-haul, repeater-less optical transmission. Photonic switches were expected to deliver enormous capacity improvements, reduce equipment complexity and lower network costs.
Despite considerable technical development and industry investment, all-optical switching did not become the dominant architecture envisioned by its proponents. Although optical circuit switches, MEMS-based photonic switches and ROADMs achieved commercial deployment in carrier networks, the broader vision of entirely photonic networking—with switching logic and control performed optically and without electronic processing—never became a commercially viable mainstream architecture. Conventional optical transport networks instead evolved through improvements in WDM, coherent optics, optical amplification, electronic switching and increasingly sophisticated optical-electrical-optical interfaces. The telecommunications industry ultimately favored hybrid optical-electronic networks.
Quantum networking could face a comparable commercialization problem. The ability to demonstrate quantum communication over existing fiber does not establish that a scalable, economically competitive carrier network can be built using conventional optical infrastructure.
There have been encouraging demonstrations of quantum and classical communications sharing the same fiber. For example, Toshiba and KDDI reported in March 2025 a demonstration carrying 33.4 Tbps of conventional data traffic alongside quantum key distribution (QKD) over an 80-kilometer fiber. This is an important proof of technical feasibility, but it does not establish the economics of a nationwide, multi-user quantum network.
There are also fundamental differences among quantum networking applications. QKD distributes cryptographic keys, while entanglement-based networking and distributed quantum computing require additional capabilities and substantially different performance characteristics. Success in multiplexing QKD with conventional traffic does not automatically demonstrate that geographically distributed quantum computers can be interconnected economically.
My assessment is that quantum networking is more likely, at least initially, to require specialized infrastructure and equipment than to become a straightforward extension of today’s carrier optical transport networks. Existing fiber may be reusable in selected applications, particularly metropolitan links and carefully engineered WDM deployments. But specialized quantum transmitters, detectors, synchronization systems, quantum memories, repeaters and associated control systems could impose substantial additional capital and operating expenses.
The economics become even more challenging when dedicated fiber, trusted intermediate nodes, environmental controls and specialized maintenance are required. Carrier operators will need to justify these costs against the actual revenue-generating applications and the alternatives available to customers.
The US and European quantum networking research communities have demonstrated that coexistence with conventional optical traffic is possible. Nevertheless, practical quantum repeaters, long-distance entanglement distribution, multi-vendor interoperability and scalable network management remain important obstacles.
It is therefore premature to assume that quantum networking will develop into a broadly deployed carrier service simply because existing fiber can be used in selected demonstrations.
The photonic switching experience of 1998–2002 is a useful cautionary precedent: technically impressive demonstrations and substantial R&D investment do not necessarily translate into commercially successful network architectures.
Toshiba’s quantum technology background:
The project builds on more than 25 years of Toshiba research and development in quantum technologies. The company recently introduced its Quantum-Safe Networking (QSN) Platform, designed to help organizations integrate quantum-safe protection into existing communications networks with reduced complexity, equipment footprint and cost.
It is important to distinguish these two technology areas. Quantum networking seeks to distribute quantum information and connect geographically separated quantum systems. Quantum-safe networking, by contrast, protects conventional communications against current and anticipated future cryptographic threats, including those posed by sufficiently powerful quantum computers.
Although related through their use of quantum technologies, these are distinct applications with different architectures, infrastructure requirements and deployment objectives.
Conclusions:
Toshiba’s collaboration with BT and Colt is a worthwhile technology-development effort addressing a genuine challenge: how to scale quantum networking without incurring the prohibitive cost of building entirely new fiber infrastructure. However, the critical test is not whether quantum signals can coexist with conventional data traffic over selected fiber links. It is whether the complete quantum networking architecture—including its specialized optical components, repeaters, control systems, maintenance requirements and operating costs—can deliver sufficient commercial value to justify deployment by telecommunications operators. Until that economic and technical case is demonstrated at meaningful scale, expectations for quantum networking as a natural extension of existing carrier optical infrastructure should remain guarded.
The historical lesson from the 1998–2002 photonic switching and all-optical networking boom is not that optical switching failed altogether. Rather, the ambitious vision of an entirely optical network, eliminating electronic switching and processing throughout the network, never materialized. Commercial optical switching did succeed, particularly at the wavelength and circuit layers, through technologies such as MEMS switches and reconfigurable optical add/drop multiplexers (ROADMs). However, electronic switching, processing and control remained essential components of commercial carrier networks. The industry ultimately adopted hybrid optical-electronic architectures rather than the fully photonic networks originally envisioned.
Quantum networking faces a similar commercialization challenge. Will it establish economically viable applications as a specialized extension of conventional optical networks, leveraging existing fiber wherever technically feasible? Or will its unique physical-layer requirements—including quantum repeaters, specialized transmitters and detectors, synchronization and stringent signal-management requirements—necessitate largely separate infrastructure with substantially higher deployment and operating costs? The ability to demonstrate quantum communications over existing fiber is encouraging, but does not establish that a scalable, commercially competitive carrier-network architecture is achievable. Ultimately, as with photonic switching, technical feasibility must translate into compelling economics and sustainable customer demand.
……………………………………………………………………………………………………………………………………………………………………………………………………………………
References:
Toshiba awarded contract to advance commercial quantum networking in the UK
UK Government – Quantum Key Distribution Research Report
https://www.gov.uk/government/publications/quantum-key-distribution-research-report/quantum-key-distribution-research-report
GSMA – Quantum Technologies and Telecom Use Cases (PDF)
https://www.gsma.com/solutions-and-impact/technologies/quantum-technologies/wp-content/uploads/2026/02/IG.19-Quantum-Technologies-Telcom-Use-Cases.pdf
CNAS – The Entanglement Edge (May 2026)
https://www.cnas.org/publications/reports/the-entanglement-edge
Nature – Quantum and Classical Coexistence over Hollow-Core Fiber
https://www.nature.com/articles/s41534-025-01125-7
ARCEP – Quantum Technologies and Their Impact on Networks (June 2026, PDF)
https://en.arcep.fr/uploads/tx_gspublication/futur-networks-briefing-note-quantum-technologies_june2026.pdf
PsiQuantum Targets AI Data Center Networks with Silicon-Photonic Optical Switching
2026 OCP Summit: Full-Stack AI Networking Silicon from Nvidia/Cisco and Broadcom; Ethernet vs InfiniBand Interconnects
Goldman Sachs report: Optical Networking is the next mega trend in AI infrastructure
2026 Fiber Connect Keynote: “The Future of Fiber Optics: AI and the Quantum”
IBM to Build World’s First Large-Scale, Fault-Tolerant Quantum Computer – Starling
Countdown to Q-day: How modern-day Quantum and AI collusion could lead to The Death of Encryption
Ultra-secure quantum messages sent a record distance over a fiber optic network
Google’s new quantum computer chip Willow infinitely outpaces the world’s fastest supercomputers
Quantum Computers and Qubits: IDTechEx report; Alice & Bob whitepaper & roadmap
Bloomberg on Quantum Computing: appeal, who’s building them, how does it work?
Impact of optical component shortages & bottlenecks explained + Hyperscaler’s CAPEX
LightCounting’s August 2026 market and component report highlights how severe physical supply shortages for high-speed optical components are reshaping data-center architectures and forcing cloud builders to expand their vendor pools from the traditional 2-3 suppliers up to 5-7 specialized hardware manufacturers. Qualifying and managing all of them is a new challenge.
- Applied Optoelectronics, Macom, and MaxLinear have already reported accelerating growth in Q2 2026 and we expect to see more examples in the upcoming earnings reports.
- Coherent and Lumentum have also reported improvements in growth rates for the last quarter, catching up with Eoptolink and Innolight (reporting at the end of August). Eoptolink has already disclosed a sharp increase in the profits expected for Q2. Accelink and CIG also report sharply higher profits.
- Tower Semiconductor reported triple-digit growth (y-o-y) in silicon photonics revenue in Q2-2026.
- GlobalFoundries plans to double its silicon photonics business in 2026.
- Cisco reported “a remarkable 28% y-o-y increase” in the networking segment revenues, up from 25% in Q1. Cisco reported three new hyperscale AI design wins and 40% growth in orders during the quarter. The company also reported record orders for campus networking – up 20% y-o-y.
- Arista Networks reported Q2 2026 revenue of $3.04 billion, marking its first-ever $3 billion quarter. This represented a roughly 38% year-over-year increase. Management also raised its full-year 2026 revenue growth outlook to 40%.
- Calix reported 21% y-o-y growth in Q2 and guided for another 15% in the current quarter. Growth in company’s revenue is attributed to sales of broadband equipment and AI-enhanced software to telecom operators.
- Extreme Networks reported 14% y-o-y growth in product sales, in part driven by success of its agentic AI networking platform.
Surging data-center traffic driven by AI queries has created acute optical component shortages, fundamentally altering supply chain qualifications for hyper-dense network switches and interconnects. The primary optical component bottleneck is a severe production shortage of Indium Phosphide (InP) laser chips and EML (Electro-Absorption Modulated Laser) components, which are failing to keep pace with a projected 53% surge in total optical transceiver and hardware demand, reaching $39 billion. Current demand for high-speed datacom optics is outstripping available supply by roughly 30%, forcing hyperscalers and system vendors to fundamentally restructure their supply chains. More details in the Addendum at the end of this article.
………………………………………………………………………………………………………………………………………………………………………………………………
Dell’Oro Group says that the rise of agentic AI and inference workloads is driving new demand and introducing network requirements that differ from those associated with training workloads. This shift is leading to significant expansion of front-end networks to support the broader buildout of AI infrastructure. We estimate that more than half of the growth in Front-end Data Center Switch sales over the next few years will be driven by AI-related opportunities. These deployments represent net-new expansion opportunities for both established vendors and new market entrants.
Accton, Arista, Celestica, Cisco, HPE/Juniper, H3C, Huawei, NVIDIA and others—emerge as the primary beneficiaries of this growth, according to the market research company.
“As AI infrastructure shifts from large-scale training to inference and agentic workflows, there is an increasing demand for general-purpose infrastructure, and expanded front-end network requirements,” said Sameh Boujelbene, Vice President at Dell’Oro Group. “The traditional assumption of a 10-to-1 ratio of XPU to CPU no longer applies across all deployments, with some environments moving closer to a 1-to-1 ratio. CPUs are becoming increasingly important for workloads orchestration and data movement. Additionally, networking for KV caching storage rack is also needed for inferencing applications,” added Boujelbene.
……………………………………………………………………………………………………………………………………………………………………………………….
As for the network providers/ISPs:
- Verizon announced a dark-fiber deal with Google to support the hyperscaler’s data center traffic growth. The deal is valued at over $1 billion and Verizon said there will be other deals announced before year-end.
- Deutsche Telekom said its AI factory for Germany’s public institutions and businesses that opened in February, has already sold the site’s 10,000 Blackwell GPUs capacity. DT is now looking at increasing capacity by another 20,000 GPUs.
- Comcast cites that its upstream broadband traffic is growing at 2.5x the rate of downstream data, which it links to AI-driven queries.
- AT&T is seeing rapid increases in large-scale data traffic requiring high-capacity metro and intercity fiber infrastructure.
Capex of Telecom Service Providers is still expected to be flat (or down 1%) in 2026, but AT&T and Comcast reported 16% and 20% y-o-y growth in capex for Q2, respectively. Both companies are investing more in broadband access. Verizon’s capex was also up, but only by 5% in Q2.
……………………………………………………………………………………………………………………………………………………………………………………….
Hyperscaler CAPEX:
The chart below illustrates the capital intensity of the TOP 4 Cloud companies. It is up sharply: Meta is already at 51% and Microsoft is at 46% in Q2. Oracle (not included in the figure) would have been off the chart at above 80% in Q1. The company reports earnings in early September and the key question is how it intends to finance future investments. Some moderation in spending growth is well needed. Amazon is the largest spender with $54.2 billion for the quarter, up 73% y-o-y. Amazon also increased guidance for 2026 capex from $200 billion to $220 billion.

Recent $ Trillion fundraising activities of Anthropic and OpenAI, supported by Nvidia, were widely covered yet both companies continue to lose money. Some financial experts refer to these activities as the “future for financial engineering.” Any innovation comes with some risk, but we all hope for the best.
………………………………………………………………………………………………………………………………………………………………………………………
Addendum: Optical Network Bottlenecks Explained:
-
- InP Epitaxial Production Limits: The primary physical constraint lies in the fabrication and epitaxy capacity for Indium Phosphide wafers used to build high-frequency lasers, where specialized manufacturing equipment (such as MOCVD systems) remains heavily backordered.
- Electrical Trace and Power Walls: Inside massive AI clusters, traditional pluggable optical modules face severe latency, thermal, and signal-integrity walls due to long copper electrical traces running from switch ASICs to the optical engine.
- Packaging and Testing Complexities: Shifting from legacy designs to dense 800G, 1.6T, and co-packaged optics (CPO) introduces intricate multi-die integration and hybrid bonding hurdles that slow down final module validation and packaging yields.
- Expanding Vendor Pools: Cloud builders are aggressively expanding their sourcing lists, moving from a concentrated pool of 2–3 legacy optical vendors out to 5–7 specialized component manufacturers to secure allocation.
- Ecosystem Pivot to Photonics: Major semiconductor players (such as Marvell’s acquisition of Celestial AI) and optical fabricators are pouring capital into silicon photonics and optical interconnect architectures to bypass standard copper and discrete laser constraints.
-
- Mechanism: LPO removes the power-hungry Digital Signal Processor (DSP) and clock/data recovery (CDR) chips directly from inside the optical transceiver module.
- The Fix: Raw, linear analog signals are driven straight from the switch or network interface card (NIC) ASIC.
- Benefits: Slashes module power consumption by 50% or more and cuts latency while preserving the hot-swappable, multi-vendor front-panel pluggable form factor.
- Trade-off: Requires host ASICs with advanced analog front-end and signal-equalization capabilities to process the raw electrical signals.
- Mechanism: CPO moves the optical engine (which converts electrical signals into light) off the front-panel cage and places it directly onto the same substrate or interposer as the switch or accelerator ASIC.
- The Fix: Electrical traces shrink from centimeters down to mere millimeters, completely bypassing lossy copper-clad circuit boards and high-power SerDes requirements.
- Benefits: Reduces optical-interface power consumption by up to 75% and maximizes bandwidth density for ultra-dense GPU scale-up fabrics.
- Trade-off: Reworks serviceability—if an optical engine fails, the repair domain shifts from a simple two-minute transceiver swap to board- or switch-level replacement
………………………………………………………………………………………………………………………………………………………………………
References:
Agentic AI and Inference to Supercharge Front-End Networks Growth, According to Dell’Oro Group
Networking chips and modules for AI data centers: Infiniband, Ultra Ethernet, Optical Connections
Goldman Sachs report: Optical Networking is the next mega trend in AI infrastructure
Cisco Execs: New “Network Supercycle” as Agentic AI Workloads Reshape Telecom Infrastructure
Cisco report: Agentic AI to reshape WAN traffic, AI inference will be ~25% of total traffic by 2035
Meta’s “Iris” AI Chip for MTIA: Implications for Telecom-Grade Optical Networking, DCI and High Capacity Ethernet Fabrics
Oriole Networks photonic networking platform to be integrated with AMD GPUs/CPUs for next-gen AI data center fabrics
Cheap Chinese AI Models: Unappreciated Threat to U.S. Hyperscaler AI Dominance
Oriole Networks photonic networking platform to be integrated with AMD GPUs/CPUs for next-gen AI data center fabrics
London, England based Oriole Networks today announced continued progress in its collaboration with AMD in support of the UK’s Advanced Research & Invention Agency (ARIA) Scaling Inference Lab. The initiative integrates Oriole’s photonic interconnect architecture with AMD Instinct GPUs and AMD EPYC CPUs to evaluate next-generation data center fabrics capable of addressing the performance, latency, and energy constraints inherent in large-scale AI workloads.
The multi-year collaboration is advancing toward deployment of what is positioned as the first production-scale, all-photonic AI network fabric. The system is designed to deliver ultra-low latency and deterministic transport characteristics at the system level, leveraging optical circuit switching to optimize east-west traffic flows across accelerator clusters. The primary objective is to demonstrate how optical interconnect technologies can support large-scale inference and distributed AI processing under stringent performance and energy constraints.
Oriole’s PRISM photonic networking platform [2.] replaces conventional electronic switching in the network core with nanosecond-scale optical circuit switching. In contrast to packet-switched electronic fabrics, this approach is intended to reduce forwarding overhead, lower core power consumption, and improve end-to-end transport efficiency for accelerator-dense workloads. AMD is contributing compute hardware and technical collaboration to support modeling and execution of large-scale network workloads relevant to frontier AI systems. However, PRISM is not built for any single chip vendor. It works across any accelerator platform, giving the wider industry a path to frontier-scale system-wide performance without the need for proprietary stacks.
Note 1. Oriole Networks is a photonic networking company, developing disruptive technologies for AI/ML and HPC networking that will revolutionize data centers. These technologies address AI’s biggest challenges – speed, latency, and sustainability. Our holistic approach replaces energy-hungry electrical switching with photonic switching. By using only light to move data in the network, our solution will increase the efficiency of LLM training and inference to unprecedented levels while dramatically reducing the energy consumption of data centers, currently putting a huge strain on energy grids. We can offer faster, more efficient, and more sustainable AI without sacrificing the planet.
Note 2. Oriole’s PRISM is a fully photonic network system designed to provide port-level, all-to-all connectivity, eliminating the need for electrical switches and dramatically reducing the number of optical transceivers needed in the network. This evolution greatly reduces power consumption and latency, increases bandwidth, and strengthens network resilience by eliminating single points of failure.

Image Credit: Oriole Networks
…………………………………………………………………………………………………………………………………………………………………………………………………………………………………………..
The deployment also represents the first commercial implementation of Oriole’s technology following an R&D-to-production transition completed in approximately three years. The company states that its xPU-agnostic architecture is intended to support heterogeneous accelerator environments and broader industry rollout beginning in 2027.
Photonic networking architecture:
PRISM is designed to route data optically rather than electrically, using photonic circuit paths in place of conventional electronic switching elements. As AI training and inference workloads scale, data center interconnect requirements increasingly exceed the efficiency limits of traditional switch-based architectures, particularly in terms of power dissipation, thermal load, and communication latency.
By eliminating electronic switching in the fabric core, the PRISM architecture seeks to reduce core network power consumption and limit buffering- and queuing-related delay. The use of optical circuit switching is consistent with ongoing industry interest in photonic interconnects, co-packaged optics, and optical disaggregation as potential enablers of high-density AI clusters.
The company reports that the architecture can substantially reduce GPU idle time and improve system-level utilization by shortening data movement paths between compute nodes. It also indicates potential reductions in cooling demand and associated water usage due to lower network power dissipation.
Quotes:
James Regan, CEO of Oriole, said: “A year ago, we were proving the physics; today, we’re proving the business. Our collaboration with AMD has moved from concept to deployment to a system an order of magnitude larger, and the data proves this is already driving performance increases at pace. This is what it looks like when photonic networking stops being a research curiosity and starts being the foundation of how serious AI infrastructure gets built. There’s a big problem now with electrical switches, which are basically bottlenecking AI traffic, and it’s going to get worse. What we do is we replace all the electrical switches.”
“AMD is excited to collaborate with Oriole on the ARIA Scaling Inference Lab cluster,” said Madhu Rangarajan, corporate vice president, Compute and Enterprise AI business, AMD. “Oriole’s AI backend networking with nanosecond optical circuit switching represents a fundamentally different way to connect accelerators at scale. We are helping to validate how photonic fabrics can work alongside AMD compute to deliver the low-latency, high-bandwidth connectivity that AI Inference workloads demand.”
“Meeting the demands for modern AI requires rapidly identifying ways to improve the performance and cost-efficiency of large-scale AI clusters. ARIA is thrilled to collaborate with Oriole and AMD to demonstrate the benefits of this new technology and it’s exactly the type of collaboration, between innovative startups and industry leaders, that the Scaling Inference Lab was designed to foster,” said Suraj Bramhavar, Program Director at ARIA
Standards and interoperability context:
From a standards perspective, photonic AI fabrics remain an active area of industry development rather than a fully mature architectural class. Relevant technical domains include IEEE 802.3 optical Ethernet interfaces, ITU-T optical transport frameworks such as G.694 and G.709, and ecosystem work in optical interconnect and co-packaged optics initiatives.
A vendor-neutral, accelerator-agnostic photonic fabric may be of interest to standards and industry groups evaluating future data center interconnect models for AI and high-performance computing. The Oriole–AMD collaboration therefore provides an early reference point for assessing the operational characteristics, integration constraints, and interoperability implications of optical circuit-switched AI infrastructure.
……………………………………………………………………………………………………………………………………………………………………………………………………………………….
References:
Oriole to Deploy World’s First AI System with Pure Photonic Network to Supercharge Data Centers
https://www.fierce-network.com/cloud/oriole-networks-pushes-pure-photonic-networking-ai-data-centers
NTT’s IOWN is (finally) evolving to an All Photonics Network (APN); Physics based AI for enterprise OT
Goldman Sachs report: Optical Networking is the next mega trend in AI infrastructure
Hyperscaler design of networking equipment with ODM partners
Technavio: Silicon Photonics market estimated to grow at ~25% CAGR from 2024-2028
2026 Fiber Connect Keynote: “The Future of Fiber Optics: AI and the Quantum”
Dr. Michio Kaku’s 2026 Fiber Connect keynote, “The Future of Fiber Optics: AI and the Quantum,” kicked off the inaugural AI & Emerging Technology Infrastructure Summit on Wednesday, May 20,2026.

As a theoretical physicist and futurist, Dr. Kaku delivered a high-altitude roadmap framing fiber optic networks not merely as faster telecom pipes, but as the mandatory foundation for a world defined by concurrent, multi-cloud AI infrastructure and quantum mechanics.
Kaku described the convergence of AI, quantum computing, and fiber infrastructure as a critical shift toward an AI-native, quantum-enabled internet essential for national competitiveness. Kaku emphasized that fiber optics are necessary to facilitate “quantum AI” by handling high-density, low-latency data movement, moving beyond traditional networking to support exponential computing advancements.
Key Takeaways:
- Fiber as the Foundation for AI: Dr. Kaku explained that massive data sets and hyperscale AI computations cannot run efficiently over wireless or legacy networks. Fiber’s near-limitless bandwidth and sub-millisecond latency are required to process these workloads in real-time.
- The Quantum Computing Leap: He detailed how quantum networks—which compute at the atomic level—will redefine security and processing power. He emphasized that quantum data requires the stability, security, and bandwidth that only fiber optics can provide.
- National Competitiveness: Dr. Kaku framed fiber broadband as a strategic national asset. He argued that a region’s ability to evolve into an AI-native economy depends directly on robust fiber infrastructure to secure future healthcare, financial, and climate innovations.
- The “Thinking Economy”: He projected that networks are evolving to do more than just transport data. They will increasingly support “thinking economies” where intelligence moves instantly between edge computing centers, end-points, and the cloud.
The presentation and subsequent fireside chat with quantum computing firm IonQ offered several critical technological dimensions and actionable industry analysis:
The Physics of the “AI Triad” (Compute, Quantum, & Photonics):
Kaku mapped out how classical silicon-based computing is approaching its physical limits (thermodynamics and transistor gating). He explained that the future relies on a three-pronged convergence:
-
- AI Models: The brain processing the logic.
- Quantum Computing: The hyper-accelerator solving atomic, chemical, and multi-variable optimization issues.
- Optical Fiber: The unified nervous system. Quantum and distributed AI workloads cannot scale on traditional copper networks because they require absolute determinism, zero-jitter latency, and near-limitless bandwidth.
Upgrading to a Quantum-Ready Internet:
Drawing from themes in his book Quantum Supremacy, Kaku noted that the move toward a quantum-enabled web alters the physical network topology. Operators must plan for physical security layers (like Quantum Key Distribution) and data transmission methods that preserve quantum entanglement across distances.
–>Fiber is the only media capable of transporting light photons over vast geographies without disrupting these states.
The Power and Cooling Crisis:
A significant focus of the analysis was the staggering energy footprint of next-generation AI factories and hyper-scale data centers. Kaku noted that moving data electronically creates heat resistance. Shifting toward all-optical (photonic) networks and in-rack fiber interconnects removes electronic bottlenecks, drastically reducing the power required to pass massive datasets between distributed data centers
Strategic Implications for Network Operators:
During the fireside chat, the discussion moved from theoretical physics to immediate business strategy and tactics:
-
- National Competitiveness: Bandwidth, latency, and optical infrastructure are the new benchmarks for a country’s economic power.
- Capacity Planning: Network planners must shift from estimating consumer download speeds to calculating the throughput required for real-time, stateful AI agents and machine learning inference workloads operating at the network edge.
FBA Panel and Summit Sessions:
Following Kaku’s opening address, the Fiber Broadband Association (FBA) hosted deep-dive industry panels that put these physics concepts into operator terms:
- The Open Compute Project (OCP): Discussed open-source hardware standards for in-rack photonics to support massive AI clustering.
- Multi-Data-Center Architectures: Network engineers mapped out how dense dark fiber rings are being laid to link secondary edge facilities, allowing enterprises to run heavy inference closer to end-users without overwhelming backbone networks.
- AI data center speed and power requirements are transitioning towards 800 Gbps–1.6 Tbps node-to-node networking and gigawatt-scale power to handle distributed generative AI workloads.
- High rack densities up to 240 kW require advanced liquid or immersion cooling, with optical technologies being introduced to reduce heat generation.
…………………………………………………………………………………………………………………………………..
References:
https://fiberconnect.fiberbroadband.org/about/whats-new/
Analysis: Fiber Broadband Association (FBA) whitepaper: Upgrading MSO Networks to Fiber to the Home (FTTH): A Technical Perspective
Fiber Broadband Association Middle Mile WG: how to use “Digital Infrastructure Networks” for coordinated fiber backbone investments
Analysis: AT&T 1Q-2026 results: increased fiber penetration, FWA momentum, D2D deals, and mobile/home internet bundles
Fiber Optic Boost: Corning and Meta in multiyear $6 billion deal to accelerate U.S data center buildout
Fiber Optic Networks & Subsea Cable Systems as the foundation for AI and Cloud services
How will fiber and equipment vendors meet the increased demand for fiber optics in 2026 due to AI data center buildouts?
Automating Fiber Testing in the Last Mile: An Experiment from the Field
AI wireless and fiber optic network technologies; IMT 2030 “native AI” concept
Dell’Oro: Optical Transport Systems market +15% year-over-year in 3Q2025 driven by Cloud Service Providers
Dell’Oro Group recently published its 3Q25 Optical Transport report, highlighting continued strength in the market as demand accelerates across customer segments and technology areas. Below is a summary of the key findings from this latest research.
The Optical Transport Systems market increased by 15% year-over-year (Y/Y) in 3Q2025, driven by robust demand across all major customer groups and technology segments. The most significant growth was seen in Cloud Service Providers (CSPs) which grew +58% Y/Y and the DWDM Long Haul segment which grew +24% Y/Y. Direct sales for data center interconnect (DCI) continued to be the driving application for optical transport equipment sales, growing 34% Y/Y. Non-DCI also performed well, rising 7% Y/Y, driven by increased spending by communication service providers (CSPs).
In the first nine months of 2025, two vendors—Ciena and Nokia—gained more than one percentage point of market share. Other vendors that gained some market share included 1Finity, Adtran, Cisco, and Smartoptics. Note that Nokia acquired Infinera -a fiber optic equipment company on February 28, 2025.

Image Source: Jimmy Yu, Dell’Oro Group
The Dell’Oro Group Optical Transport Quarterly Report offers complete, in-depth coverage of the market with tables covering manufacturers’ revenue, average selling prices, and unit shipments (by speed up to 1.6 Tbps). The report tracks DWDM long haul, WDM metro, multiservice multiplexers (SONET/SDH), data center interconnect (metro and long haul), disaggregated WDM systems, and IPoDWDM ZR/ZR+ Optics. To purchase this report, please contact us at [email protected].
…………………………………………………………………………………………………………………………………………………………………………………………
Backgrounder:
- Optical Transceivers: Convert electrical signals into optical signals for transmission over fibers, and vice versa, at the endpoints of a link.
- Wavelength Division Multiplexers (WDM/DWDM): Devices that combine multiple optical signals (each on a different wavelength) into a single fiber for transmission, and separate them at the receiving end, maximizing fiber capacity.
- Optical Add/Drop Multiplexers (OADMs): Allow specific wavelengths (channels) to be added or removed from a fiber link at intermediate points in the network without interrupting the other channels.
- Optical Cross-Connects (OXCs) / Optical Switches: Used to route optical signals from one incoming fiber to a different outgoing fiber in the optical domain, often used in core networks.
- Regenerators / Optical Amplifiers (EDFAs): Used to amplify or regenerate optical signals over long distances to maintain signal strength and quality.
- OTN Terminal Equipment / Muxponders & Transponders: These devices package client signals (like Ethernet, Fibre Channel, or even SONET/SDH signals) into the standard OTN frame format (ITU G.709) for efficient transport.
- SONET/SDH: These are legacy, connection-oriented, circuit-switched technologies originally designed for carrying voice traffic in North America (SONET) and globally (SDH). They operate at the physical layer (Layer 1) and use Time Division Multiplexing (TDM).
- Usage: They are still widely deployed in existing network infrastructure, especially where high reliability and stringent latency requirements for legacy TDM services are necessary.
- OTN: OTN (ITU-T G.709 standard) is the modern successor, designed to combine the management and protection capabilities of SONET/SDH with the bandwidth efficiency of WDM.
- Usage: OTN has largely replaced SONET/SDH in new core and metro networks due to its ability to transparently carry multiple types of traffic (Ethernet, IP, Fibre Channel, and SONET/SDH frames) over a single, high-capacity infrastructure. It offers enhanced performance monitoring, Forward Error Correction (FEC) for longer reach, and greater scalability.
- Huawei has consistently maintained a leading position in the global optical networking market.
- Ciena is a major leader, particularly in North America (holding nearly 50% share in the U.S. market) and among cloud providers, benefiting from strong demand for its WaveLogic 6e and 400ZR/ZR+ solutions.
- Nokia has significantly strengthened its position, becoming the second-largest optical networking vendor globally (with approximately 20% market share) following its acquisition of Infinera in February 2025. The combined company saw substantial growth in revenue from cloud customers.
- Cisco saw a 31% increase in revenue from cloud operators in Q2 2025, a key driver of market growth.
- ZTE and FiberHome are also among the top six, often noted for their competitive solutions in global and emerging markets.
- Excluding sales into China, the leading vendors are Ciena, Huawei, Nokia, Infinera (now part of Nokia), and Fujitsu, accounting for around 80% of that specific market segment.
References:
Optical Transport Market Surges 15% in 3Q25, According to Dell’Oro Group
Dell’Oro: Optical Transport market to hit $17B by 2027; Lumen Technologies 400G wavelength market
LightCounting: Q1 2024 Optical Network Equipment market split between telecoms (-) and hyperscalers (+)
Highlights of LightCounting’s December 2023 Quarterly Market Update on Optical Networking
Dell’Oro: Optical Transport Market Down 2% in 1st 9 Months of 2021
Dell’Oro: Optical Transport Equipment Market Stagnant in 1Q 2021; Jimmy Yu’s Take
Dell’ Oro: Huawei still top telecom equipment supplier; optical transport market +1% in 2020
AI infrastructure investments drive demand for Ciena’s products including 800G coherent optics
Artificial Intelligence (AI) infrastructure investments are starting to shift toward networks needed to support the technology, rather than focusing exclusively on computing and power, according to Ciena Chief Executive Gary Smith. The trends helped Ciena swing to a profit and post a 24% jump in sales in the recent quarter.
The company enables high-speed fiber optic connectivity for telecommunications and data centers, helping hyper-scalers such as Amazon and Microsoft support AI initiatives via data center interconnects and intra-data center networking. Currently, the company is ramping up production to meet surging demand fueled by cloud and AI investments.
“There’s no point in investing in these massive amounts of GPUs if we’re going to strand it because we didn’t invest in the network,” Smith said Thursday.
……………………………………………………………………………………………………………………………………………………..
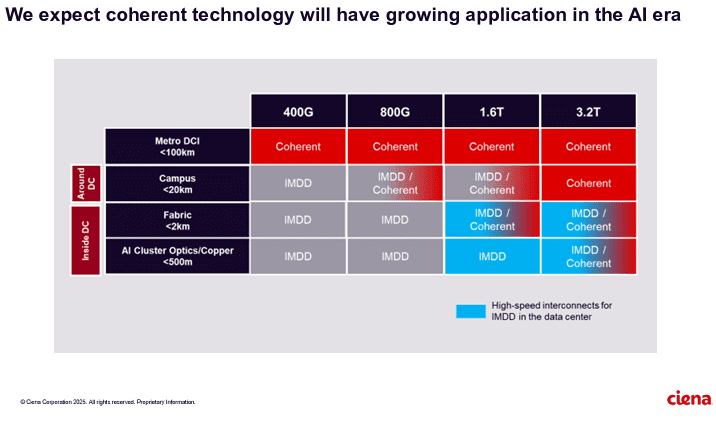
Ciena sees a bright future in 800G coherent optics that can accommodate AI traffic. Smith said a global cloud provider has selected Ciena’s coherent 800-gig pluggable modules and Reconfigurable Line System (RLS) photonics for investing in geographically distributed, regional GPU clusters. “With our coherent optical technology ideally suited for this type of connectivity, we expect to see more of these opportunities emerge as cloud providers evolve their data center network architectures to support their AI strategies,” he added.
It’s still early innings for 800G adoption, but demand is climbing due to AI and cloud connectivity. Vertical Systems Group expects to see “a measurable increase” in 800G installations this year. Dell’Oro optical networking analyst Jimmy Yu noted on LinkedIn Ciena’s data center interconnect win is the first he’s heard of that involves connecting GPU clusters across 100+ kilometer spans. “It was a hot topic of discussion for nearly 2 years. It is now going to start,” Yu said.
……………………………………………………………………………………………………………………………………………………
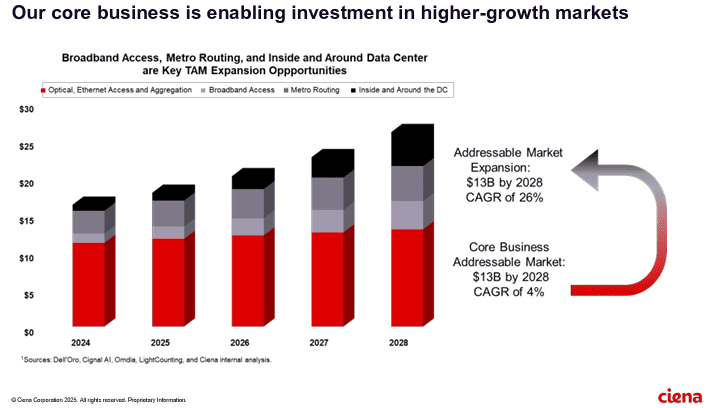
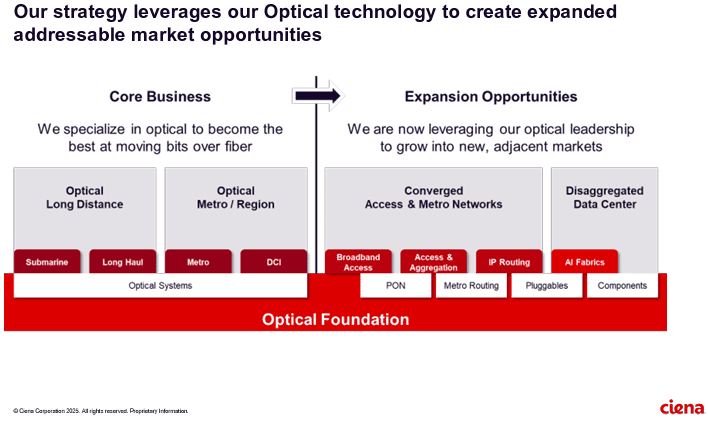
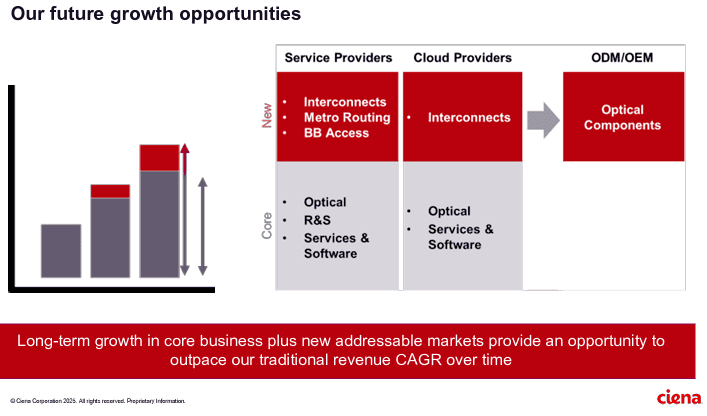
Ciena’s future growth opportunities include network service and cloud service providers as well as ODM/OEM sales of optical components.
References:
https://www.wsj.com/business/earnings/ciena-swings-to-profit-as-ai-investments-drive-demand-0195f30c
https://investor.ciena.com/static-files/d964ccac-74b3-43d9-a73e-ecf67fab6060
https://www.fierce-network.com/broadband/ciena-now-expects-tariff-costs-10m-quarter
Quintessent: Supporting “newer AI workloads” with lasers and DWDM
Integrated-photonics companies have increasingly seized on the opportunities in advanced AI. Many are building high-speed optical interconnects for data centers, with the electrical–optical conversion as close as possible to the number-crunching GPU or application-specific integrated circuit (ASIC).
However, Goleta, CA based startup Quintessent, is focusing on solving what it says is a major bottleneck hindering commercial deployment of such high-speed optical interconnects for AI – the light source or laser, which is currently the “weakest link” in system reliability and scalability, according to co-founder and CEO, Alan Liu.
Quintessent’s answer lies in part in its laser technology, incorporating quantum dots (QDs)—the semiconductor nanocrystals celebrated in the 2023 Nobel Prize in Chemistry—and multiwavelength comb lasers. The firm believes that combination can boost bandwidth, improve efficiency and cut latency by enabling highly parallel dense wavelength-division multiplexed (DWDM) optical links for computing clusters and data centers. And in late March, the company announced that it had secured US$11.5 million in new seed funding to push its vision closer to commercialization.
Quintessent was co-founded in 2019 by Optica Fellow John Bowers of the University of California, Santa Barbara (UCSB), USA, who serves as the company’s board chairman, and Liu, formerly a student in Bowers’ lab. In a conversation with OPN in November 2023, Liu noted that his Ph.D. work in the lab, which spanned the years from 2011 to 2017, focused on what he called “one of the glaring holes in silicon photonics”: how to integrate the light source. His work specifically involved integration of QD lasers with silicon photonics, which subsequently became “one of the core technologies for Quintessent.”
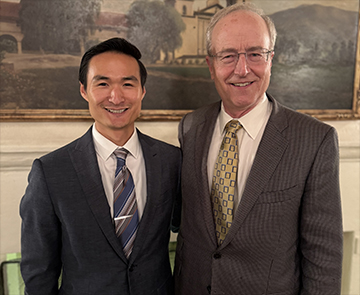
Quintessent co-founders Alan Liu (left) and John Bowers. Image: Courtesy of A. Liu.
Even at that time, Liu had some stirrings in the direction of commercializing the technology. Ultimately, though, after earning his Ph.D. in 2017, he left Santa Barbara for a two-year stint at a consulting firm in the Washington, DC, area. There, he worked as a subject-matter expert in photonics on projects for the US Department of Defense’s advanced-research arm, DARPA, and the US Department of Energy’s counterpart, ARPA-E.
Still, the entrepreneurial itch never quite left Liu. Nor did his fascination with the promise of QD laser technology, as he saw subsequent work done in Bowers’ lab to further advance the performance of those lasers and demonstrate new functions with them, including multiwavelength comb sources.
In 2019, Liu says, he got a call from Bowers, who noted that he was seeing “a lot of interest” from industry in the technology the lab was developing, but that there was “no company to sell it.” When Bowers asked if he wanted to help start one up, Liu recalls, “it didn’t take me long to sign on and say yes.” In the course of the next few years, they built Quintessent’s core team, drawing on numerous other contacts both within and outside of Bowers’ UCSB lab, and pulled in a mix of government R&D and venture funding, including the $11.5 million seed round announced in March 2024. The business case for Quintessent, Liu says, rests largely on “some of the newer AI workloads that were coming into the fray” beginning in the late 2010s, and their immense appetite for computing resources and power.
“If you’re going to be optimizing for power efficiency and bandwidth and latency, the required architecture is one that’s wide and parallel,” he explains. And for optics, at some point, trying to achieve that level of parallelism by adding more and more spatial or fiber channels becomes unwieldy.
The alternative solution, Liu says, is a highly parallel DWDM architecture—using not lots of fibers but “lots of lambdas.” For the crushing workloads of advanced AI, DWDM is optimal, as it “allows you to both simultaneously optimize bandwidth and minimize power and latency,” without relying on digital signal processing or a potential rat’s nest of individual fiber interconnects to boost overall bandwidth.
One key for achieving that vision was “enabling a new kind of laser, and using that laser to enable new communication and transceiver architectures,” according to Liu. “That was a common gap I saw across the industry.” Particularly in the context of AI, Liu observes, a big argument for better lasers has to do with reliability.
Particularly in the context of AI, Liu observes, a big argument for better lasers—and especially for Quintessent’s concept of simplifying wavelength scaling using multiwavelength comb sources fabricated from InAs/GaAs QD material—has to do with reliability. “Optical solutions for AI are going to have to be at least an order of magnitude more reliable than what we see today in existing transceivers,” he maintains. “If you imagine a scenario where there’s 10 times more optics deployed, and your failure rates stay the same, then you’ve got 10 times more failures you’re asking the customer to deal with. That gets a little dicey.”
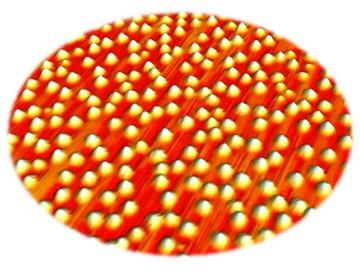
An atomic force microscopy (AFM) image of InAs/GaAs quantum dots. Image: Courtesy of A. Liu
Getting to better overall reliability will require much more reliable lasers, Liu believes, as lasers are “kind of the weakest link at the moment.” And he and the Quintessent team think that QD lasers offer a way forward, as they are “intrinsically more reliable than quantum well materials today.”
Tobias Egle, a materials scientist who works with M Ventures, one of the partners in the most recent Quintessent funding round, explained the difference further in a separate call with OPN. “These QD lasers are not as affected by material defects, dislocations and so on,” Egle says. “Simply put, a single dislocation through the facet or active region of a traditional laser can lead to complete failure. In contrast, when you have billions of QDs which are independent of one another, the presence of a single dislocation has a negligible impact on your overall performance.”
Quintessent experienced a milestone a year ago, when the company and Tower Semiconductor—the Israel-based global foundry firm with which Quintessent had partnered since 2021—announced that they had achieved what they called the world’s first heterogenous integration of GaAs quantum dot lasers in a commercial foundry silicon photonics process. The pair also unveiled a foundry silicon platform, PH18DB, targeted for the telecom and datacom optical transceiver market, and an accompanying process development kit (PDK).
Meanwhile, on the funding side, Quintessent announced an oversubscribed US$11.5 million seed round in March 2024, with an investment group led by Osage University Partners (OUP) and including, in addition to M Ventures, participation by previous Quintessent funders Sierra Ventures, Foothill Ventures and Entrada Ventures. In a press release accompanying the recent funding announcement, Liu said the new money would let the company “grow our team and accelerate the development of highly scalable and highly reliable optical interconnects that transcend the scaling limitations of incumbent solutions,” based on the firm’s core technology of QD-enabled multiwavelength comb lasers.
Operationally, Liu told OPN that—having “checked off all of the fundamental technology questions” regarding the laser technology’s feasibility—Quintessent is now focused on optimizing the laser design, which he calls “a key Lego block,” and of other pieces of the overall architecture to validate system-level functionality. Then, an important next step will be getting chips into customers’ hands for ground-truthing and feedback, and using that feedback to “drive forward the commercialization roadmap.”
“So samples, then low-volume pilots, then high-volume manufacturing—simple, right?” he laughs. Liu seems exhilarated by the challenge. “I’m one of those people that liked to play video games in the hard, hard mode,” he says. “If it’s too easy, you don’t get much enjoyment out of it.”
References:
https://www.optica-opn.org/Home/Industry/2024/April/Quintessent_Targets_Lasers_for_AI
Co-Packaged Optics to play an important role in data center switches
Ranovus Monolithic 100G Optical I/O Cores for Next-Generation Data Centers
Dell’Oro: DWDM equipment market to exceed $17 billion by 2026
LightCounting: Optical Ethernet Transceiver sales will increase by 40% in 2024
LightCounting expected sales of Ethernet optical transceivers to decline by 5-10% in 2023, but surging demand from Google and Nvidia kept the market growing, albeit at single digits.
Sales of Optical Ethernet transceivers declined in 2019 as a result of lower spending by the Cloud companies, which now dominate demand for those parts. Cloud companies reduced their spending again in the end of 2022 and the market outlook was dire in early 2023. Yet, one year later the market has bounced back.
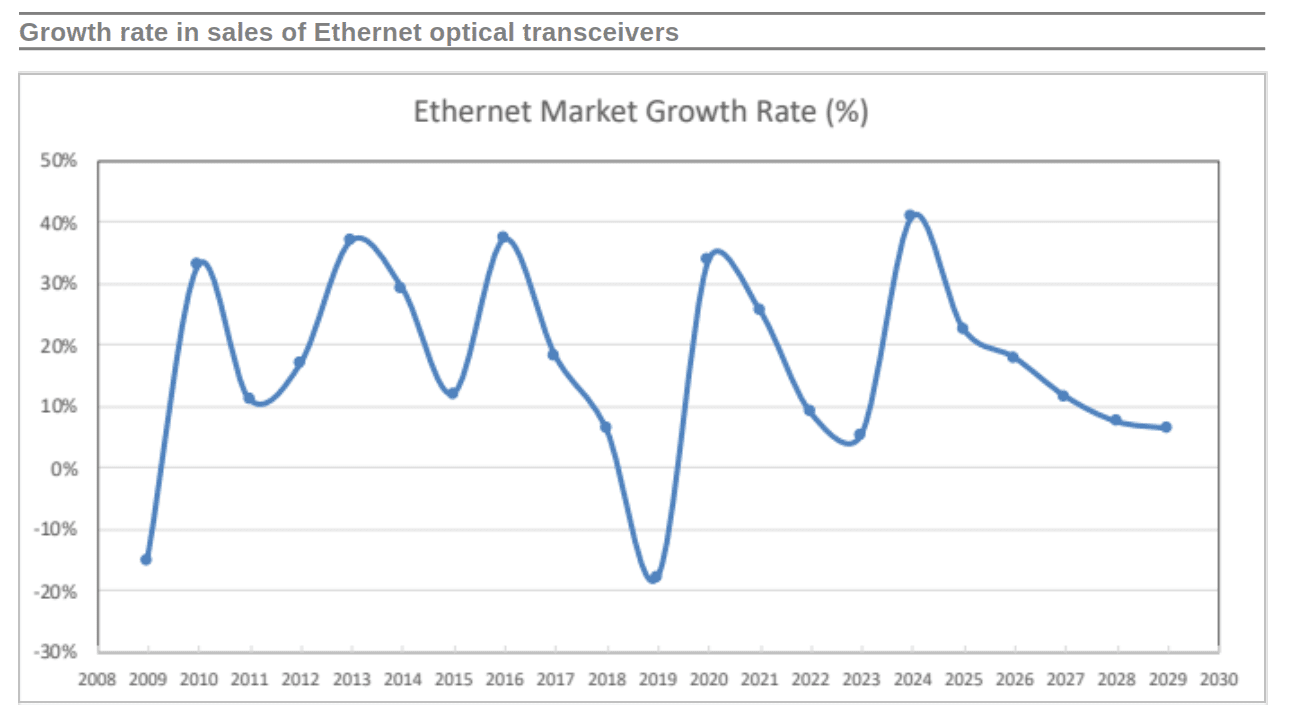
The market research firm has sharply increased their forecast for sales of 400G/800G transceivers and now expect: 40% growth in 2024, more than 20% in 2025 and double digit growth in 2026-2027, as illustrated in the figure below.
Source: LightCounting
………………………………………………………………………………………………………………….
The growth will not continue indefinitely. Any slowdown in purchases of optics by Nvidia or Cloud companies can reverse the market dynamics. Timing of such a decline is unpredictable. All we know, it will happen at some point. Our model suggests a soft landing with single digit growth rates in 2028-2029, but it is more likely that we will see another sharp drop followed by a recovery, conforming to the rocky history of the past 15 years.
Fears of an economic recession have subsided, but they continue to weigh on spending of telecom operators, which see no revenue growth. Yet, we will not know for sure if a recession is coming until it actually starts and it will take another half a year after that for the economists to formally declare it. By that time, we will be busy discussing the timing of a recovery.
What remains certain is that optics are critical for data centers and for the rest of the global networking infrastructure. Recent progress in generative AI makes the future even more exciting. Keep this in mind, while navigating the markets volatility as shown in the above graph.
……………………………………………………………………………………………………………….
About LightCounting:
The market research firm was established in 2004 with an objective of providing in-depth coverage of market and technologies for high speed optoelectronic interfaces employed in communications. By now, the company employs a team of industry experts and offers comprehensive coverage of optical communications supply chain.
……………………………………………………………………………………………………………….
References:
https://www.lightcounting.com/report/march-2024-ethernet-optics-287
https://www.lightcounting.com/report/march-2024-quarterly-market-update-288
Highlights of LightCounting’s December 2023 Quarterly Market Update on Optical Networking
LightCounting: Sales of Optical Transceivers will decline in 2023
LightCounting: Optical components market to hit $20 billion by 2027+ Ethernet Switch ASIC Market Booms
Highlights of LightCounting’s December 2023 Quarterly Market Update on Optical Networking
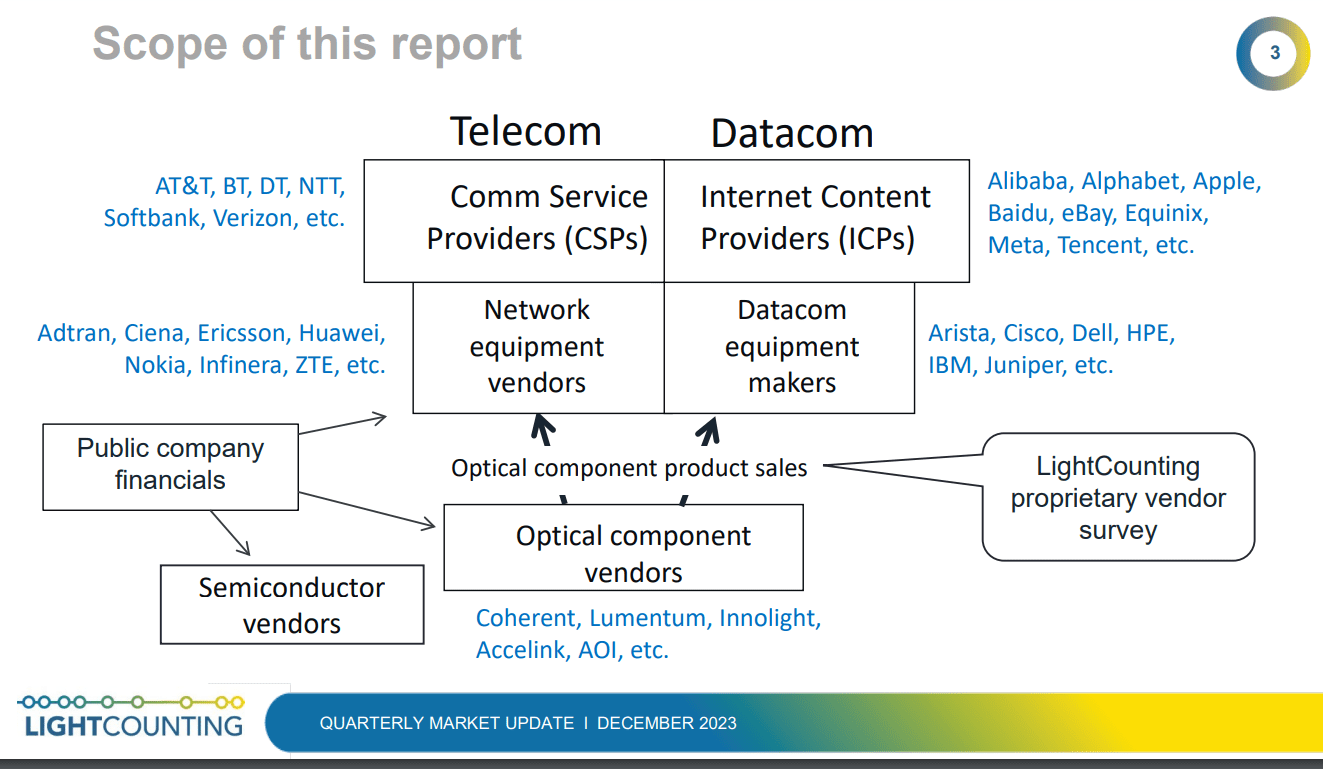
LightCounting’s Quarterly Market Update report [1.] for Q3 2023 revealed that the optical communications industry financial results were disappointing.
Every financial market indicator that the market research firm tracks – ICP (Integrated Communications Provider) and CSP (Communications Service Provider) capex, datacom and networking equipment, and semiconductor (x-Nvidia) and optical components sales – all had negative growth compared to Q3 2022.
Note 1. LightCounting’s Quarter Market Update reports are designed to provide an easy-to-digest snapshot of optical transceiver growth trends, backed up by detailed quarter-by-quarter sales data collected via LightCounting’s proprietary vendor survey. Performance metrics and commentary for top-tier telecom and internet service providers, network and datacom equipment makers, and optical component and semiconductor vendors are also included to provide an understanding of what drives sales trends at the transceiver level.
- Alphabet and Microsoft had record capital expenditures.
- Arista, Broadcom, Calix, Innolight, and Nvidia all reported record revenues.
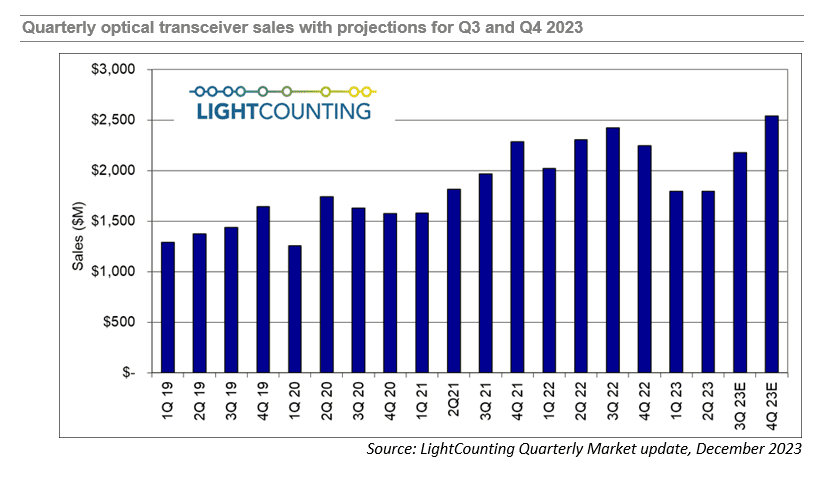
LightCounting is projecting, based on its current analysis, that sales increased in Q3 and will increase further in Q4, to a new record high, as shown in the figure below. This data includes estimates for 400G and 800G transceivers manufactured by Nvidia internally.
The expectation of growth in Q4 carries over to 2024 as well and is consistent with the guidance given by several companies ranging from Alphabet and Amazon to Coherent and Lumentum. The big caveat is that growth in 2024 will be tightly focused on AI-related infrastructure, and growth in demand for those products is expected to far outstrip demand in other segments like traditional telco and enterprise networks. Most of the growth in the optical components and modules market will come from sales of 800G transceivers.
References:
https://www.lightcounting.com/report/december-2023-quarterly-market-update-199
LightCounting: Will Network Transformation resolve telecom’s paradox?
Industry Analysts: Important Optical Networking Trends for 2023
MTN Group and NEC XON deploy Africa’s first 400G optical transponder using TIP’s Phoenix
Co-Packaged Optics to play an important role in data center switches
The commercialization of co-packaged optics (CPO) has been long anticipated but is becoming increasingly desirable as data needs accelerate. Co-Packaged Optics are an advanced heterogeneous integration of optics and silicon on a single packaged substrate aimed at addressing next generation bandwidth and power challenges.
As the bandwidth of data center switches increases, a disproportionate amount of power is becoming dedicated to the switch – optics interface. Reducing the physical separation between these two components by co-packaging enables system power savings which is essential to continued bandwidth scaling.
CPO brings together a wide range of expertise in fiber optics, digital signal processing (DSP), switch ASICs, and state-of-the-art packaging and test to provide disruptive system value for the data center and cloud infrastructure.
The companies and institutions working on CPO have made great strides in developing suitable electronic components. But hundreds of meters of fiber will be packed into the switch box for the first time, and faceplate connections will have unprecedented densities. As a result, the design and development of optical system solutions will also be critical elements in the success of CPO. Optical components with performance tailored to the CPO application and effective solutions for managing the fiber in the switch box are vital in optimizing the complete optical system. Three aspects of CPO deployment, in particular, hinge on the properties of the fiber and the optical interfaces: optical power loss, the trade-off between minimizing bend loss and controlling for MPI and maintaining the polarization state if external lasers are used.
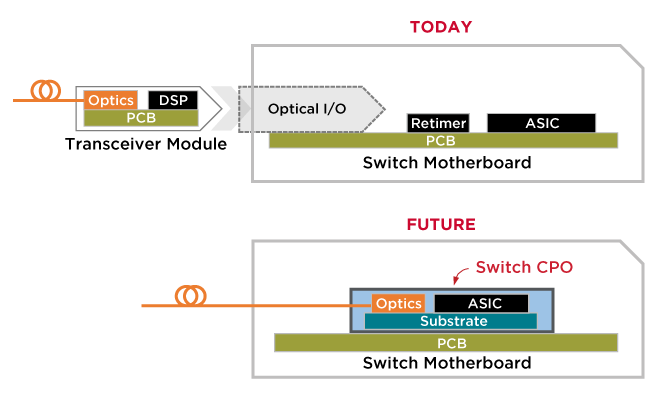
Image Courtesy of Broadcom
……………………………………………………………………………………………………………………………………….
Data centers face substantial challenges as they scale, particularly in reducing power dissipation and cost per bit. CPO will play a significant role in helping to meet those challenges. In today’s data center switches, external fiber optic connections that carry data terminate on pluggable transceivers on the housing faceplate. The optical data stream is coupled to the electrical signals at that interface.
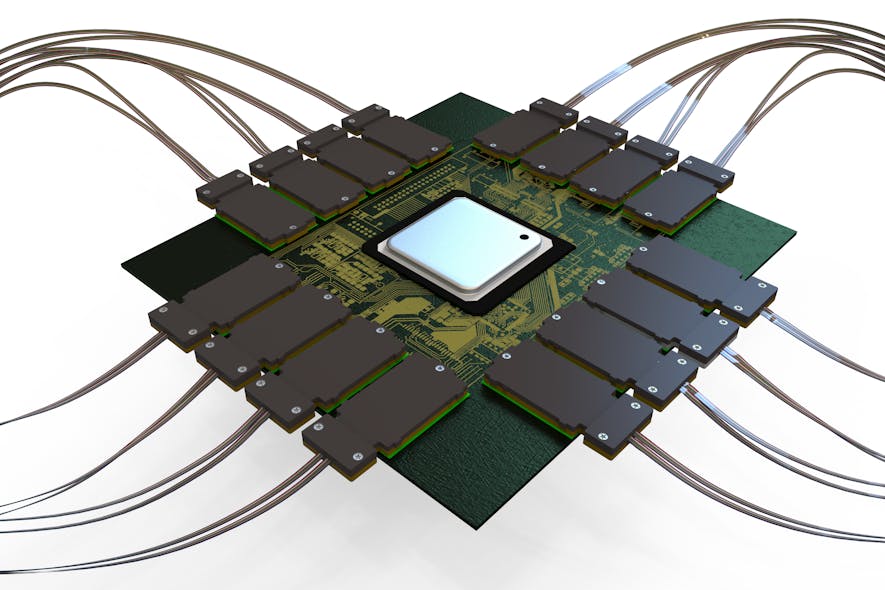
With a CPO realization of a 51.2 Tbps switch, the substrate connects a central regulator ASIC to 16 optoelectronic (O/E) tiles on the substrate perimeter. These tiles are connected to optical fiber signal cables that run to the switch box faceplate and receive power from external lasers that they modulate to produce the outgoing optical signal stream.
They communicate between the transceiver and the switch application-specific integrated circuit (ASIC) via copper traces on printed circuit boards. Under the CPO paradigm, as the optoelectronic conversion is pushed back from the faceplate to the switch substrate, long electrical traces are replaced with virtually loss-free optical fiber.
With CPO, the fiber path continues past a connector at the faceplate and into the switch box, ending at photonic integrated circuits (PICs) on optical tiles attached to the switch substrate. This shift presents the novel challenge of routing and connecting hundreds of optical fibers within a compact and crowded space, creating a need to minimize the footprint of the optics while still achieving performance and reliability targets.
CPO will soon be a reality that relies on a system of complex, interconnected components working well together. For optimum overall performance, these components must be designed with the specific requirements of CPO in mind, which for the optical subsystem include efficient and unobtrusive deployment within a crowded switch box, low power losses, absence of MPI impairments, and good reliability. Some CPO realizations also need optical polarization state control.
The familiar fiber and connectivity products, while having impressive attributes, are not optimum for the CPO application, and there is great scope for enhancing the performance of the optics by moving beyond default solutions to those specifically designed for the role.
References:
https://www.broadcom.com/info/optics/cpo
Coherent Optics: Synergistic for telecom, Data Center Interconnect (DCI) and inter-satellite Networks
Heavy Reading: Coherent Optics for 400G transport and 100G metro edge