fiber optics
Toshiba Wins UK Contract to Advance Commercial Quantum Networking: Can It Leverage Existing Optical Fiber Infrastructure?
Disclaimer: ChatGPT was used extensively to research and analyze the references cited in this article. The author provided editorial guidance and direction, reviewed the material, and is 100% responsible for the article’s final content.
…………………………………………………………………………………………………………………………………………………………………………………………………………………………………….
Introduction:
Toshiba Europe has been awarded a contract by Innovate UK, part of UK Research and Innovation (UKRI), to develop technologies intended to accelerate the commercial deployment of quantum networks. The Innovate UK-funded project targets scalable, multi-user quantum networks, but specialized Physical-layer requirements and deployment economics could limit their integration with conventional carrier optical networks. The project will focus on technologies for long-distance quantum links and multi-user quantum networks, with prototype subsystems evaluated under realistic operating conditions.
The contract was awarded through Innovate UK’s Enabling Commercial Quantum Networking competition, which supports UK companies developing components and subsystems for quantum networks. The competition represents a combined £20 million investment in the UK’s quantum technology ecosystem and aims to strengthen domestic capabilities across the emerging quantum networking supply chain.
The project supports the UK’s National Quantum Strategy, which includes an ambition to deploy advanced quantum networks at scale by 2035 and establish foundations for a future quantum internet. Such networks could eventually enable quantum information to be distributed among geographically separated quantum computers and other quantum systems.
Toshiba will develop and evaluate prototype subsystems designed to make quantum networks easier and more economical to expand using the UK’s existing optical fiber infrastructure. The work will investigate more efficient utilization of network resources and management of connectivity as the number of connected users and sites increases. Improved resource utilization could reduce infrastructure requirements and capital expenditures while making quantum networking services more accessible to telecommunications operators and customers.
UK network operators BT and Colt Technology Services will collaborate on validating the technology against practical network deployment and operational requirements.
Quantum networking and telecommunications infrastructure:
A significant longer-term application of quantum networking is connecting quantum processors located in separate data centers so that they can potentially work together on distributed computational tasks. Interconnecting quantum processors could expand the computational resources available to researchers and organizations and contribute to advances in areas such as pharmaceutical discovery and materials science. However, scaling quantum networks presents substantial engineering challenges. Unlike conventional optical communications, which transmit classical information using light, quantum networks must distribute and preserve fragile quantum states. This introduces requirements for specialized optical components, quantum-state management, synchronization and, ultimately, quantum repeaters capable of extending quantum communications over longer distances.
Integration with existing carrier fiber infrastructure is another important consideration. Network operators must address fiber loss, optical signal coexistence, routing, resource allocation and operational management while accommodating the specialized requirements of quantum communications.
One potential approach is to multiplex quantum and conventional data channels over the same optical fiber using wavelength-division multiplexing (WDM). This could avoid the expense of deploying entirely separate fiber networks. However, conventional optical signals can introduce noise and other impairments that degrade quantum channels. Raman scattering, optical power levels, fiber attenuation and losses introduced by multiplexers and other optical components all require careful engineering.
Furthermore, conventional optical amplifiers cannot simply be used to amplify unknown quantum states because of the quantum no-cloning principle. Quantum repeaters, which are needed to extend quantum communications over longer distances without relying on conventional amplification, remain a significant technology-development challenge.
Consequently, sharing existing fiber infrastructure does not necessarily mean that quantum networks can use conventional carrier optical equipment, transmission systems and operational procedures without substantial modification.
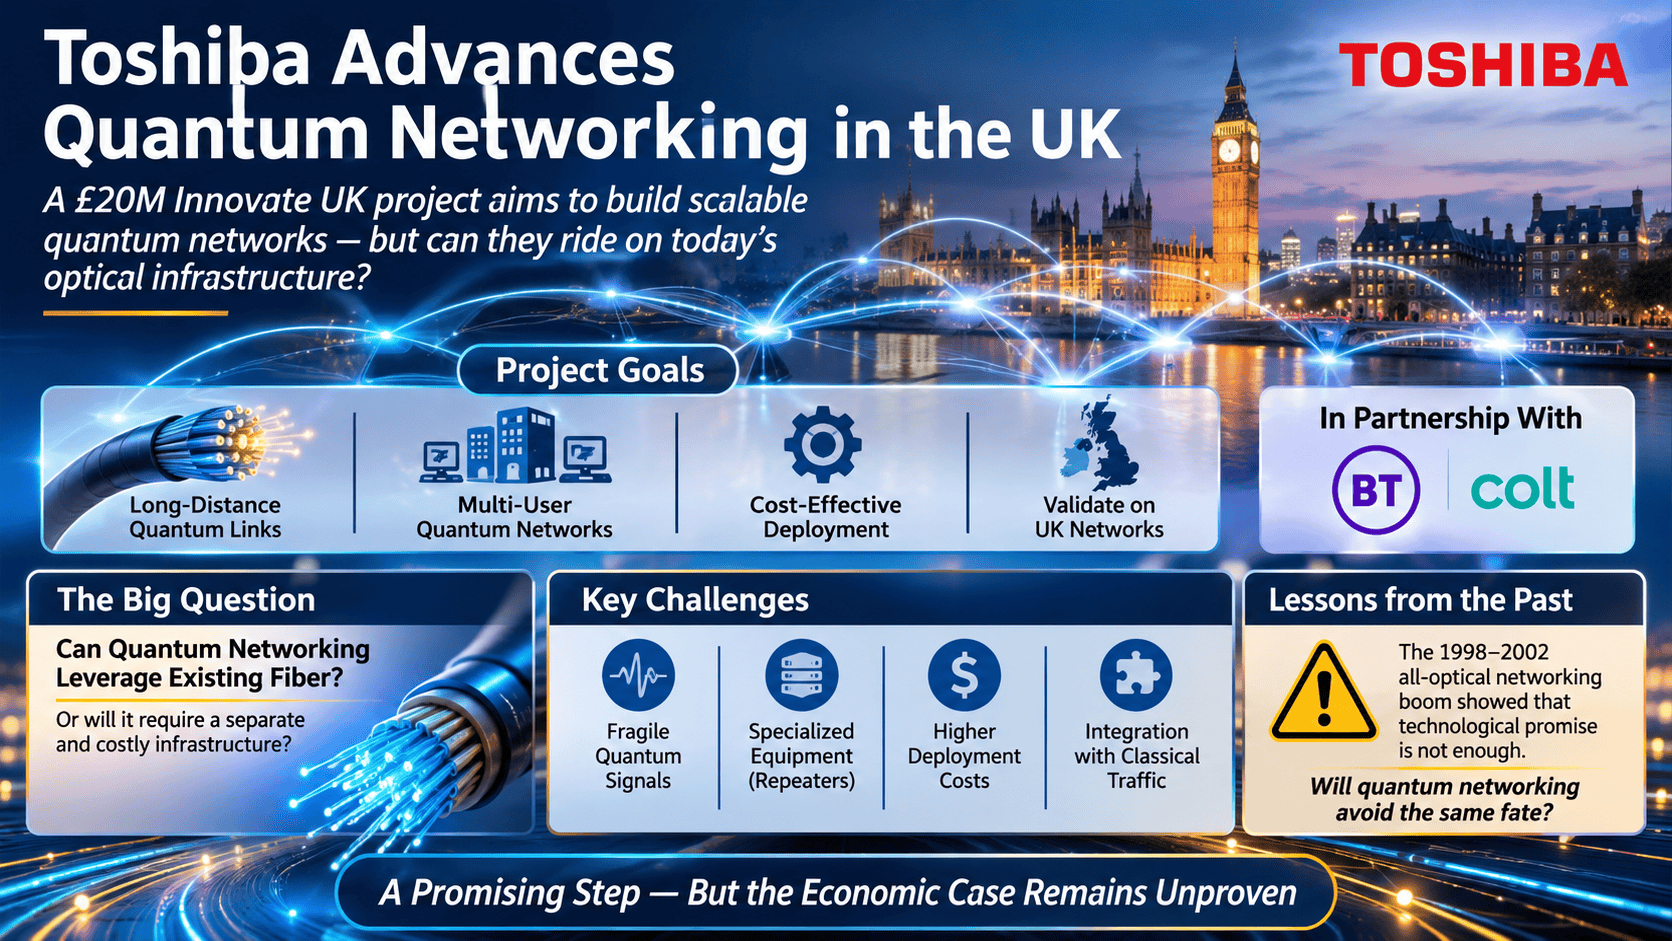
Image Created by ChatGPT
……………………………………………………………………………………………………………………………………………………………
Can quantum networking become an economically viable extension of carrier optical networks?
This is arguably the most important commercial question surrounding Toshiba’s project. The telecommunications industry has a long history of investing in promising optical networking technologies that did not achieve their anticipated commercial potential. During the 1998–2002 optical networking boom period, substantial investment went into photonic switching and all-optical networking. The vision was to eliminate repeated optical-electrical-optical (O-E-O) conversions, allowing data to remain in the optical domain throughout the network. That was supposed to usher in ultra-long-haul, repeater-less optical transmission. Photonic switches were expected to deliver enormous capacity improvements, reduce equipment complexity and lower network costs.
Despite considerable technical development and industry investment, all-optical switching did not become the dominant architecture envisioned by its proponents. Although optical circuit switches, MEMS-based photonic switches and ROADMs achieved commercial deployment in carrier networks, the broader vision of entirely photonic networking—with switching logic and control performed optically and without electronic processing—never became a commercially viable mainstream architecture. Conventional optical transport networks instead evolved through improvements in WDM, coherent optics, optical amplification, electronic switching and increasingly sophisticated optical-electrical-optical interfaces. The telecommunications industry ultimately favored hybrid optical-electronic networks.
Quantum networking could face a comparable commercialization problem. The ability to demonstrate quantum communication over existing fiber does not establish that a scalable, economically competitive carrier network can be built using conventional optical infrastructure.
There have been encouraging demonstrations of quantum and classical communications sharing the same fiber. For example, Toshiba and KDDI reported in March 2025 a demonstration carrying 33.4 Tbps of conventional data traffic alongside quantum key distribution (QKD) over an 80-kilometer fiber. This is an important proof of technical feasibility, but it does not establish the economics of a nationwide, multi-user quantum network.
There are also fundamental differences among quantum networking applications. QKD distributes cryptographic keys, while entanglement-based networking and distributed quantum computing require additional capabilities and substantially different performance characteristics. Success in multiplexing QKD with conventional traffic does not automatically demonstrate that geographically distributed quantum computers can be interconnected economically.
My assessment is that quantum networking is more likely, at least initially, to require specialized infrastructure and equipment than to become a straightforward extension of today’s carrier optical transport networks. Existing fiber may be reusable in selected applications, particularly metropolitan links and carefully engineered WDM deployments. But specialized quantum transmitters, detectors, synchronization systems, quantum memories, repeaters and associated control systems could impose substantial additional capital and operating expenses.
The economics become even more challenging when dedicated fiber, trusted intermediate nodes, environmental controls and specialized maintenance are required. Carrier operators will need to justify these costs against the actual revenue-generating applications and the alternatives available to customers.
The US and European quantum networking research communities have demonstrated that coexistence with conventional optical traffic is possible. Nevertheless, practical quantum repeaters, long-distance entanglement distribution, multi-vendor interoperability and scalable network management remain important obstacles.
It is therefore premature to assume that quantum networking will develop into a broadly deployed carrier service simply because existing fiber can be used in selected demonstrations.
The photonic switching experience of 1998–2002 is a useful cautionary precedent: technically impressive demonstrations and substantial R&D investment do not necessarily translate into commercially successful network architectures.
Toshiba’s quantum technology background:
The project builds on more than 25 years of Toshiba research and development in quantum technologies. The company recently introduced its Quantum-Safe Networking (QSN) Platform, designed to help organizations integrate quantum-safe protection into existing communications networks with reduced complexity, equipment footprint and cost.
It is important to distinguish these two technology areas. Quantum networking seeks to distribute quantum information and connect geographically separated quantum systems. Quantum-safe networking, by contrast, protects conventional communications against current and anticipated future cryptographic threats, including those posed by sufficiently powerful quantum computers.
Although related through their use of quantum technologies, these are distinct applications with different architectures, infrastructure requirements and deployment objectives.
Conclusions:
Toshiba’s collaboration with BT and Colt is a worthwhile technology-development effort addressing a genuine challenge: how to scale quantum networking without incurring the prohibitive cost of building entirely new fiber infrastructure. However, the critical test is not whether quantum signals can coexist with conventional data traffic over selected fiber links. It is whether the complete quantum networking architecture—including its specialized optical components, repeaters, control systems, maintenance requirements and operating costs—can deliver sufficient commercial value to justify deployment by telecommunications operators. Until that economic and technical case is demonstrated at meaningful scale, expectations for quantum networking as a natural extension of existing carrier optical infrastructure should remain guarded.
The historical lesson from the 1998–2002 photonic switching and all-optical networking boom is not that optical switching failed altogether. Rather, the ambitious vision of an entirely optical network, eliminating electronic switching and processing throughout the network, never materialized. Commercial optical switching did succeed, particularly at the wavelength and circuit layers, through technologies such as MEMS switches and reconfigurable optical add/drop multiplexers (ROADMs). However, electronic switching, processing and control remained essential components of commercial carrier networks. The industry ultimately adopted hybrid optical-electronic architectures rather than the fully photonic networks originally envisioned.
Quantum networking faces a similar commercialization challenge. Will it establish economically viable applications as a specialized extension of conventional optical networks, leveraging existing fiber wherever technically feasible? Or will its unique physical-layer requirements—including quantum repeaters, specialized transmitters and detectors, synchronization and stringent signal-management requirements—necessitate largely separate infrastructure with substantially higher deployment and operating costs? The ability to demonstrate quantum communications over existing fiber is encouraging, but does not establish that a scalable, commercially competitive carrier-network architecture is achievable. Ultimately, as with photonic switching, technical feasibility must translate into compelling economics and sustainable customer demand.
……………………………………………………………………………………………………………………………………………………………………………………………………………………
References:
Toshiba awarded contract to advance commercial quantum networking in the UK
UK Government – Quantum Key Distribution Research Report
https://www.gov.uk/government/publications/quantum-key-distribution-research-report/quantum-key-distribution-research-report
GSMA – Quantum Technologies and Telecom Use Cases (PDF)
https://www.gsma.com/solutions-and-impact/technologies/quantum-technologies/wp-content/uploads/2026/02/IG.19-Quantum-Technologies-Telcom-Use-Cases.pdf
CNAS – The Entanglement Edge (May 2026)
https://www.cnas.org/publications/reports/the-entanglement-edge
Nature – Quantum and Classical Coexistence over Hollow-Core Fiber
https://www.nature.com/articles/s41534-025-01125-7
ARCEP – Quantum Technologies and Their Impact on Networks (June 2026, PDF)
https://en.arcep.fr/uploads/tx_gspublication/futur-networks-briefing-note-quantum-technologies_june2026.pdf
PsiQuantum Targets AI Data Center Networks with Silicon-Photonic Optical Switching
2026 OCP Summit: Full-Stack AI Networking Silicon from Nvidia/Cisco and Broadcom; Ethernet vs InfiniBand Interconnects
Goldman Sachs report: Optical Networking is the next mega trend in AI infrastructure
2026 Fiber Connect Keynote: “The Future of Fiber Optics: AI and the Quantum”
IBM to Build World’s First Large-Scale, Fault-Tolerant Quantum Computer – Starling
Countdown to Q-day: How modern-day Quantum and AI collusion could lead to The Death of Encryption
Ultra-secure quantum messages sent a record distance over a fiber optic network
Google’s new quantum computer chip Willow infinitely outpaces the world’s fastest supercomputers
Quantum Computers and Qubits: IDTechEx report; Alice & Bob whitepaper & roadmap
Bloomberg on Quantum Computing: appeal, who’s building them, how does it work?
Deep Dive – AT&T Fiber vs. Verizon Fios: Fiber Deployments, Footprints and Convergence Strategies
Disclaimer: This article was written by Perplexity.ai in response to a query from Alan J Weissberger who edited the piece. The companion article is here:
AT&T’s Fiber Expansion Strengthens Its Converged Wireless and Home Broadband Strategy
Introduction:
- AT&T reported the large fiber-reach of 39M locations and an aggressive fiber expansion program.
- Verizon’s acquisition of Frontier substantially broadens its fiber platform.
- However, a current, apples-to-apples deployment-cost ranking is unavailable: the verified disclosures do not establish comparable 2026 construction costs per home passed. Historical cost estimates should not be presented as current operating metrics.
Deployment Economics and Fiber Reach:
Reporting basis: AT&T third-quarter 2026 results; Verizon second-quarter 2026 disclosures and acquisition announcements. The periods and fiber footprint definitions differ.
| Metric | AT&T Fiber | Verizon Fios / expanded Verizon fiber platform |
|---|---|---|
| Reported fiber reach | More than 39 million consumer and business locations at September 30, 2026. | The Frontier transaction brought the combined footprint to approximately 30 million homes and businesses; this is an acquisition-era figure, not a verified Q3 closing balance. |
| Year-end 2026 target | More than 40 million locations. | More than 32 million fiber passings, reiterated on the Q2 earnings call. |
| Longer-term expansion | More than 60 million locations by the end of 2030. | No directly comparable long-term target established in the sources verified for this dashboard. |
| Footprint boundary | Includes owned-and-operated fiber and reach through Fiber Ventures arrangements; not exclusively AT&T-owned construction. | Combined Verizon footprint includes acquired Frontier territory. It should not be labeled “Fios-only” reach. |
| Current construction cost per home passed | No comparable 2026 dollar figure verified. Management reported approximately 2% annual increases in average deployment cost per passing over the preceding two years. | No comparable 2026 Fios-specific dollar figure verified. |
| Historical cost reference—not a current estimate | In February 2023, management commentary placed deployment costs near a $900–$1,000-per-passing ceiling. The reported figure does not provide enough accounting detail for a clean cross-operator comparison. | Frontier—not legacy Fios—expected costs toward the upper end of a $900–$1,000-per-passing range in 2023. This cannot be substituted for Verizon’s current blended build cost. |
| Capital-efficiency signal | AT&T expects annual capital investment in 2027–2028 to be approximately $1 billion below its previous plan while maintaining its fiber-reach objective. This is a companywide investment outlook, not a disclosed fiber unit-cost reduction. | Management emphasizes operating- and capital-expenditure efficiency alongside Frontier integration, but the verified disclosures do not isolate comparable savings per new fiber passing. |
Fixed-Mobile Convergence:
| Metric | AT&T | Verizon |
|---|---|---|
| Reported convergence penetration | 42.8% of advanced home internet connections also had an AT&T consumer postpaid wireless account at Q3-end. This includes fiber and Internet Air, rather than fiber alone. | A directly comparable penetration percentage was not established in the verified disclosures. |
| Incremental converged relationships | Approximately 350,000 added during Q3 2026. | No directly comparable quarterly relationship-addition figure established here. |
| Commercial execution | Uses fiber and fixed wireless broadband to anchor multiproduct relationships and cross-sell mobile service. | Verizon One combines mobility and broadband with one bill and integrated servicing; its broadband component can be fiber or FWA. |
| Evidence on retention | Management identifies convergence as a customer-lifetime-value strategy. The verified Q3 material does not establish a controlled, like-for-like churn reduction attributable solely to bundling. | In September 2024, a Verizon executive reported approximately 50% lower mobile churn and 40% lower broadband churn among bundled Fios/wireless customers. These are historical management claims, not current 2026 measurements. |
| Principal execution issue | Increase penetration and multiproduct adoption while introductory pricing and bundle discounts pressure standalone fiber ARPU. | Convert the enlarged Frontier footprint into mobile/broadband relationships while integrating customer servicing and go-to-market operations. |
A convergence percentage measures customer overlap, not network integration. Neither a bundled bill nor a household taking both services demonstrates a unified fixed-mobile core architecture. AT&T’s reported metric explicitly counts qualifying customer relationships; Verizon’s unified offering likewise spans commercial packaging and servicing.
Access-Network Technology:
The most useful engineering comparison is the optical access architecture—not simply the highest advertised retail speed.
| Technical dimension | AT&T Fiber | Legacy Verizon Fios |
|---|---|---|
| Established multi-gigabit upgrade approach | XGS-PON, alongside its existing GPON base. | NG-PON2 overlay on existing GPON infrastructure in upgraded markets. This should not be generalized to the acquired Frontier network. |
| PON capacity | XGS-PON provides nominal 10 Gbit/s symmetric line capacity on a wavelength pair. | The cited NG-PON2 implementation supports four 10 Gbit/s wavelength channels, providing 40 Gbit/s aggregate capacity. |
| Architecture tradeoff | Lower-cost fixed-wavelength optics and a widely adopted upgrade approach. | Higher initial optical-system cost, offset by wavelength flexibility, potential channel bonding, and service separation. |
| Shared-infrastructure opportunity | Higher-capacity PON supports multi-gigabit access without rebuilding the entire passive fiber plant. | Verizon has described using NG-PON2 to support residential, enterprise, and wireless transport services on a common optical distribution network. |
| Important capacity caveat | PON line rate is shared access capacity—not a dedicated 10 Gbit/s allocation to every household. | The 40 Gbit/s figure is aggregate multiwavelength system capacity—not a standard 40 Gbit/s residential service. |
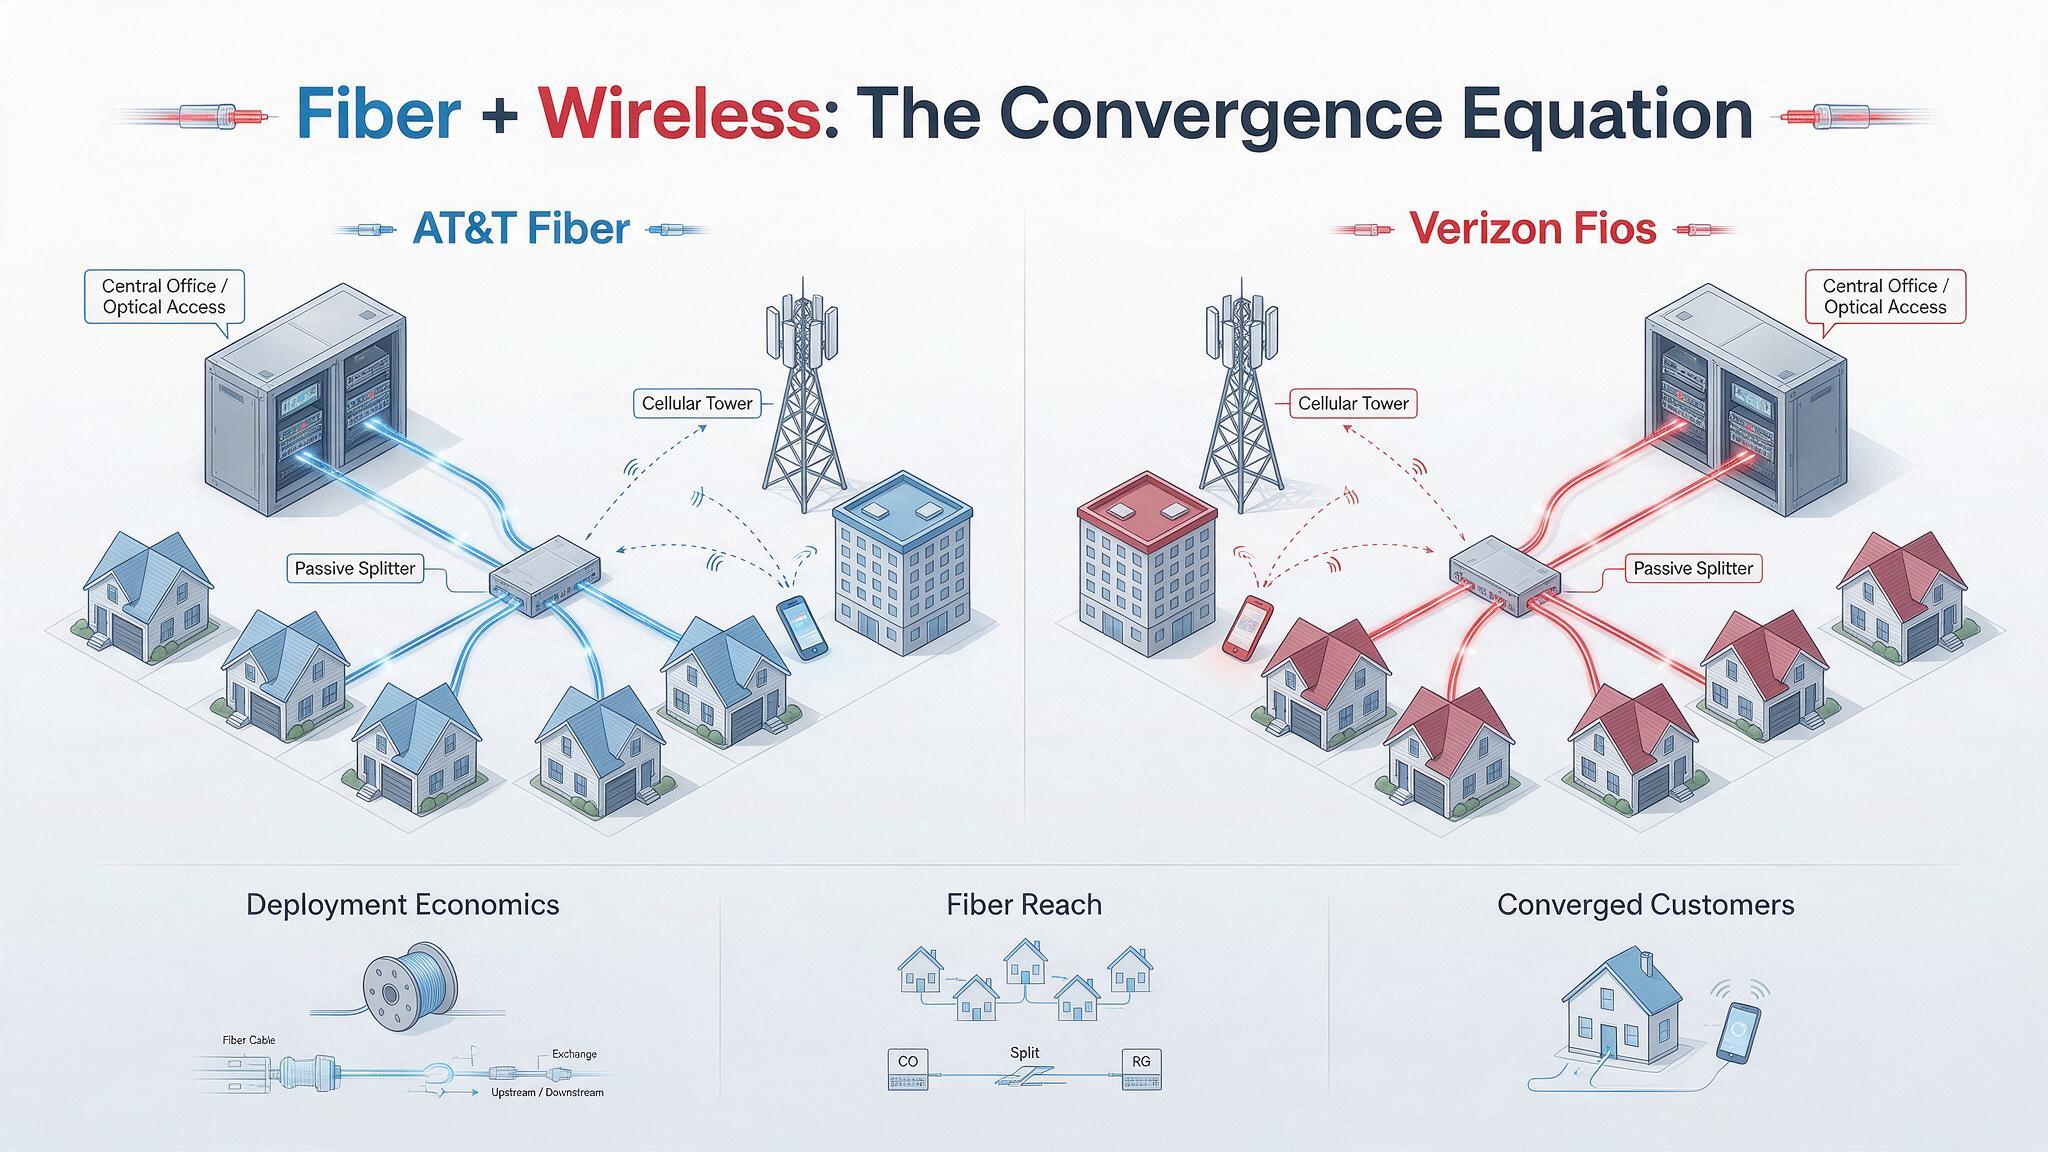
How to Interpret Deployment Cost Correctly:
A defensible cost dashboard must separate three different denominators:
-
Cost per passing: construction expenditure divided by newly serviceable locations.
-
Cost per connected customer: attributable construction expenditure divided by activated customers, plus any separately excluded connection costs.
-
Acquisition cost per passing: transaction value divided by acquired locations—a valuation measure, not a construction-cost measure.
The historical AT&T cost discussion illustrates the problem: the published figure did not clearly establish whether drops, customer electronics, installation labor, splitters, and other equipment were included. Without consistent cost boundaries, a seemingly precise AT&T–Verizon unit-cost comparison would be misleading.
An illustrative calculation—not either operator’s reported economics—shows why penetration matters:
References:
Network X Americas: AT&T and Comcast reveal huge AI impact on network operations
Analysis: AT&T 1Q-2026 results: increased fiber penetration, FWA momentum, D2D deals, and mobile/home internet bundles
AT&T grows fiber revenue 19%, 261K net fiber adds and 29.5M locations passed by its fiber optic network
AT&T sets 1.6 Tbps long distance speed record on its white box based fiber optic network
Lumen launches Multi-Cloud Gateway (MCGW) and expands metro fiber network after selling consumer FTTH business to AT&T
Impact of optical component shortages & bottlenecks explained + Hyperscaler’s CAPEX
LightCounting’s August 2026 market and component report highlights how severe physical supply shortages for high-speed optical components are reshaping data-center architectures and forcing cloud builders to expand their vendor pools from the traditional 2-3 suppliers up to 5-7 specialized hardware manufacturers. Qualifying and managing all of them is a new challenge.
- Applied Optoelectronics, Macom, and MaxLinear have already reported accelerating growth in Q2 2026 and we expect to see more examples in the upcoming earnings reports.
- Coherent and Lumentum have also reported improvements in growth rates for the last quarter, catching up with Eoptolink and Innolight (reporting at the end of August). Eoptolink has already disclosed a sharp increase in the profits expected for Q2. Accelink and CIG also report sharply higher profits.
- Tower Semiconductor reported triple-digit growth (y-o-y) in silicon photonics revenue in Q2-2026.
- GlobalFoundries plans to double its silicon photonics business in 2026.
- Cisco reported “a remarkable 28% y-o-y increase” in the networking segment revenues, up from 25% in Q1. Cisco reported three new hyperscale AI design wins and 40% growth in orders during the quarter. The company also reported record orders for campus networking – up 20% y-o-y.
- Arista Networks reported Q2 2026 revenue of $3.04 billion, marking its first-ever $3 billion quarter. This represented a roughly 38% year-over-year increase. Management also raised its full-year 2026 revenue growth outlook to 40%.
- Calix reported 21% y-o-y growth in Q2 and guided for another 15% in the current quarter. Growth in company’s revenue is attributed to sales of broadband equipment and AI-enhanced software to telecom operators.
- Extreme Networks reported 14% y-o-y growth in product sales, in part driven by success of its agentic AI networking platform.
Surging data-center traffic driven by AI queries has created acute optical component shortages, fundamentally altering supply chain qualifications for hyper-dense network switches and interconnects. The primary optical component bottleneck is a severe production shortage of Indium Phosphide (InP) laser chips and EML (Electro-Absorption Modulated Laser) components, which are failing to keep pace with a projected 53% surge in total optical transceiver and hardware demand, reaching $39 billion. Current demand for high-speed datacom optics is outstripping available supply by roughly 30%, forcing hyperscalers and system vendors to fundamentally restructure their supply chains. More details in the Addendum at the end of this article.
………………………………………………………………………………………………………………………………………………………………………………………………
Dell’Oro Group says that the rise of agentic AI and inference workloads is driving new demand and introducing network requirements that differ from those associated with training workloads. This shift is leading to significant expansion of front-end networks to support the broader buildout of AI infrastructure. We estimate that more than half of the growth in Front-end Data Center Switch sales over the next few years will be driven by AI-related opportunities. These deployments represent net-new expansion opportunities for both established vendors and new market entrants.
Accton, Arista, Celestica, Cisco, HPE/Juniper, H3C, Huawei, NVIDIA and others—emerge as the primary beneficiaries of this growth, according to the market research company.
“As AI infrastructure shifts from large-scale training to inference and agentic workflows, there is an increasing demand for general-purpose infrastructure, and expanded front-end network requirements,” said Sameh Boujelbene, Vice President at Dell’Oro Group. “The traditional assumption of a 10-to-1 ratio of XPU to CPU no longer applies across all deployments, with some environments moving closer to a 1-to-1 ratio. CPUs are becoming increasingly important for workloads orchestration and data movement. Additionally, networking for KV caching storage rack is also needed for inferencing applications,” added Boujelbene.
……………………………………………………………………………………………………………………………………………………………………………………….
As for the network providers/ISPs:
- Verizon announced a dark-fiber deal with Google to support the hyperscaler’s data center traffic growth. The deal is valued at over $1 billion and Verizon said there will be other deals announced before year-end.
- Deutsche Telekom said its AI factory for Germany’s public institutions and businesses that opened in February, has already sold the site’s 10,000 Blackwell GPUs capacity. DT is now looking at increasing capacity by another 20,000 GPUs.
- Comcast cites that its upstream broadband traffic is growing at 2.5x the rate of downstream data, which it links to AI-driven queries.
- AT&T is seeing rapid increases in large-scale data traffic requiring high-capacity metro and intercity fiber infrastructure.
Capex of Telecom Service Providers is still expected to be flat (or down 1%) in 2026, but AT&T and Comcast reported 16% and 20% y-o-y growth in capex for Q2, respectively. Both companies are investing more in broadband access. Verizon’s capex was also up, but only by 5% in Q2.
……………………………………………………………………………………………………………………………………………………………………………………….
Hyperscaler CAPEX:
The chart below illustrates the capital intensity of the TOP 4 Cloud companies. It is up sharply: Meta is already at 51% and Microsoft is at 46% in Q2. Oracle (not included in the figure) would have been off the chart at above 80% in Q1. The company reports earnings in early September and the key question is how it intends to finance future investments. Some moderation in spending growth is well needed. Amazon is the largest spender with $54.2 billion for the quarter, up 73% y-o-y. Amazon also increased guidance for 2026 capex from $200 billion to $220 billion.

Recent $ Trillion fundraising activities of Anthropic and OpenAI, supported by Nvidia, were widely covered yet both companies continue to lose money. Some financial experts refer to these activities as the “future for financial engineering.” Any innovation comes with some risk, but we all hope for the best.
………………………………………………………………………………………………………………………………………………………………………………………
Addendum: Optical Network Bottlenecks Explained:
-
- InP Epitaxial Production Limits: The primary physical constraint lies in the fabrication and epitaxy capacity for Indium Phosphide wafers used to build high-frequency lasers, where specialized manufacturing equipment (such as MOCVD systems) remains heavily backordered.
- Electrical Trace and Power Walls: Inside massive AI clusters, traditional pluggable optical modules face severe latency, thermal, and signal-integrity walls due to long copper electrical traces running from switch ASICs to the optical engine.
- Packaging and Testing Complexities: Shifting from legacy designs to dense 800G, 1.6T, and co-packaged optics (CPO) introduces intricate multi-die integration and hybrid bonding hurdles that slow down final module validation and packaging yields.
- Expanding Vendor Pools: Cloud builders are aggressively expanding their sourcing lists, moving from a concentrated pool of 2–3 legacy optical vendors out to 5–7 specialized component manufacturers to secure allocation.
- Ecosystem Pivot to Photonics: Major semiconductor players (such as Marvell’s acquisition of Celestial AI) and optical fabricators are pouring capital into silicon photonics and optical interconnect architectures to bypass standard copper and discrete laser constraints.
-
- Mechanism: LPO removes the power-hungry Digital Signal Processor (DSP) and clock/data recovery (CDR) chips directly from inside the optical transceiver module.
- The Fix: Raw, linear analog signals are driven straight from the switch or network interface card (NIC) ASIC.
- Benefits: Slashes module power consumption by 50% or more and cuts latency while preserving the hot-swappable, multi-vendor front-panel pluggable form factor.
- Trade-off: Requires host ASICs with advanced analog front-end and signal-equalization capabilities to process the raw electrical signals.
- Mechanism: CPO moves the optical engine (which converts electrical signals into light) off the front-panel cage and places it directly onto the same substrate or interposer as the switch or accelerator ASIC.
- The Fix: Electrical traces shrink from centimeters down to mere millimeters, completely bypassing lossy copper-clad circuit boards and high-power SerDes requirements.
- Benefits: Reduces optical-interface power consumption by up to 75% and maximizes bandwidth density for ultra-dense GPU scale-up fabrics.
- Trade-off: Reworks serviceability—if an optical engine fails, the repair domain shifts from a simple two-minute transceiver swap to board- or switch-level replacement
………………………………………………………………………………………………………………………………………………………………………
References:
Agentic AI and Inference to Supercharge Front-End Networks Growth, According to Dell’Oro Group
Networking chips and modules for AI data centers: Infiniband, Ultra Ethernet, Optical Connections
Goldman Sachs report: Optical Networking is the next mega trend in AI infrastructure
Cisco Execs: New “Network Supercycle” as Agentic AI Workloads Reshape Telecom Infrastructure
Cisco report: Agentic AI to reshape WAN traffic, AI inference will be ~25% of total traffic by 2035
Meta’s “Iris” AI Chip for MTIA: Implications for Telecom-Grade Optical Networking, DCI and High Capacity Ethernet Fabrics
Oriole Networks photonic networking platform to be integrated with AMD GPUs/CPUs for next-gen AI data center fabrics
Cheap Chinese AI Models: Unappreciated Threat to U.S. Hyperscaler AI Dominance
Verizon’s $1 Billion Google Dark Fiber Deal Highlights Importance of Optical Networks
Executive Summary:
Verizon CEO Dan Schulman said on Friday the company had secured a more-than-$1 billion dark fiber agreement with Google. It underscores how hyperscale AI growth is elevating dark fiber, route diversity, and high-capacity optical engineering into core industry priorities and is evidence that the network layer is becoming a central enabler of AI-scale computing. The deal, disclosed during Verizon’s Q2 2026 earnings call, is intended to connect Google data centers and support the transport demands of AI workloads.
“We have other deals that we expect to announce by year end that taken together are expected to be worth multiple billions of dollars in revenue over the next several years,” Schulman said on Verizon’s post-earnings call.
From a telecom perspective, the significance lies in the shift from best-effort connectivity toward engineered optical infrastructure with explicit performance objectives. As hyperscalers expand distributed AI training and inference, the requirements for capacity, latency, route diversity, and operational control increasingly favor dark fiber over shared transport models.blogs.cisco+2
Why This Matters for Network Architecture:
Dark fiber gives the customer direct control over the optical layer, enabling custom design choices for line rates, protection schemes, and traffic engineering. That flexibility is especially relevant for large data-center interconnect environments, where traffic growth can quickly outpace conventional managed services.blogs.cisco+1
The Verizon-Google transaction also reinforces the role of long-haul and metro fiber as strategic infrastructure rather than commodity bandwidth. In practice, this places greater emphasis on fiber route resilience, diverse path design, and the ability to scale toward higher-capacity optical systems as AI clusters expand.blogs.cisco+1
Standards and Industry Implications:
While the deal itself is commercial, its implications touch several standards-adjacent concerns that are increasingly important to operators and vendors. These include high-capacity optical transport, inter-domain coordination, deterministic latency for distributed workloads, and the operational models needed to support AI-driven traffic growth.blogs.cisco+1
For IEEE ComSoc readers, the broader signal is that future network evolution may be shaped as much by AI infrastructure economics as by traditional access or mobility growth. The value proposition is moving toward fiber-based transport layers that can support hyperscale interconnect, cloud adjacency, and resilient backhaul for distributed computing environments.benton+1
Conclusions:
Verizon’s reported dark fiber deal with Google suggests that optical connectivity is no longer a passive enabler but a competitive differentiator in the data-center supply chain. It highlights a broader shift in network economics: AI growth is elevating fiber infrastructure from a supporting asset to a strategic enabler. For carriers, the message is clear — the winners in the AI era may be those that can pair scale, route control, and transport engineering with the capacity demands of hyperscale cloud buildouts.
Text & Images from Sebastian Barros:
Verizon’s billion dollar agreement with Google shows that the AI infrastructure boom is moving beyond chips, data centers and electricity. The next constraint is connecting everything together. Verizon will use existing fiber where possible and construct new routes where necessary. It can provide either dark fiber or managed, lit capacity, depending on what the customer wants.
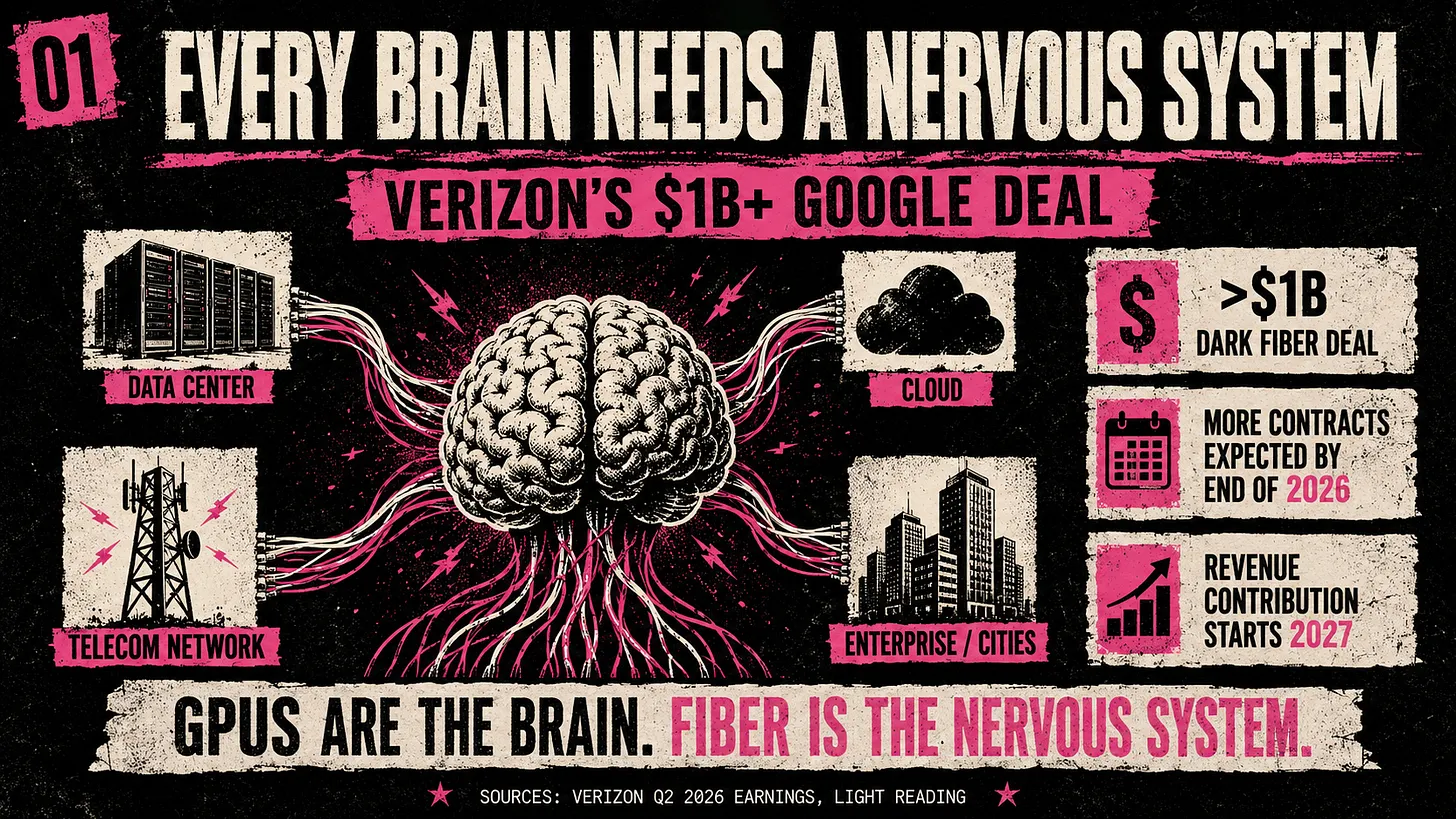
Google already operates one of the most advanced private networks in the world. Its infrastructure spans more than two million miles of lit fiber, 33 subsea cable investments, more than 200 network edge locations, and thousands of content delivery sites. Yet Google still needs Verizon to provide additional routes.
The (hyperscaler) companies building the largest AI brains cannot build every nerve themselves, as the pace is too fast. The telco opportunity begins when data needs to leave the campus.
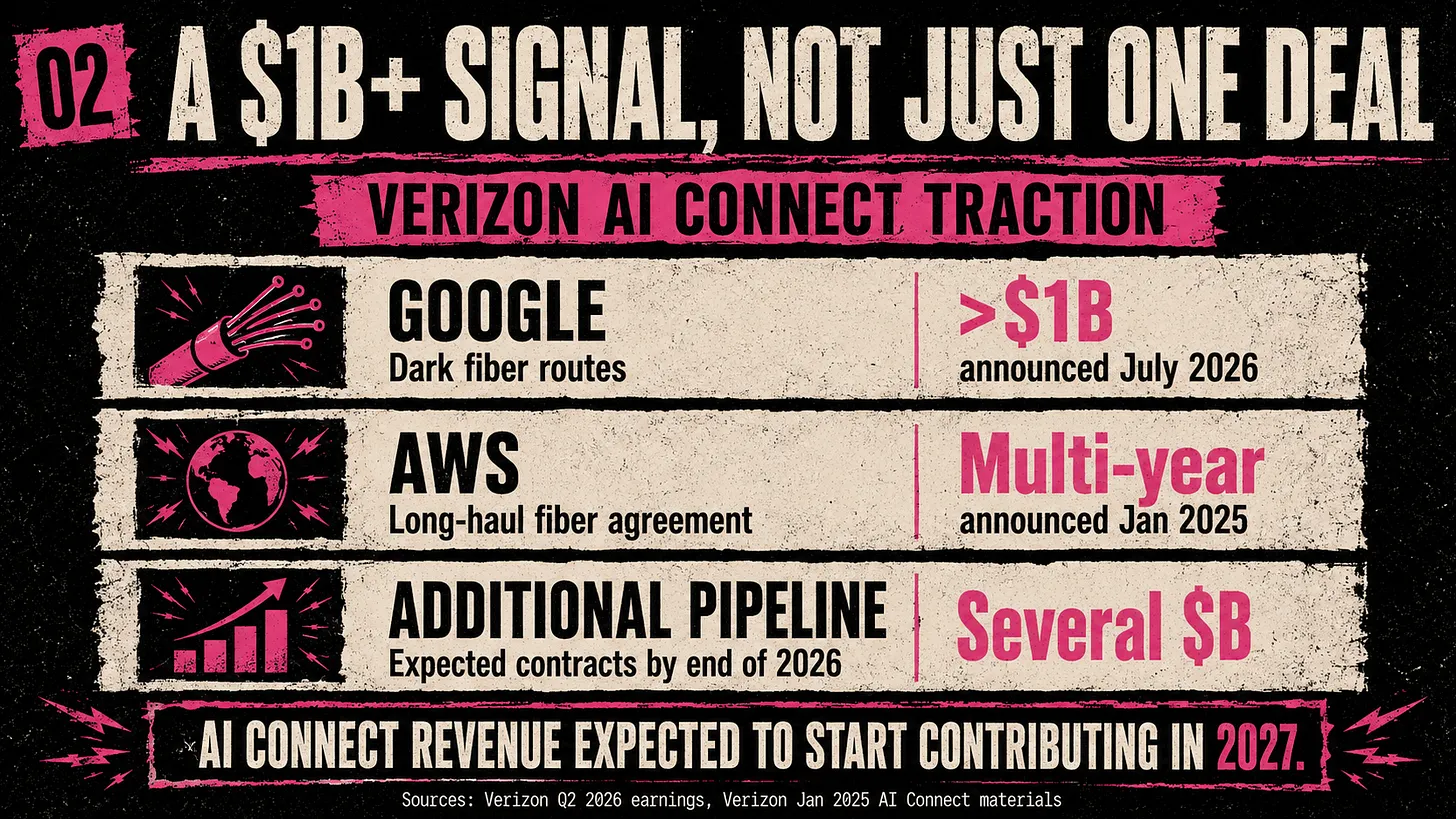
Models must be copied between regions; training datasets must be moved from storage locations to computing clusters; companies need private connections to cloud platforms; AI applications must retrieve enterprise information stored across different data centers. Inference results must reach factories, vehicles, hospitals, stores, offices, and consumers.
AI therefore requires two different networks. The first connects processors inside the brain. The second connects different brains with the outside world, and Telcos have a much stronger position in the second.
References:
https://sebastianbarros.substack.com/p/every-brain-needs-a-nervous-system
Verizon to build new, long-haul, high-capacity fiber pathways to connect AWS data centers
Hyper Scale Mega Data Centers: Time is NOW for Fiber Optics to the Compute Server
S&P Global Market Intelligence Surveys: Fiber Deployments in U.S. and Europe + AI Infrastructure Causes Market Shift
Amazon and Corning in Multi-Billion-Dollar Fiber Infrastructure Deal in North Carolina
2026 Fiber Connect Keynote: “The Future of Fiber Optics: AI and the Quantum”
Big Fiber’s $250M financing deal to buildout dark fiber routes for AI Data Center expansion
S&P Global Market Intelligence Surveys: Fiber Deployments in U.S. and Europe + AI Infrastructure Causes Market Shift
S&P’s Global Market Intelligence most recent survey showed that 87% of telecom providers in North America and Europe were deploying fiber optics last year, about the same as 2024. That’s according to the firm’s Erik Keith during a webinar hosted June 17th by the Fiber Broadband Association and its president, Gary Bolton. Among the 104 telecom operators surveyed globally, nearly nine out of ten are already using fiber as part of their broadband strategy. On the cable side, more than two-thirds of operators have either deployed fiber-to-the-home or plan to do so.
The Fiber Broadband Association says, “FTTH technology is clearly the “end game” solution for wireline broadband access services, however, the speed and scope of operator migration to full-fiber networks varies widely, depending on factors such as operator roadmaps and competitive landscape conditions.”
- Pervasive Adoption: Among the 104 telecom operators surveyed globally, 87% in North America and Europe utilize or are actively deploying fiber.
- FTTH Dominance: Fiber-to-the-home (FTTH) is widely regarded as the ultimate end-game for wireline broadband, though legacy copper and fixed wireless networks remain a part of some operators’ transition strategies.
- Cable Operator Progress: On the cable side, more than two-thirds of providers have already deployed FTTH or plan to do so as competition intensifies. More than two-thirds of surveyed cable operators have either deployed FTTH or plan to do so in the near future.
- Growing Cable Competition: Fiber overlap now extends across an estimated 75% of the U.S. cable footprint. Because of this, traditional cable operators are experiencing continued broadband subscriber losses and are actively revising their pricing and bundling strategies.
- High Consumer Satisfaction: Consumer surveys show that gigabit-tier fiber subscribers report the highest overall satisfaction rates, while fiber providers—including Verizon, Breezeline, and Frontier—claim the three lowest monthly churn rates in the U.S.
- AI as a Fiber Catalyst: Fiber is increasingly viewed as a dual-use asset capable of supporting both residential users and hyperscalers, as surging artificial intelligence (AI) demands require advanced, high-capacity infrastructure.
……………………………………………………………………………………………………………….
A different S&P Global Market Intelligence report argues that AI infrastructure demand is becoming linked to a larger market shift: constrained energy supply, higher expected earnings for producers and a growing premium for companies that control scarce capacity. For telecom and technology markets, the report adds another layer to the AI infrastructure conversation. The AI buildout is often discussed in terms of chips, models, cloud platforms and data centers. S&P Global Market Intelligence’s analysis suggests the conversation also needs to include energy supply, regional exposure, capex efficiency and the market value of scarce capacity.
……………………………………………………………………………………………………………….
References:
https://www.benton.org/headlines/fiber-breakfast-week-24-fiber-technology-trends
2026 Fiber Connect Keynote: “The Future of Fiber Optics: AI and the Quantum”
Analysis: Fiber Broadband Association (FBA) whitepaper: Upgrading MSO Networks to Fiber to the Home (FTTH): A Technical Perspective
Fiber Broadband Association Middle Mile WG: how to use “Digital Infrastructure Networks” for coordinated fiber backbone investments
Analysis: AT&T 1Q-2026 results: increased fiber penetration, FWA momentum, D2D deals, and mobile/home internet bundles
Fiber Optic Boost: Corning and Meta in multiyear $6 billion deal to accelerate U.S data center buildout
Fiber Optic Networks & Subsea Cable Systems as the foundation for AI and Cloud services
How will fiber and equipment vendors meet the increased demand for fiber optics in 2026 due to AI data center buildouts?
Automating Fiber Testing in the Last Mile: An Experiment from the Field
AI wireless and fiber optic network technologies; IMT 2030 “native AI” concept
EdgeCore Digital Infrastructure and Zayo bring fiber connectivity to Santa Clara data center
Fiber Connect 2023: Telcos vs Cablecos; fiber symmetric speeds vs. DOCSIS 4.0?
Amazon and Corning in Multi-Billion-Dollar Fiber Infrastructure Deal in North Carolina
Introduction:
The surge in optical fiber demand is intensifying as hyperscale cloud providers accelerate infrastructure buildouts to support AI-driven workloads and high-density data center interconnect (DCI). Corning [1.] today announced a multi‑billion‑dollar investment from Amazon to expand fiber manufacturing capacity in North Carolina—incremental to its previously announced $10 billion regional cloud infrastructure expansion—reflects a broader structural shift in how optical supply chains are being secured and scaled.
Note 1. Corning’s fiber-optic infrastructure uses highly pure strands of optical glass thinner than a human hair to transmit massive amounts of data as pulses of light. These networks serve as the backbone for modern communications, connecting everything from rural broadband rollouts to hyperscale data centers driving generative AI. In hyperscale cloud and AI data centers, Corning provides high-density optical hardware and cables, such as their GlassWorks AI™ solutions. These large setups feature massive fiber-optic trunk cables containing hundreds to thousands of individual fibers bundled together to link powerful processors and servers. For outdoor networks running underground or on utility poles, you will see ruggedized cables protected by thick jackets and aramid yarn. These cables are designed to withstand weather, crushing, and extreme temperatures.
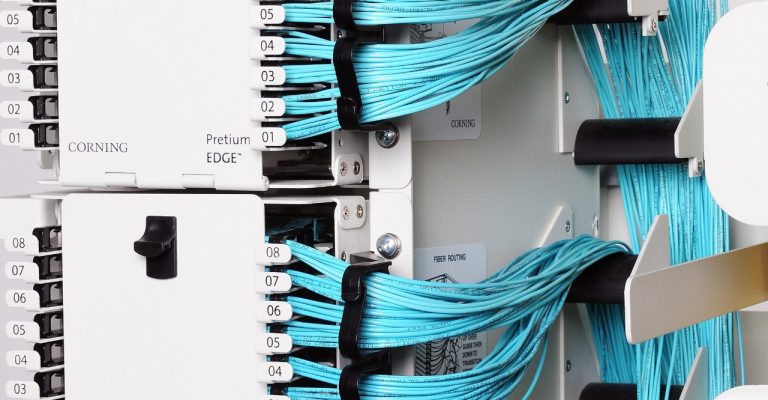
Corning’s structured cable solutions for internal data center connectivity. Image Credit: Corning
…………………………………………………………………………………………………………………………………………………………………………………….
This trend is not isolated. Hyperscalers including Meta, Microsoft, and wireline network operator Lumen are proactively entering long-term supply and co-investment agreements with fiber and cable manufacturers, effectively reshaping the upstream optical ecosystem.
Recent Fiber Supply Agreements with Corning:
-
May 2026: NVIDIA committed $500 million to Corning to support construction of three new optical manufacturing facilities in North Carolina and Texas. This investment is expected to increase Corning’s U.S.-based optical connectivity manufacturing capacity by approximately 10× and expand domestic fiber production by over 50%, targeting AI cluster interconnect requirements characterized by high fiber count and low-latency links aligned with IEEE 802.3 Ethernet and emerging co-packaged optics ecosystems.
-
January 2026: Meta finalized a $6 billion agreement with Corning to secure fiber supply for large-scale data center fabrics. These fabrics increasingly rely on high-fiber-density architectures consistent with leaf-spine topologies and standards such as IEEE 802.3bs/ck (400G/800G Ethernet), as well as parallel single-mode fiber (PSM) and wavelength-division multiplexing (WDM) approaches defined in ITU-T G.694.x.
-
September 2025: Microsoft entered a manufacturing agreement with Corning and Heraeus focused on hollow-core fiber (HCF), a technology aligned with ITU-T G.650 characterization frameworks. HCF offers lower latency (reduced group index) and improved performance for latency-sensitive AI workloads and inter-data center transport.
-
August 2024: Corning and Lumen established a supply agreement for next-generation fiber optic cable to support AI-driven traffic growth. This aligns with ITU-T G.652.D and G.657 fiber standards for bend-insensitive and high-capacity terrestrial deployments, as well as evolving requirements for high-count ribbon fiber cables in dense metro and campus environments.
Structural Implications for the Optical Supply Chain:
Hyperscalers are transitioning from passive consumers of optical components to active participants in manufacturing scale-up, including:
-
Anchor tenancy models: As seen with Meta’s backing of Corning’s North Carolina facility, hyperscalers are underwriting capacity expansion, effectively securing preferential access to supply.
-
Vertical influence: Direct investments and long-term offtake agreements allow hyperscalers to influence fiber specifications, manufacturing roadmaps, and deployment architectures (e.g., optimized fiber types for short-reach vs. long-haul DCI).
-
Workforce development: Amazon and Corning’s collaboration with Catawba Valley Community College to expand fiber technician training reflects a strategic effort to address labor constraints in optical manufacturing and deployment, reinforcing domestic supply chain resilience.
Implications for Telecom Operators:
These developments introduce non-trivial risks and strategic considerations for telecom operators:
-
Supply prioritization: Hyperscaler-backed agreements may shift allocation dynamics, potentially constraining availability for traditional telecom buyers during periods of tight supply.
-
Pricing pressure: Long-term, high-volume contracts could influence pricing benchmarks, potentially disadvantaging operators without comparable scale or capital flexibility.
-
BEAD timing mismatch: U.S. operators anticipating fiber expansion funded by BEAD (Broadband Equity, Access, and Deployment) may face supply bottlenecks if hyperscaler demand absorbs near-term manufacturing output.
-
Architectural divergence: Hyperscaler-driven requirements—optimized for short-reach, ultra-high-capacity intra-data-center and DCI links—may skew innovation toward their use cases, potentially misaligning with traditional access network needs governed by ITU-T G.984 (GPON), G.9807 (XGS-PON), and emerging 25G/50G PON standards.
A useful analogy is the semiconductor industry, where hyperscaler influence has already reshaped foundry capacity allocation and advanced node prioritization. A similar dynamic is now emerging in optical fiber and connectivity, with hyperscalers effectively acting as quasi-industrial planners for next-generation optical infrastructure.
Quotes:
“Amazon’s investments in North Carolina have created more than 26,000 jobs across the state. This multibillion-dollar agreement with Corning continues that commitment, channeling investment into American manufacturing and creating 1,000 new jobs at their facilities near our data centers,” said Matt Garman, CEO of AWS. “We’re also partnering to train North Carolinians for highly skilled roles in fiber optics and fusion splicing. These long-term investments create long-term careers and real opportunity in the communities where we operate.”
“This agreement with Amazon represents a significant milestone for Corning and for American manufacturing,” said Wendell Weeks, chairman, CEO, and president of Corning. “For 175 years, Corning has pioneered the technologies that connect people and transform industries. Amazon’s investment will help us expand production, create 1,000 new advanced manufacturing jobs at our facilities, and lead the way toward building a resilient U.S. manufacturing base.”
Clearfield CEO Cheri Beranek told Fierce Network at Fiber Connect that supply chain issues are re-emerging, particularly around high-count fiber. “There’s absolutely a shortage of ribbon fiber,” she said, referring to a conversation with Hawaii Telecom, a Clearfield customer. “The high count for the ribbon fiber … everything over 432 is tough to get,” she said. “The fiber companies want to tell you that there’s enough American‑made fiber… but there can’t be.”
“In talking to fiber optic suppliers, they all say one thing, ‘It’s nice to finally be the cool kid on the block.’ Hyperscalers are finally realizing that they not only need compute, storage, chips, power, water and real estate, they also need fiber optic connectivity,” said Fierce Network’s Chief Analyst Linda Hardesty.
The net effect is a tightening coupling between AI infrastructure demand and optical supply chain strategy—one that telecom operators will need to actively manage through procurement strategy, vendor diversification, and potentially deeper participation in supply-side partnerships.
End Note:
Amazon’s long-term commitment to North Carolina goes beyond direct investments and jobs created in the state. Through workforce development, Career Choice, and upskilling programs, Amazon has already provided practical training for nearly 7,000 people in North Carolina, helping to open new pathways for higher-paying jobs and fulfilling careers.
In the last decade, Amazon has contributed more than $72 million to charities and organizations supporting local needs across North Carolina, with $10 million provided in 2025 alone to 26 local community partners. This includes contributions like $1.5 million to enhance public safety services for southeastern Hamlet and surrounding Richmond County communities by funding a new fire substation that is expected to lower emergency response times and homeowner insurance premiums.
References:
https://www.corning.com/data-center/au/en/home/applications/enterprise-private-data-center.html
https://www.aboutamazon.com/news/company-news/amazon-corning-fiber-optics-1000-jobs-north-carolina
Fiber Optic Boost: Corning and Meta in multiyear $6 billion deal to accelerate U.S data center buildout
Corning to Build New Fiber Optic Plant in Phoenix, AZ for AT&T Fiber Network Expansion
Calix and Corning Weigh In: When Will Broadband Wireline Spending Increase?
Verizon-Corning $1.05B fiber deal part of larger build-out or buy program
Goldman Sachs report: Optical Networking is the next mega trend in AI infrastructure
Goldman Sachs analysts forecast a $154billion opportunity in optical networking driven by skyrocketing capacity demands from hyperscale cloud and AI workloads. Carriers and vendors are integrating 10GbE edge networking and AI-RAN (Artificial Intelligence Radio Access Network) trials on live 5G networks.
Goldman argues that AI infrastructure is creating a networking bottleneck phase, where optical interconnects become essential to connect more chips, keep latency low, and let AI clusters scale efficiently. The total optical networking market forecast 9x increase to $154 billion is due to both scale-up and scale-out AI data center architectures grow.
AI compute gains are no longer just about faster GPU and HBM chips; they depend on moving data fast enough between chips, racks, and super-nodes. Goldman Sachs emphasizes that networking now “unlocks computing capability” by enabling seamless exchange across multiple AI chips, which is exactly where copper-based links start to fall short. That makes fiber-optic connectivity, pluggable optics, and co-packaged optics central to the next phase of AI build-out. The report splits opportunity across scale-up and scale-out networking, plus component categories such as copper cables, pluggable optical modules, CPO, and PCB midplanes.
External coverage of this report says Goldman Sachs sees scale-up as the larger pool, about $106 billion or 69% of the $154 billion TAM, while CPO could represent about $91 billion or 59% of the total, assuming 29% penetration in scale-out networking. In practical terms, the report is signaling that the highest-value optical opportunity sits inside tightly coupled AI systems, not just in long-haul or metro transport.
………………………………………………………………………………………………………………………………………………………………………………………….
Goldman projects the following:
- Dollar content increase by 16x / 45x in Scale Out / Scale Up per computing unit from GB300 NVL72 (per computing unit means 72 GPUs per rack to reach NVL72) to Rubin Ultra NVL576 (per computing unit means 72 GPUs per rack, and 8 racks together to reach NVL576), with opportunities across pluggable optical modules, optical engines in CPO, copper cables, and PCB midplanes.
- A 13x larger addressable market for optical modules / optical engines expanding from scale out (e.g. GB300 NVL72) to scale up (e.g. Nvidia Rubin Ultra [1.] NVL576 level 2 scale up via CPO) per computing unit. n
- A 10x larger value market for pluggable optical modules in scale out per computing unit from GB300 NVL72 to Rubin Ultra NVL576, even with a 29% CPO penetration rate. The numbers of pluggable optical module (1.6T equivalent) per computing unit would increase from 216 units in GB300 NVL72 to 2.5k units in Rubin Ultra NVL576.
Note 1. Nvidia Rubin Ultra is a flagship, next-generation AI and high-performance computing (HPC) processor succeeding the standard Rubin architecture. Scheduled to debut in late 2027, it utilizes massive multi-die chiplet designs and unprecedented memory configurations to power the next wave of generative and agentic AI.
………………………………………………………………………………………………………………………………………………………………………….
Market Forecasts:
The investment bank expects the aggregate dollar content per computing unit across scale up and scale out to increase by 29x from US$315k in GB300 NVL72 to US$9.4bn in Rubin Ultra NVL576, and assuming the numbers of racks through the full product cycle are 48k racks for GB300 NVL72, and 16.5k computing units for Rubin Ultra NVL576, the aggregate value TAM across scale up and scale out would increase by 9x from US$15bn in GB300 NVL72 (mainly in 2026) to US$154bn in Rubin Ultra NVL576 (mainly in 2028).
Among the US$154bn value TAM, 69% goes to scale up, or US$106bn, and CPO contributes US$91bn, or 59% of the US$154bn value TAM, assuming CPO at 29% penetration rate in scale out.
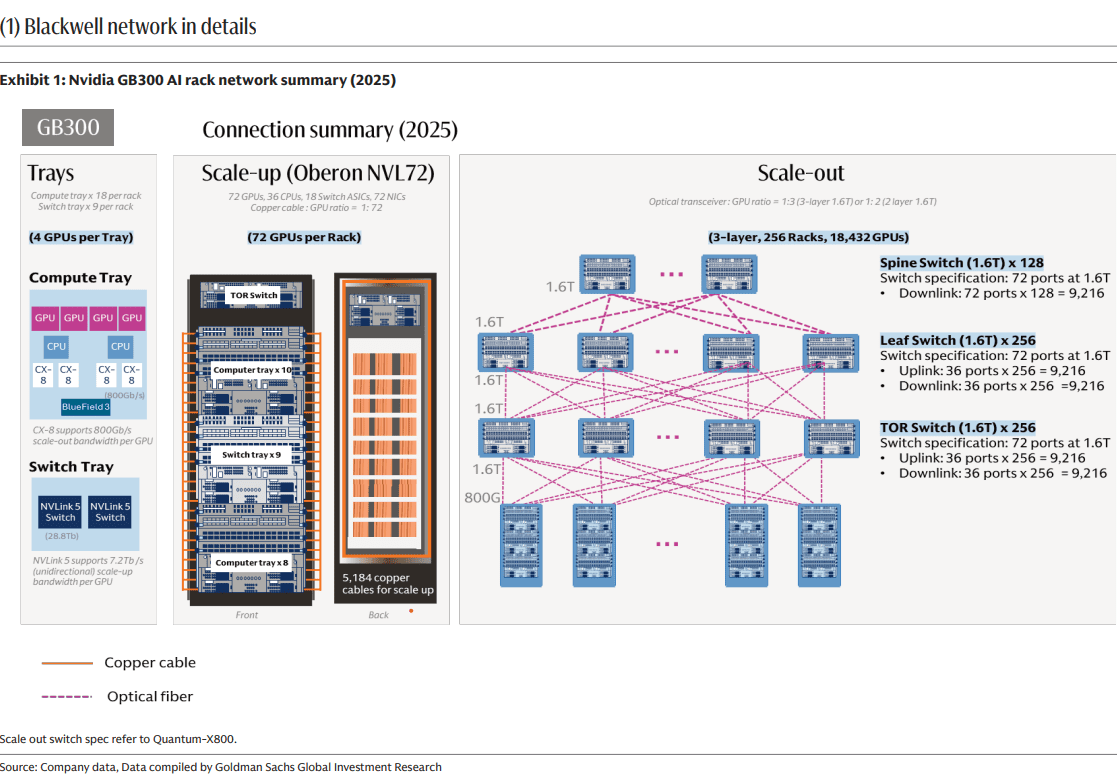
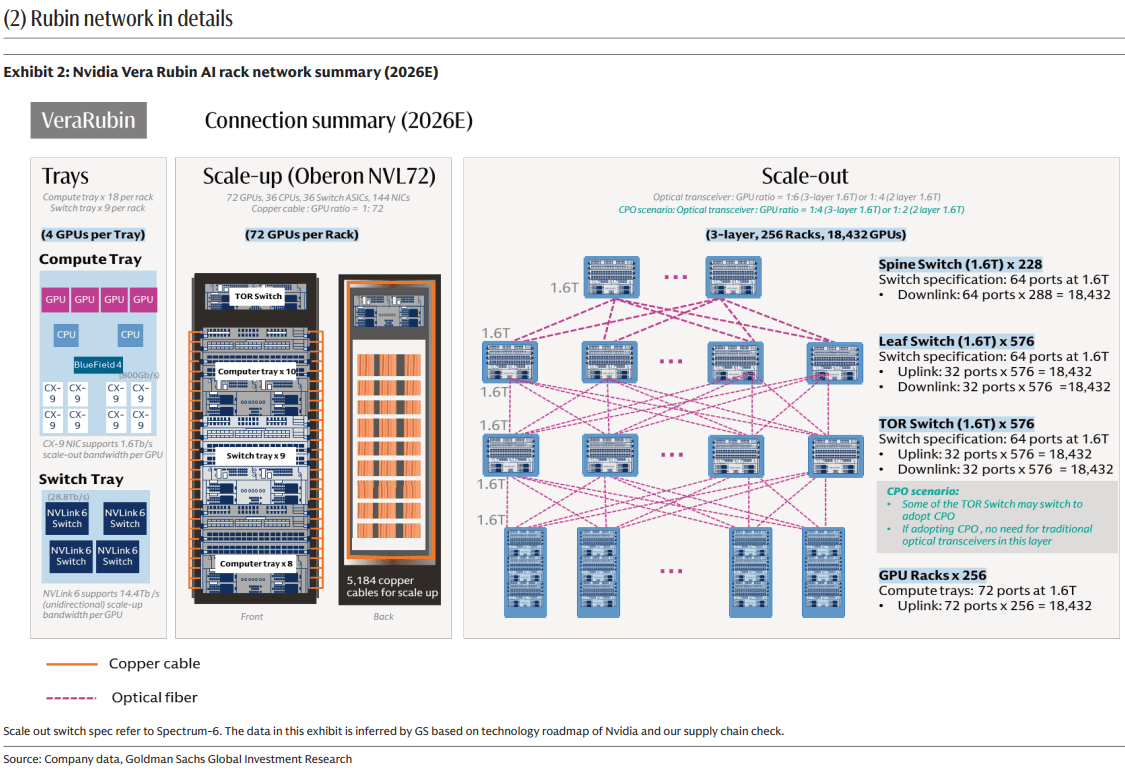
For network architects, the important takeaway is that AI clusters are becoming optics-heavy at more layers of the network stack, not just at the edge of the rack. The likely winners are suppliers that can reduce power, improve density, and simplify packaging for very high-bandwidth links, especially around CPO and advanced pluggables. This is less a story about traditional telecom optics and more about datacenter interconnects optimized for GPU fabrics and AI training/inference throughput.
The most consistently cited “top beneficiaries” are Coherent, Lumentum, and Fabrinet. These companies sit close to the core optical component modules and manufacturing layers that scale with higher AI interconnect demand. That makes them the most straightforward proxies for the forecasted optics expansion. The report’s thesis favors companies with strong exposure to high-end optical transport, coherent optics, and data-center interconnect rather than the broader optical networking/PON equipment companies like Ciena, Nokia/Infinera, Cisco/Acacia, ADVA, or Calix.
Conclusions:
Strategically, Goldman Sachs maintains that optical networking is no longer a niche enabling layer; it is becoming a core enabler of AI capex scaling. That shifts investor attention toward optical component vendors, silicon photonics, transceiver suppliers, and adjacent packaging ecosystems. The report’s core message is simple: as AI clusters grow, the network fabric becomes a first-order constraint, and optics are the most likely answer.
References:
2026 Fiber Connect Keynote: “The Future of Fiber Optics: AI and the Quantum”
How will fiber and equipment vendors meet the increased demand for fiber optics in 2026 due to AI data center buildouts?
Big Fiber’s $250M financing deal to buildout dark fiber routes for AI Data Center expansion
Analysis: Fiber Broadband Association (FBA) whitepaper: Upgrading MSO Networks to Fiber to the Home (FTTH): A Technical Perspective
Fiber Optic Boost: Corning and Meta in multiyear $6 billion deal to accelerate U.S data center buildout
Fiber Optic Networks & Subsea Cable Systems as the foundation for AI and Cloud services
AI infrastructure investments drive demand for Ciena’s products including 800G coherent optics
DriveNets and Ciena Complete Joint Testing of 400G ZR/ZR+ optics for Network Cloud Platform
2026 Fiber Connect Keynote: “The Future of Fiber Optics: AI and the Quantum”
Dr. Michio Kaku’s 2026 Fiber Connect keynote, “The Future of Fiber Optics: AI and the Quantum,” kicked off the inaugural AI & Emerging Technology Infrastructure Summit on Wednesday, May 20,2026.

As a theoretical physicist and futurist, Dr. Kaku delivered a high-altitude roadmap framing fiber optic networks not merely as faster telecom pipes, but as the mandatory foundation for a world defined by concurrent, multi-cloud AI infrastructure and quantum mechanics.
Kaku described the convergence of AI, quantum computing, and fiber infrastructure as a critical shift toward an AI-native, quantum-enabled internet essential for national competitiveness. Kaku emphasized that fiber optics are necessary to facilitate “quantum AI” by handling high-density, low-latency data movement, moving beyond traditional networking to support exponential computing advancements.
Key Takeaways:
- Fiber as the Foundation for AI: Dr. Kaku explained that massive data sets and hyperscale AI computations cannot run efficiently over wireless or legacy networks. Fiber’s near-limitless bandwidth and sub-millisecond latency are required to process these workloads in real-time.
- The Quantum Computing Leap: He detailed how quantum networks—which compute at the atomic level—will redefine security and processing power. He emphasized that quantum data requires the stability, security, and bandwidth that only fiber optics can provide.
- National Competitiveness: Dr. Kaku framed fiber broadband as a strategic national asset. He argued that a region’s ability to evolve into an AI-native economy depends directly on robust fiber infrastructure to secure future healthcare, financial, and climate innovations.
- The “Thinking Economy”: He projected that networks are evolving to do more than just transport data. They will increasingly support “thinking economies” where intelligence moves instantly between edge computing centers, end-points, and the cloud.
The presentation and subsequent fireside chat with quantum computing firm IonQ offered several critical technological dimensions and actionable industry analysis:
The Physics of the “AI Triad” (Compute, Quantum, & Photonics):
Kaku mapped out how classical silicon-based computing is approaching its physical limits (thermodynamics and transistor gating). He explained that the future relies on a three-pronged convergence:
-
- AI Models: The brain processing the logic.
- Quantum Computing: The hyper-accelerator solving atomic, chemical, and multi-variable optimization issues.
- Optical Fiber: The unified nervous system. Quantum and distributed AI workloads cannot scale on traditional copper networks because they require absolute determinism, zero-jitter latency, and near-limitless bandwidth.
Upgrading to a Quantum-Ready Internet:
Drawing from themes in his book Quantum Supremacy, Kaku noted that the move toward a quantum-enabled web alters the physical network topology. Operators must plan for physical security layers (like Quantum Key Distribution) and data transmission methods that preserve quantum entanglement across distances.
–>Fiber is the only media capable of transporting light photons over vast geographies without disrupting these states.
The Power and Cooling Crisis:
A significant focus of the analysis was the staggering energy footprint of next-generation AI factories and hyper-scale data centers. Kaku noted that moving data electronically creates heat resistance. Shifting toward all-optical (photonic) networks and in-rack fiber interconnects removes electronic bottlenecks, drastically reducing the power required to pass massive datasets between distributed data centers
Strategic Implications for Network Operators:
During the fireside chat, the discussion moved from theoretical physics to immediate business strategy and tactics:
-
- National Competitiveness: Bandwidth, latency, and optical infrastructure are the new benchmarks for a country’s economic power.
- Capacity Planning: Network planners must shift from estimating consumer download speeds to calculating the throughput required for real-time, stateful AI agents and machine learning inference workloads operating at the network edge.
FBA Panel and Summit Sessions:
Following Kaku’s opening address, the Fiber Broadband Association (FBA) hosted deep-dive industry panels that put these physics concepts into operator terms:
- The Open Compute Project (OCP): Discussed open-source hardware standards for in-rack photonics to support massive AI clustering.
- Multi-Data-Center Architectures: Network engineers mapped out how dense dark fiber rings are being laid to link secondary edge facilities, allowing enterprises to run heavy inference closer to end-users without overwhelming backbone networks.
- AI data center speed and power requirements are transitioning towards 800 Gbps–1.6 Tbps node-to-node networking and gigawatt-scale power to handle distributed generative AI workloads.
- High rack densities up to 240 kW require advanced liquid or immersion cooling, with optical technologies being introduced to reduce heat generation.
…………………………………………………………………………………………………………………………………..
References:
https://fiberconnect.fiberbroadband.org/about/whats-new/
Analysis: Fiber Broadband Association (FBA) whitepaper: Upgrading MSO Networks to Fiber to the Home (FTTH): A Technical Perspective
Fiber Broadband Association Middle Mile WG: how to use “Digital Infrastructure Networks” for coordinated fiber backbone investments
Analysis: AT&T 1Q-2026 results: increased fiber penetration, FWA momentum, D2D deals, and mobile/home internet bundles
Fiber Optic Boost: Corning and Meta in multiyear $6 billion deal to accelerate U.S data center buildout
Fiber Optic Networks & Subsea Cable Systems as the foundation for AI and Cloud services
How will fiber and equipment vendors meet the increased demand for fiber optics in 2026 due to AI data center buildouts?
Automating Fiber Testing in the Last Mile: An Experiment from the Field
AI wireless and fiber optic network technologies; IMT 2030 “native AI” concept
Big Fiber’s $250M financing deal to buildout dark fiber routes for AI Data Center expansion
Executive Summary:
Big Fiber [1.] has secured $250 million in financing from Stonepeak and Caisse de dépôt et placement du Québec (CDPQ) to expand its dark fiber footprint and increase network capacity in response to accelerating hyperscaler and large-scale data center investments in AI-driven workloads.
Note 1. Sunnyvale, CA headquartered Big Fiber was previously known as Bandwidth IG, which was originally established in 2019 as a telecom and dark-fiber infrastructure company. The rebrand to BIG Fiber was announced on May 1, 2025 when the company described it as a shift to better reflect its focus on privately owned, newly constructed dark fiber networks. The company has built privately owned metro dark fiber networks from its inception, primarily in the SF Bay Area and the Greater Portland, OR and Atlanta, GA areas.
BIG Fiber structures its dark fiber portfolio around high‑strand‑count, single‑mode, low‑loss fiber deployed in purpose‑built, underground metro and regional routes, rather than a carrier‑specific “technology” stack of its own. The company’s public materials emphasize:
-
Single‑mode fiber (SMF) for metro and long‑haul connectivity, consistent with standard dark‑fiber infrastructure designed for multi‑wavelength and DWDM‑based upgrades.
-
High‑density, high‑fiber‑count cables in metro corridors (often hundreds of strands) to support dense data‑center and interconnect demand, which is typical of “new‑build” dark‑fiber operators entering AI‑and‑cloud‑centric markets.
-
Point‑to‑point and ring‑style topologies engineered for extreme route diversity (tri‑/quad‑versity) and low latency, rather than a legacy long‑haul backbone that relies on older fiber types or managed wavelengths.
To complement Big Fiber’s dark‑fiber infrastructure; the customer provides the optical PHY layer (e.g., coherent DWDM, 400ZR/ZR+, or other high‑speed optics), which is how dark‑fiber providers typically position their offerings.
–>More about Big Fiber at the end of this article from the company itself.
……………………………………………………………………………………………………………………………………………………………………………………………………………………………………….
Proceeds of the facility will be used to refinance existing debt, provide new capital and facilitate the necessary headroom for major fiber optic network expansions already underway. This includes a significant multi-market buildout in Greater Atlanta, adding over 205 route miles and 165,000 fiber miles to BIG Fiber’s existing market-leading footprint.
“Our partnership with Stonepeak Credit and La Caisse marks a pivotal moment in our mission to empower our customers with highly scalable and purpose-built dark fiber solutions,” said Bruce Garrison, CEO of BIG Fiber. “This financing ensures we have the scale to stay ahead of the escalating demand for modernized infrastructure enabling the AI ecosystem and the necessary digital highways for decades to come.”
“BIG Fiber’s infrastructure delivers critical bandwidth to meet the insatiable demand for both data and compute capacity across its key markets,” said Arun Varanasi, Managing Director at Stonepeak Credit. “We are proud to partner with Columbia Capital, SDC Capital Partners, and La Caisse to support the company’s next leg of growth as it positions itself as one of the preeminent dark fiber operators in the country.”
“BIG Fiber is well positioned to meet the growing connectivity needs of enterprises and data centers seeking new, high-quality infrastructure options,” said Jérôme Marquis, Managing Director and Head of Private Credit at La Caisse. “Its resilient business model, underpinned by long-term contracts and strong structural demand, positions the company well for growth. Together with Stonepeak Credit, we’re providing a tailored financing solution that supports the continued buildout of essential digital infrastructure.”
The latest expansion will bring BIG Fiber’s Atlanta and San Francisco Bay Area network capacity to 850 route miles and over 3 million fiber miles. Projects are currently under construction or contract, with phased Ready for Service (RFS) dates expected in early 2027.

………………………………………………………………………………………………………………………………………………………………………………………………………………………………
According to Big Fiber Chief Commercial Officer Patton Lochridge, demand signals are particularly strong in key U.S. metros including the San Francisco Bay Area, Hillsboro, and Atlanta, where new fiber routes are being deployed to support AI-centric data center expansion. “We’re seeing customers require extreme route diversity, often moving toward triversity or quadversity networks to connect metro assets and long-haul routes,” Lochridge said. He added that inference workloads are increasing the demand for dense metro connectivity: “Traditional telecommunications networks are often too congested or lack the latency and loss tolerances required for stringent AI workloads, making purpose-built metro fiber essential.” Lochridge indicated that the majority of the new capital will be directed toward greenfield build-outs and targeted overbuilds of “exhausted legacy telecommunications corridors that need more scale.”
Industry analysts highlight a parallel geographic shift in AI infrastructure deployment. Sterling Perrin, senior principal analyst for optical networks and transport at Omdia, noted that AI campuses are expanding beyond traditional connectivity hubs such as Ashburn, Dallas, and Northern California into power-advantaged regions including West Texas, Ohio, Tennessee, Louisiana, and Georgia. “They all require massive fiber optic connectivity,” Perrin said.
Power availability is emerging as a primary constraint shaping network topology. Ron Westfall, vice president and analyst at HyperFrame Research, emphasized that grid limitations are driving hyperscalers toward distributed AI campus architectures interconnected via metro and long-haul dark fiber. “Power grid constraints have forced a material shift toward metro and long-haul dark fiber infrastructure to stitch together distributed regional data center campuses,” Westfall said. “Because this relentless GPU-to-GPU communication demands near-zero latency and unprecedented bandwidth, infrastructure planners are prioritizing the deployment of ultra-high-strand dark fiber corridors that directly link distributed, power-rich data centers.”
AI Workloads Reshape Optical Demand:
AI-driven traffic growth is now materially impacting the optical supply chain. In its April 2026 post-OFC analysis, CRU Group reported that AI-related data center demand “has overtaken traditional telecom as the primary growth engine for optical [fiber] and cable,” contributing to tightening supply conditions for high-fiber-count cables and upstream preform materials.
Despite this surge, the majority of AI traffic remains intra-data-center. Omdia estimates indicate that up to 90% of AI traffic does not exit the facility during GPU cluster operations. However, the emergence of distributed AI architectures is beginning to increase requirements for high-capacity inter-data-center interconnect (DCI).
At the Optica Executive Forum, Cisco SVP and Fellow Rakesh Chopra highlighted the scale differential between AI and conventional traffic profiles. As cited by Perrin, AI “scale-up” traffic within data centers can generate 504 times more traffic than traditional DCI flows, while “scale-out” traffic can produce 56 times DCI bandwidth requirements. “With AI training models at the limits of what can be processed within a data center, distributed AI clusters are inevitable,” Perrin said.
This architectural transition is reflected in NVIDIA’s AI factory designs, which decouple east-west GPU compute traffic from traditional north-south enterprise flows, leveraging low-latency leaf-spine topologies optimized for continuous GPU synchronization.
Westfall further noted that these evolving traffic patterns are fundamentally altering network design assumptions. Operators are increasingly optimizing for persistent machine-to-machine synchronization rather than burst-oriented enterprise traffic models.
Fiber as a Core AI Infrastructure Asset:
The Big Fiber’s latest financing aligns with broader trends in AI infrastructure investment, where capital is being deployed across integrated stacks including energy, land, connectivity, and compute infrastructure. Utilities are expanding transmission capacity, while developers are co-locating generation resources near emerging AI hubs.
Within this context, fiber infrastructure is being revalued based on its strategic proximity to power-rich data center clusters. “Infrastructure monetization is shifting away from historical metrics such as per-megabit pricing toward asset-level valuations built around proximity to power-rich data centers,” Westfall said.
If current deployment trajectories persist, the resulting topology will consist of a dense, high-capacity mesh of metro and long-haul fiber routes interconnecting geographically distributed, power-optimized AI campuses with hyperscale cloud and interconnection ecosystems.
………………………………………………………………………………………………………………………………
About BIG Fiber:
BIG Fiber is a metro dark fiber provider that offers high capacity, strategically placed, dark fiber networks to mission critical data centers, Hyperscalers and enterprises throughout the San Francisco Bay Area, Greater Portland and Greater Atlanta areas. BIG Fiber’s 100% underground network meets critical data needs for enterprises and data centers that require new, quality infrastructure options. BIG Fiber’s San Francisco Bay Area network offers more than 320 route miles and 65 data centers. The Greater Portland network has more than 20 route miles and 15 data centers, and the Greater Atlanta network has more than 550 route miles and 30 data centers. BIG Fiber was founded in 2019 and is headquartered in Sunnyvale, California. Visit www.bigfiber.com to learn more.
………………………………………………………………………………………………………………………………
References:
BIG Fiber Secures $250 Million Financing Led by Stonepeak Credit and La Caisse
Analysis: Fiber Broadband Association (FBA) whitepaper: Upgrading MSO Networks to Fiber to the Home (FTTH): A Technical Perspective
Fiber Broadband Association Middle Mile WG: how to use “Digital Infrastructure Networks” for coordinated fiber backbone investments
Analysis: AT&T 1Q-2026 results: increased fiber penetration, FWA momentum, D2D deals, and mobile/home internet bundles
Fiber Optic Boost: Corning and Meta in multiyear $6 billion deal to accelerate U.S data center buildout
Fiber Optic Networks & Subsea Cable Systems as the foundation for AI and Cloud services
How will fiber and equipment vendors meet the increased demand for fiber optics in 2026 due to AI data center buildouts?
Automating Fiber Testing in the Last Mile: An Experiment from the Field
AI wireless and fiber optic network technologies; IMT 2030 “native AI” concept
Analysis: Fiber Broadband Association (FBA) whitepaper: Upgrading MSO Networks to Fiber to the Home (FTTH): A Technical Perspective
Executive Summary:
The Fiber Broadband Association (FBA) has published an economic and structural framework for Hybrid Fiber Coax (HFC)-to-Fiber to the Premises (FTTP) [1.] upgrades, viewing that as a ‘strategic imperative’ for cable network operators (MSOs). FBA’s The whitepaper white paper, “Upgrading MSO Networks to Fiber to the Home (FTTH): A Technical Perspective,“ positions fiber as the long-term architectural solution for cable access networks.
The whitepaper evaluates multiple migration paths—including full overbuilds, targeted deployments, and HFC/FTTP coexistence—alongside passive optical network (PON) options and operating models. Economically, the report estimates FTTP operating expenses to be approximately 50% lower than HFC, driven by the elimination of active outside plant components. It outlines deployment options ranging from incremental overlays to full HFC replacement, each with distinct cost-performance trade-offs.
Note 1. Fiber optic access networks (sometimes referred to as fiber-to-the-home—FTTH—or fiber-to-the-premises—FTTP) are built to connect homes and businesses to lightning fast Internet connections. The fiber optic cables that make up these networks are the fastest and most reliable broadband technology and are capable of delivering vastly higher bandwidth than traditional copper wires or wireless. All-fiber networks are directly connected from the central office all the way to a subscriber’s building. There is no other technology along the path except fiber optics.
Fiber optic cables are made up of thin strands of glass that carry information by transmitting pulses of light, which are usually created by lasers. The vibrations are turned on and off very quickly. A single fiber can carry multiple streams of information simultaneously over different wavelengths, or colors, of light, enabling more robust video, Internet, and voice services. Fiber cables are capable of transmitting multi-gigabit Internet speeds compared to the mere megabytes typical of copper connections.
Image Credit: Panther Media GmbH/Alamy Stock Photo
…………………………………………………………………………………………………………………………..
Divergent Cable Operator (MSO) Strategies:
In practice, MSO upgrade strategies remain highly variable, shaped by market competition, plant condition, density, and capital constraints. Most large operators now manage hybrid access portfolios spanning HFC, FTTP, and, in some cases, fixed wireless access (FWA).
Optimum Communications, for example, is deploying FTTP overlays in dense Northeastern markets while relying on DOCSIS 3.1 in rural areas where fiber economics are less favorable.
Comcast and Charter similarly pursue selective FTTP in greenfield and edge-out scenarios but continue to prioritize HFC evolution via DOCSIS 4.0. Both assert that upgraded HFC can deliver symmetrical multi-gigabit services at lower cost. Charter estimates upgrade costs at approximately $100 per home passed (excluding CPE), versus roughly $200 for Comcast. Both operators utilize virtualized CMTS platforms and distributed access architectures (DAA) to support converged HFC/FTTP operations and targeted fiber extensions.
Operational cost differences remain contested. Charter CEO Chris Winfrey characterized the delta as minimal—on the order of one to two dollars per passing—stating, “We’ll take that tradeoff any day.” This reinforces the view that large-scale HFC-to-FTTP overbuilds are unlikely among major incumbents in the near term.
HFC investment also continues. Comcast and Charter are deploying low-latency capabilities based on the IETF Low Latency Low Loss Scalable Throughput (L4S) standard, with Charter already launching in multiple U.S. markets.
Fiber-First Deployments:
Smaller operators are, in some cases, moving more decisively toward FTTP. MCTV, serving approximately 57,000 customers in Ohio and West Virginia, determined that FTTP and DOCSIS 3.1 were cost-comparable and opted for full fiber rebuilds. The operator now passes more than 80% of its footprint with FTTP and has decommissioned roughly two-thirds of its HFC power supplies.
Competitive and Technology Outlook:
The FBA identifies FTTP as the “primary driver” of recent cable subscriber losses, citing “structural limitations” of HFC in symmetry, latency, and scalability “that DOCSIS upgrades can partially address but not fully overcome.” Cable proponents dispute this, pointing to DOCSIS 4.0 and future enhancements.
However, competitive pressure is multi-dimensional. In addition to fiber, FWA is gaining traction, particularly in lower-speed tiers. As a result, operators are increasingly focused on pricing, service bundling, and customer experience, including converged broadband-mobile offerings, rather than peak speeds alone.
On the technology roadmap, CableLabs continues to extend DOCSIS, including exploration of an “operational annex” supporting spectrum up to 3 GHz and downstream rates around 25 Gbit/s, with longer-term targets of 6 GHz and 50 Gbit/s. At the same time, it is expanding work on PON, including coherent PON, reflecting a more access-technology-agnostic posture.
Migration Trajectory:
Some industry veterans align with the FBA’s long-term view. John Chapman has advocated a “fiber-first” strategy, citing projections that access networks may need to support up to 1 Tbit/s by 2040. Rather than abrupt transitions, this approach emphasizes phased migration from HFC to FTTP while leveraging existing infrastructure.
Quotes:
John Chapman, a DOCSIS pioneer and former long-time Cisco Systems engineering exec, suggested last year that the cable industry should adjust its thinking and take a “fiber-first” approach as historical trends indicate that broadband access networks will need to be capable of supporting speeds of 1 Tbit/s by 2040. Rather than doing a quick cutover, he thinks MSO’s should migrate from HFC to FTTP over an extended period. But they should get started now.
“The industry has reached an inflection point between the maturity of DOCSIS and the inevitability of fiber. It’s about coming up with a graceful, pragmatic solution to migrate, to transition from DOCSIS to fiber. And that migration’s going to take 20 years. But we need a strategy that accommodates the two,” he said. “It’s a cultural change.”
Jay Rolls, a former Charter CTO and current CTO of BSP, a company that conducts due diligence on various types of broadband network transactions, also believes that cable operators should be weighing whether FTTP is the right move. His recent analysis suggests that the capital spend on a DOCSIS 4.0 overhaul is comparable to an FTTP rebuild.
“Every network and market is different, but the tipping point is fast arriving where overbuilding fiber makes as much financial sense as upgrading HFC, especially when you consider what comes next,” he said on a Light Reading podcast.
References:
Upgrading MSO Networks to Fiber to the Home (FTTH): A Technical Perspective
https://fiberconnect.fiberbroadband.org/
Fiber Broadband Association Middle Mile WG: how to use “Digital Infrastructure Networks” for coordinated fiber backbone investments
Analysis: AT&T 1Q-2026 results: increased fiber penetration, FWA momentum, D2D deals, and mobile/home internet bundles
Fiber Optic Boost: Corning and Meta in multiyear $6 billion deal to accelerate U.S data center buildout
Fiber Optic Networks & Subsea Cable Systems as the foundation for AI and Cloud services
How will fiber and equipment vendors meet the increased demand for fiber optics in 2026 due to AI data center buildouts?
Automating Fiber Testing in the Last Mile: An Experiment from the Field
AI wireless and fiber optic network technologies; IMT 2030 “native AI” concept