AI & OPEX
Bain & Co: AI Infrastructure Buildout Will Require $6 Trillion Revenue by 2031 to Support Massive CAPEX
Introduction:
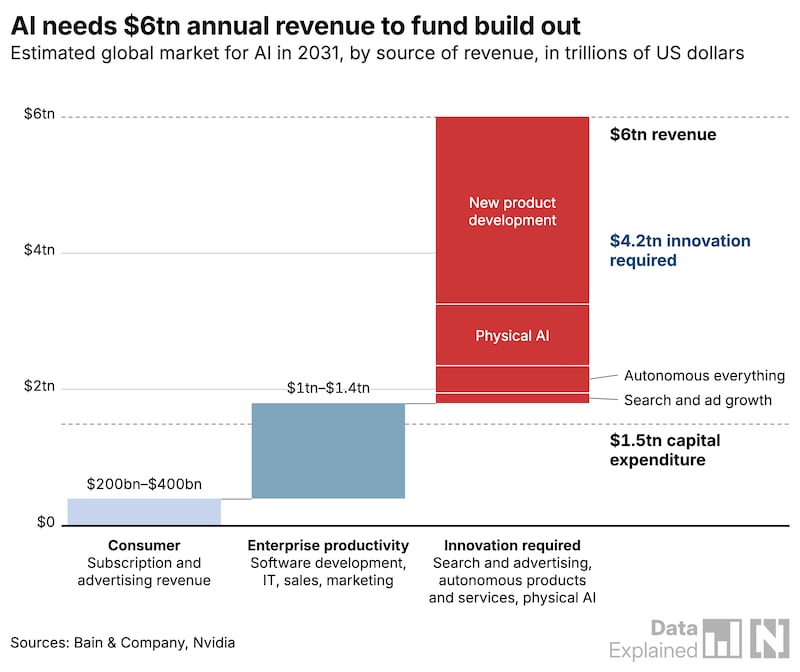
Bain & Company estimates that the AI industry will need to generate approximately $6 trillion in annual revenue by 2031 to support the capital intensity (CAPEX) of the global AI infrastructure buildout, including investment in data centers, accelerated computing, memory, networking and power systems. In its latest technology report, released September 29th, Bain projects that new AI-enabled products could account for roughly $4.2 trillion of that revenue requirement. The firm identifies AI-driven innovation across search, advertising, autonomous systems and physical AI as major prospective sources of value creation.
Enterprise adoption could contribute a further $1 trillion to $1.4 trillion annually through productivity gains in software engineering, sales, marketing, customer service and IT operations. Bain characterizes “absorption speed”—the rate at which enterprises operationalize AI—as the emerging competitive variable, with leading AI labs investing more than $9.75 billion in engineering models intended to accelerate enterprise deployment and integration.
“The debate today is fixated on employee productivity. The economics of AI infrastructure demand trillions in new revenue beyond productivity gains. What the industry needs is a wave of innovation that will dwarf what mobile and cloud unlocked,” said David Crawford, chairman of Bain’s global technology practice and lead author of the report.
At a Glance:
- AI infrastructure investment is racing ahead, but generating enough economic value to justify it will require trillions of dollars in new AI-driven revenue.
- Productivity gains from existing enterprise and consumer applications won’t be enough; entirely new markets must emerge to close the funding gap.
- The winners will be those that create breakthrough AI applications that transform industries and expand the global economy.
Consumer AI services, including subscription and advertising-supported offerings, are projected to contribute between $200 billion and $400 billion in annual revenue. This segment is central to the commercial scaling of AI because it extends AI-enabled services to billions of users through consumer platforms, devices and digital-service ecosystems.
“New products and uses that don’t exist today will enable new markets and opportunities from abundant intelligence – these may include drug discovery, mental health and energy generation,” Bain said.
Bain forecasts annual AI infrastructure spending of up to $1.5 trillion by 2031. The figure encompasses greenfield data-center construction, expansion of existing facilities, and continuing investment in GPUs, memory, network fabrics and related infrastructure. Bain assumes that capital expenditure could represent approximately one-quarter of total AI-industry revenue—“an ambitious but reasonable percentage based on trends among cloud providers.” On that basis, the firm calculates that the AI market would need to approach $6 trillion in annual revenue to sustain the projected infrastructure investment cycle.
“The unprecedented speed and scale of the AI buildout, with billions flowing into chips, data centers, networks and power systems, have focused attention on the challenge of building capacity. But the more important question may be whether enough economic value can be created to justify it.”
Consider the scale of investment and the gap between that and the revenue model necessary to fund it.
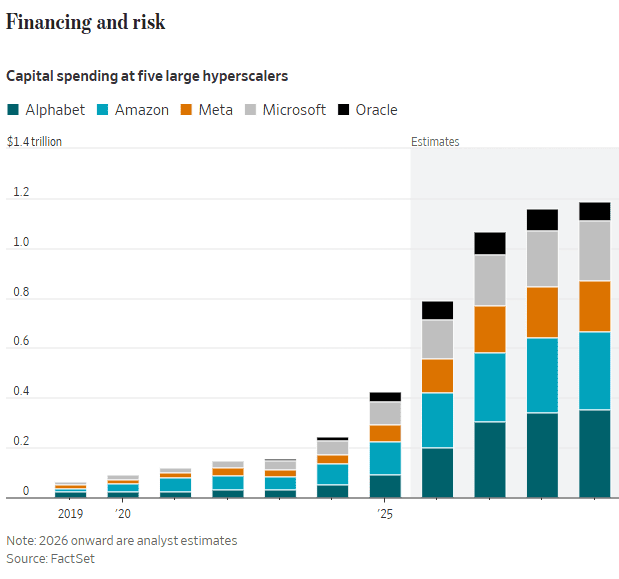
- The arms race among hyperscalers (Microsoft, Google, Amazon, Meta, and Oracle) is accelerating: Their capital expenditures could reach $780 billion in 2026, nearly five times the level of just three years earlier.
- Leading-edge AI data centers today are approaching 1 gigawatt (GW) of power capacity. By 2027, many are expected to approach 2 GW facilities, with 9 GW campuses emerging by the end of the decade.
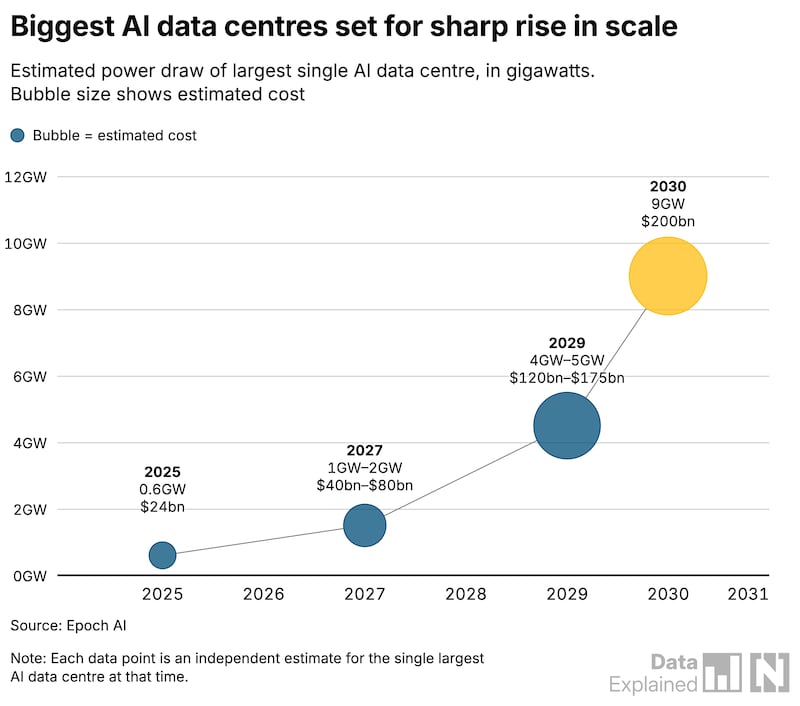
The scale of individual AI data-center projects illustrates the infrastructure requirements underlying those projections. Bain said AI data-center size and cost are increasing rapidly, with leading facilities approximately doubling in scale every 12 to 16 months. Meta Platforms’ Prometheus data center in Ohio, for example, had approximately 600 MW of capacity and an estimated cost of $24 billion in 2025, according to Epoch AI. The facility is projected to reach as much as 2 GW of capacity and cost approximately $80 billion by 2027. Epoch AI projects that Prometheus could reach 5 GW by 2029, with costs of up to $175 billion, and 9 GW by 2030, at an estimated cost of $200 billion.
Such growth places data-center infrastructure squarely within the telecommunications and network-infrastructure domain. Multi-gigawatt AI campuses require high-density optical interconnects, large-scale Ethernet or InfiniBand fabrics, low-latency east-west traffic engineering, high-capacity metro and long-haul connectivity, and resilient access to electric generation and transmission capacity. The infrastructure challenge consequently extends beyond data-center construction to the coordinated scaling of semiconductor supply chains, transport networks, power systems, cooling infrastructure and specialized technical labor.
Bain identified electric-grid capacity, access to GPUs and other critical infrastructure components, talent availability, workforce retention, public acceptance and regulatory requirements as important factors shaping the pace and geography of AI data-center deployment. Resource consumption, noise and community impacts are also becoming material considerations in project planning and approval processes.
Governments in the UAE, Saudi Arabia, the European Union, South Korea and the United States are supporting the expansion of AI and data-centre infrastructure, Bain said. The firm described data centres as increasingly important to technology innovation, economic development and national sovereignty.
The Bain report stated: “Capital needs for data infrastructure will remain high … bottlenecks in power, semiconductors, and other inputs carry large capital needs of their own, opening additional entry points for investors. And as sovereign infrastructure becomes a bigger part of national strategies, partnerships offer both a way in and geographic diversification.”
…………………………………………………………………………………………………………………………………………………………………………………………………………………….
Greg Ip of the WSJ: Believers in the artificial-intelligence boom need to take a very close look at this number: 9% of GDP. That is how much American businesses and consumers eventually have to spend per year on the services of companies like Anthropic and OpenAI to justify the staggering sums being committed to the technology right now.
Is it plausible that Americans will spend as much of their income on this one technology as they do on food? Roughly twice what the nation pays for all forms of energy or all computers and software? Seven times what consumers spend on phone, streaming, and internet services combined?
You should be skeptical. Even the most transformative inventions eventually run into the law of diminishing returns: each additional dollar a user spends yields less additional productivity (or enjoyment) than the last. That imposes a natural ceiling. The question, of course, is where that ceiling is. Whether or not you think 9% of GDP is right, you have to care, because this figure isn’t some fever dream: it is implicit in the dollars that investors and companies are committing right now.
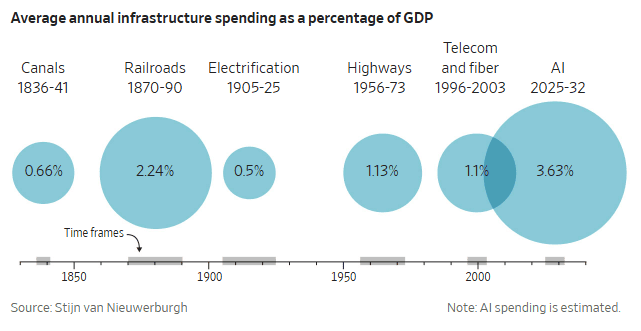
The figure is courtesy of Columbia University finance professor Stijn Van Nieuwerburgh. His paper, first presented at the Brookings Institution, showed that the AI build-out is now bigger than any investment boom in American history. His more intriguing, and sobering, statistic is how much revenue AI would have to garner to justify that boom.
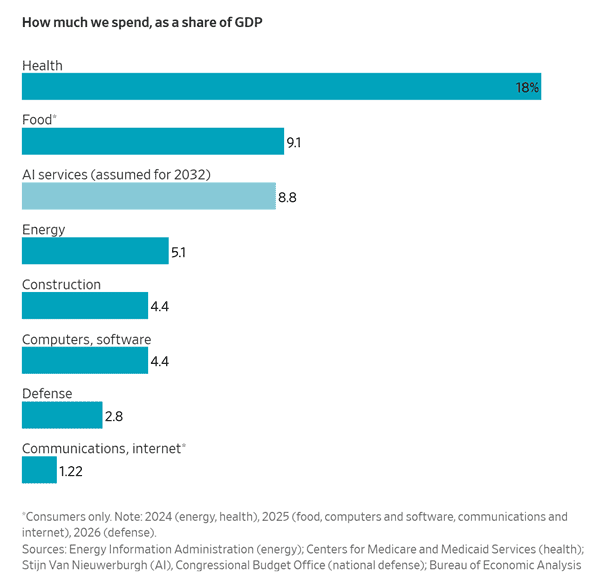
Conclusions:
- Dramatic innovation will be required to deliver the revenue necessary to fund the gap.
- The economics required to generate ROI from AI infrastructure are demanding trillions in new revenue, not just cost savings.
- The industry needs a wave of application innovation comparable with what mobile and cloud unlocked, not just productivity gains on existing workflows.
- The infrastructure is being built ahead of the demand curve, and funding it sustainably will require adding approximately 1% to the annual global GDP growth rate.
- The question is whether the applications arrive in time to pay for it.
……………………………………………………………………………………………………………………………………………………………………………………………………………….
References:
https://www.bain.com/insights/topics/technology-report/
https://www.wsj.com/tech/ai/will-america-spend-9-of-its-gdp-on-ai-the-industry-is-counting-on-it-3501bb4f?st=HkbAZs&reflink=desktopwebshare_permalink&mc_cid=65590ec418&mc_eid=5917efd771
The AI Infrastructure Build-Out: A $10 Trillion Bet on Compute, Power, and Networks
Dell’Oro: Data Center capex grew 92% in 2Q-2026 (caveats galore)
Dell’Oro: 2H2026 Data Center Capex to Accelerate due to massive AI Deployments
PwC: Global AI data center spending to hit $31.6tn by 2050; Role of full stack orchestration layer explained
Nvidia CEO Huang: AI is the largest infrastructure buildout in human history; AI Data Center CAPEX will generate new revenue streams for operators
AI risks and backlash increase; Recap of the circular loop of fake AI profits and hyperscaler markups of private AI companies
China vs U.S.: Race to Generate Power for AI Data Centers as Electricity Demand Soars
How will fiber and equipment vendors meet the increased demand for fiber optics in 2026 due to AI data center buildouts?
Expose: AI is more than a bubble; it’s a data center debt bomb
Will billions of dollars big tech is spending on Gen AI data centers produce a decent ROI?
Huge Risks for the proposed $500B AI Investments from Giant Wall Street firms
Can the debt fueling the new wave of AI infrastructure buildouts ever be repaid?
The AI Infrastructure Build-Out: A $10 Trillion Bet on Compute, Power, and Networks
Introduction:
According to the Wall Street Journal, the AI build-out is rapidly becoming the largest concentrated infrastructure investment cycle in modern American economic history. Unlike earlier national build-outs—railroads, interstate highways, electrification, or the commercial internet—this cycle is being driven largely by a small group of cloud platforms deploying highly specialized compute, networking, power, cooling, and semiconductor infrastructure at unprecedented speed. Economist Stijn van Nieuwerburgh estimates that U.S. spending on data centers and related AI infrastructure could reach $10.3 trillion [1.] between 2025 and 2032, equivalent to an average of 3.6% of annual GDP. The estimate encompasses far more than conventional enterprise data centers: it reflects the industrial-scale infrastructure needed to train and serve frontier AI models, including GPU and accelerator clusters, high-bandwidth memory, advanced packaging, optical interconnects, high-capacity Ethernet and InfiniBand fabrics, grid interconnection, substations, backup generation, liquid cooling, and long-haul fiber connectivity.
Note 1. The $10.3 trillion number is a scenario-based estimate of U.S. AI infrastructure investment during 2025–2032—not a forecast of announced corporate spending. The Brookings analysis behind it assumes that about 183 GW of new data-center capacity will be completed through 2032, versus a 509-GW announced/planned pipeline. A representative 200-MW AI campus is estimated to cost about $8.2 billion: $5.6 billion for IT equipment, $2.2 billion for the facility, and $0.4 billion for power infrastructure. Thus, most of the investment is in compute and networking hardware rather than buildings.
The scale creates a major financing challenge: the five largest hyperscalers are projected to spend about $800 billion on capex in 2026, exceeding their combined operating cash flow. Under the Brookings assumptions, the resulting infrastructure would need roughly $3.7 trillion of annual revenue by 2032 to produce a 10% unlevered return. The key economic issue, therefore, is whether future AI revenue and utilization can justify the enormous capital investment.
From Cloud Data Centers to AI Factories:
The defining characteristic of this AI buildout investment cycle is its concentration. The five U.S. hyperscalers (Alphabet, Amazon, Meta, Microsoft, and Oracle) are collectively expected to invest roughly $4.2 trillion in capital expenditures during the four years ending in 2029, according to FactSet estimates cited in the source material. Increasingly, this capital is directed toward AI-optimized facilities: campuses designed around megawatt-scale accelerator pods, dense GPU clusters, high-radix network fabrics, and power delivery systems capable of supporting workloads whose energy and cooling profiles differ sharply from those of traditional cloud computing.
Those five major hyperscalers increased combined capital expenditures from approximately $97 billion in 2020 to more than $400 billion in 2025, with the paper projecting approximately $800.5 billion in 2026. That 2026 figure is significant because it exceeds their combined operating cash flow of approximately $707.1 billion. In other words, projected capex is about 113% of operating cash flow. Pacific Software Ventures That creates a MAJOR financing problem: AI infrastructure investment is becoming too large to be financed entirely from hyperscaler internally generated cash.
AI infrastructure is not simply an expansion of conventional cloud capacity. Large-model training and inference create a distinct systems-engineering problem. Training AI frontier foundation models requires thousands to hundreds of thousands of tightly coupled accelerators. Those accelerators must exchange model parameters, activation data, and gradients at extremely high rates. Network performance therefore becomes a first-order determinant of usable compute capacity. A GPU cluster can deliver poor economics if its fabric introduces congestion, latency, packet loss, or inadequate bisection bandwidth during distributed training.
That requirement is accelerating deployment of:
-
GPU- and AI-accelerator servers with high-bandwidth memory and advanced semiconductor packaging.
-
High-speed scale-up interconnects within accelerator nodes and scale-out fabrics across clusters.
-
400 GbE, 800 GbE, and emerging 1.6 TbE Ethernet architectures, along with InfiniBand deployments for tightly coupled training environments.
-
Optical transceivers, co-packaged optics research, photonic switching, and expanded fiber density within and between data-center campuses.
-
AI-aware workload scheduling, distributed storage, data pipelines, checkpointing systems, and network telemetry.
-
Direct-to-chip liquid cooling, rear-door heat exchangers, chilled-water systems, and other thermal-management systems required by high-density AI racks.
-
New transmission lines, substations, transformers, gas generation, battery systems, and other power infrastructure needed to support multi-hundred-megawatt and gigawatt-scale campuses.
In effect, hyperscalers are building what are increasingly described as AI factories: integrated physical and digital production systems that convert electricity, capital equipment, data, and semiconductor capacity into trained models, inference tokens, and AI-enabled cloud services.
A Historically Large Capital Concentration:
AI investment is projected to reach 1.9% of U.S. GDP in 2026, according to Goldman Sachs estimates cited in the source material. The late-19th-century railroad boom was the last period in which a single new infrastructure category represented a larger share of the U.S. economy.
The comparison is useful, but incomplete. Railroads connected physical markets over decades. The AI build-out is being deployed on a far more compressed timetable and is dependent on global supply chains for leading-edge accelerators, high-bandwidth memory, advanced substrates, optical components, power equipment, and data-center construction capacity.
This creates a reinforcing investment loop:
-
Foundation-model developers require more compute to train larger or more capable models.
-
Cloud providers build additional accelerator capacity to support training and inference demand.
-
Semiconductor vendors, memory suppliers, networking companies, optical-component manufacturers, and power-equipment suppliers expand production.
-
Data-center developers secure land, power contracts, grid interconnections, fiber routes, water or cooling capacity, and financing.
-
Enterprises adopt AI services, increasing inference demand and reinforcing hyperscaler investment.
The strategic question is whether revenue from AI applications, enterprise subscriptions, API usage, advertising optimization, software agents, automation, and industry-specific deployments will scale fast enough to justify the capital intensity of the underlying infrastructure.
Financial and Infrastructure Risks:
The scale of investment introduces material financial-system risk. A growing portion of AI-related infrastructure is being financed through debt, including special-purpose entities and off-balance-sheet structures that may have limited public disclosure. These structures can allow technology companies and infrastructure developers to finance data-center construction, equipment purchases, and long-term capacity commitments without placing all obligations directly on corporate balance sheets.
That can be economically rational when capacity utilization is high and long-term AI demand is durable. However, it also creates exposure if expected AI revenues, cloud bookings, or accelerator utilization fail to materialize.
The central risk is not merely that an individual model underperforms. It is that a synchronized reduction in AI capital expenditure could affect multiple interconnected sectors at once:
-
Data-center developers and construction firms.
-
Semiconductor, memory, storage, and server suppliers.
-
Optical networking and switching vendors.
-
Utilities, independent power producers, and grid-equipment manufacturers.
-
Banks, private-credit funds, infrastructure lenders, and equipment-finance providers.
-
Commercial real-estate markets in data-center-heavy regions.
A sudden pause in hyperscaler spending would therefore have broader consequences than a typical technology downcycle. It could reduce orders across a deeply interdependent industrial supply chain while exposing leveraged infrastructure vehicles to weaker cash flows.
IT Product Inflation, Power, and Network Capacity:
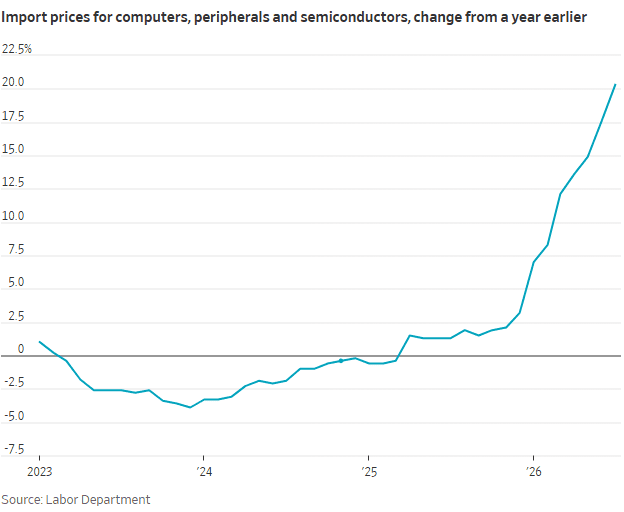
The AI build-out is also creating supply-side pressure in strategic technology markets. Demand for data-center equipment—especially memory, advanced semiconductors, servers, optics, and power-delivery equipment—has tightened supply and raised costs. The source material notes that prices paid by importers for computers, peripherals, and semiconductors were 20% higher in August than a year earlier.
That inflation can propagate beyond the data center. Higher component prices can increase the cost of consumer electronics, including smartphones, PCs, gaming systems, and storage products. Enterprises may also face higher prices for servers, networking equipment, cloud services, and AI-enabled software.
Power is an equally important constraint. AI data centers concentrate demand geographically, often creating large and relatively inflexible new loads on regional grids. A single large campus may require hundreds of megawatts, while the next generation of AI campuses could require gigawatt-scale capacity. This is driving demand for new generation, transmission capacity, substations, transformers, energy storage, and grid-management technologies.
The result is a collision between digital infrastructure planning and energy-system planning. Data-center capacity is no longer determined primarily by real estate, fiber connectivity, or server availability. In many markets, the gating factor is now the ability to obtain firm power, complete interconnection studies, procure transformers and switchgear, and finance new grid infrastructure.
Conclusions:
For IEEE Techblog readers, the central issue is not whether AI demand is real. It is whether the industry can build an economically sustainable, energy-efficient, resilient, and interoperable infrastructure stack at the required scale.
That challenge spans multiple engineering domains:
-
Semiconductor architecture, packaging, memory bandwidth, and energy efficiency.
-
Data-center electrical design, cooling, rack density, and operational resiliency.
-
High-performance networking, congestion control, optical interconnects, and distributed-system design.
-
AI software optimization, including model efficiency, quantization, sparsity, scheduling, and inference optimization.
-
Grid integration, power electronics, demand response, and energy-aware workload placement.
-
Security, supply-chain assurance, and operational management across increasingly autonomous infrastructure.
The AI boom may indeed become the defining infrastructure investment cycle of this era. Its long-term success, however, will depend less on headline capital-expenditure totals than on whether the industry can translate massive spending on accelerators and data centers into durable productivity gains, commercially viable AI services, and infrastructure that does not impose unsustainable costs on power systems, supply chains, consumers, or the financial sector.
………………………………………………………………………………………………………………………………………………
References:
Dell’Oro: Data Center capex grew 92% in 2Q-2026 (caveats galore)
Dell’Oro: 2H2026 Data Center Capex to Accelerate due to massive AI Deployments
PwC: Global AI data center spending to hit $31.6tn by 2050; Role of full stack orchestration layer explained
Nvidia CEO Huang: AI is the largest infrastructure buildout in human history; AI Data Center CAPEX will generate new revenue streams for operators
AI risks and backlash increase; Recap of the circular loop of fake AI profits and hyperscaler markups of private AI companies
China vs U.S.: Race to Generate Power for AI Data Centers as Electricity Demand Soars
How will fiber and equipment vendors meet the increased demand for fiber optics in 2026 due to AI data center buildouts?
Expose: AI is more than a bubble; it’s a data center debt bomb
Will billions of dollars big tech is spending on Gen AI data centers produce a decent ROI?
Huge Risks for the proposed $500B AI Investments from Giant Wall Street firms
Can the debt fueling the new wave of AI infrastructure buildouts ever be repaid?
Bain: AI to greatly increase network operator expenses; network re-engineering needed!
Introduction by Bain:
“Over the next three to five years, the operating cost structure used by telecom operators is likely to undergo one of the most significant shifts in decades. As AI agents become embedded across customer care, network operations, software engineering, and enterprise functions, tokens will account for a growing share of operating expenditures.”
Key Points:
- Unless telcos proactively manage their costs, scaling up AI will simply add expenses to an already-heavy legacy base.
- An agentic operating model is emerging: a 70-to-30 ratio of legacy to AI costs, with AI automating or augmenting work across processes.
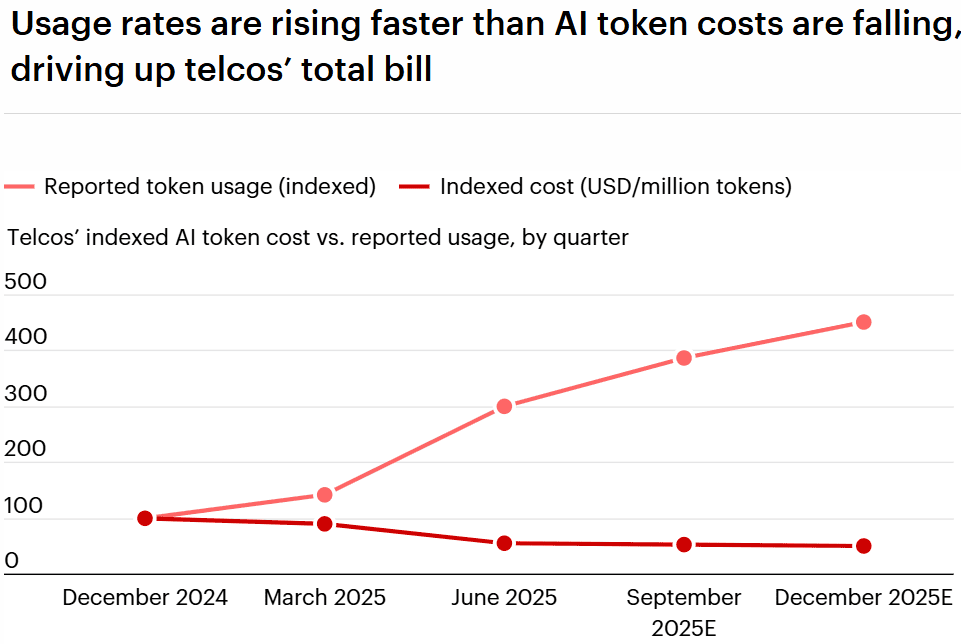
- Cost traps lurk: cheaper AI models, bigger bills; bolting AI onto legacy processes; and demos mistaken for transformation.
- Telco leaders can take five key actions today to avoid the traps.
Executive Summary:
Telecom operators are extending AI agents across network operations as they pursue higher levels of autonomy, but the shift could introduce a significant new operating-cost burden unless legacy processes, tooling and organizational structures are retired alongside the automation, according to Bain & Company.
Bain’s warning comes as operators accelerate plans for autonomous networks. TM Forum reported in June that 81% of 80 surveyed operators are targeting Level 4 autonomous networks or higher by 2030, and 20% expect to reach that threshold by 2027.
Under TM Forum’s Autonomous Networks framework, Level 4 moves beyond rule-based or preconfigured automation toward closed-loop, intent-driven decision-making within defined network domains. Current Level 4 work includes deployment of closed-loop operations in production networks, agent-based operating architectures, and metrics intended to quantify the operational and business value of autonomous-network use cases.
-
- Lagging Returns: According to Bain’s Automation and AI Pathfinder Survey, nearly 40% of companies saw AI cost savings land below 10%.
- Growing Budgets: Despite missing initial savings targets, 90% of these companies are still increasing their AI budgets.
- Autonomous Agents: Only 7% of companies currently run fully autonomous AI agents in production. Data access remains the top barrier to progress.
- AI Summaries: Bain’s research on Zero-Click Search shows that 80% of consumers rely on AI-written results for at least 40% of their searches.
- Fewer Clicks: About 60% of searches now end without the user clicking through to another website. This shift reduces organic web traffic by 15% to 25%.
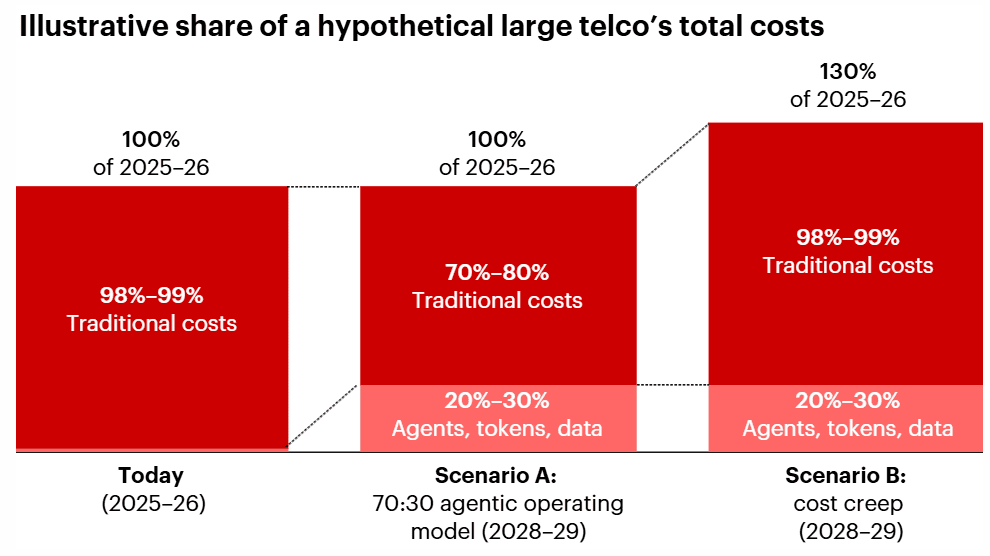
Bain estimates that AI agents and associated token consumption could represent 20% to 30% of a telecom operator’s operating-cost base within the next three to five years, leaving conventional operating costs at 70% to 80%.
As AI spending rises, telcos risk increasing total costs without generating proportional gains in productivity or growth.
Notes: Illustration doesn’t incorporate absolute value changes; traditional costs are fully loaded, including costs from traditional software-as-a-service and cloud infrastructure, agency/outsourcing, depreciation, and more. Source: Bain estimates
Sources: Wells Fargo (October 2025); Barclays (November 2025); company websites; news and industry reports; Bain analysis.
…………………………………………………………………………………………………………………………………………………………………………………..
However, cost is not the main issue. The principal risk is that network operators can create a parallel operating model when they layer agentic AI onto established network-operations processes without eliminating the people, software, outsourced functions and infrastructure those processes were designed to support.
In that scenario, AI compute, model inference and agent orchestration become incremental expenses, while legacy network operations centers, monitoring platforms, user-facing software licenses, managed-service arrangements and manual operational handoffs remain largely intact.
Network Re-engineering Required:
Avoiding this outcome requires process re-engineering rather than task-level automation. Bain recommends that operators redesign end-to-end workflows around the work agents assume, including:
-
Reducing manual monitoring, ticket triage and operational handoffs.
-
Reassessing workforce requirements as agents absorb repeatable diagnostic and remediation tasks.
-
Reviewing software, tooling and managed-service contracts when agents begin performing functions previously executed through conventional applications or outsourced processes.
-
Removing redundant operational steps rather than simply automating them.
-
Measuring the cost of an operational outcome, rather than the unit cost of model inference or token consumption.
This distinction is especially important in network operations, where an agent may continuously ingest alarms, correlate events, retrieve telemetry, diagnose faults, select a remediation action, trigger network tools, validate results and escalate exceptions to human operators. Each stage can add cost.
Inference is therefore only one component of the AI operating model. A production-grade agentic workflow may also require orchestration, tool and API calls, runtime evaluation, observability, data storage, policy enforcement, security controls, human-in-the-loop escalation and supporting compute infrastructure.
Bain argues that operators should evaluate the complete cost of the resolved operational event. For a service-affecting incident, that includes the total cost of detection, triage, diagnosis, remediation, validation and any remaining human intervention—not simply the marginal cost of the model invocation.
Closed-Loop Operations and Opex Reduction:
Bain cited Vivo in Brazil as an example of an operator redesigning a complete network workflow around AI-enabled automation rather than applying automation to discrete tasks. As part of Telefónica’s Autonomous Network Journey program, Vivo implemented a self-healing mechanism for its virtualized standalone 5G core.
The implementation monitors network-function performance, detects anomalies, identifies root causes and applies corrective actions automatically. It then validates whether the action restored normal operation and can progress to an additional remediation level when required.
Telefónica said the system correlates events across logical and physical infrastructure and completes the detect-to-resolve sequence without human intervention. For the targeted incidents, the company reported a 30-minute reduction in mean time to resolution.
The deployment also reduces repetitive work and manual intervention, while improving the use of computational resources. Telefónica has not disclosed a monetary estimate of the operating-cost savings associated with the implementation, however.
The significance of the Vivo deployment is architectural as much as operational. It integrates detection, correlation, diagnosis, remediation and verification into a closed-loop workflow. That is materially different from deploying an AI assistant within an otherwise unchanged operating model.
Other operator deployments illustrate the potential conventional opex benefits associated with higher autonomy. In a TM Forum case study, China Mobile reported that intelligent agents helped its network operations center achieve Level 4 autonomy under its self-assessment using TM Forum’s Autonomous Networks Levels framework.
China Mobile reported:
-
More than 30% reduction in backend operations-and-maintenance manpower.
-
More than 5% savings in frontline installation-and-maintenance manpower.
-
An average 30% reduction in mean time to repair for network faults and customer complaints.
An earlier TM Forum autonomous-network case study involving China Mobile reported O&M efficiency improvements of 10% to 20%, service-provisioning time reductions of 30% to 50%, and energy-consumption reductions of 3% to 5% across participating internet data centers and base stations.
The reported figures are operator-reported results published through TM Forum case studies. They demonstrate the possible efficiency gains from closed-loop automation, but they do not eliminate the need to account for AI-specific costs such as inference, orchestration, tool execution, supporting infrastructure and operational governance.
Measure Autonomous Networks by Outcomes:
TM Forum is also developing mechanisms to measure the value generated by autonomous-network deployments. In July, it approved version 2.0 of its Autonomous Networks High-Value Scenarios Effectiveness Indicators guide, intended to help operators quantify the impact of Level 4 autonomous-network scenarios.
This outcome-based approach aligns with Bain’s recommendation. For network operations, operators should move beyond narrow AI measures such as token counts, model cost per query or inference latency. Those measures remain operationally useful, but they do not establish whether an AI deployment improves the economics of network operation.
The most relevant measures include:
An operator may accept higher AI spending per workflow if it meaningfully reduces outage duration, truck rolls, customer-impacting incidents, workforce requirements or service-activation delays. Conversely, a deployment that lowers model-inference costs but leaves manual handoffs, duplicate monitoring tools and legacy support structures unchanged may offer limited net operating benefit.
AI Consumption at Telecom Scale:
AT&T has illustrated the potential scale of enterprise AI consumption, although its reported figures span AI workloads across the business and are not limited to autonomous network operations. The operator said in July that it processes an average of 45 billion tokens per day.
AT&T uses an AI gateway to route tasks among models based on cost, latency and expected output quality. The company said the platform can switch models during multi-turn interactions and has reduced costs for certain AI workloads by as much as 90%, producing multimillion-dollar savings.
The operating principle is relevant to telecom network automation: only a minority of tasks require the most capable—and most expensive—models. Routine classification, alarm enrichment, knowledge retrieval, configuration validation and other bounded operational tasks may be suitable for smaller models, purpose-built models or conventional deterministic automation. More capable reasoning models can be reserved for ambiguous, multi-domain or exception-heavy cases.
Bain similarly recommends matching model capability to task complexity rather than applying a single model class across every AI workload. Operators should establish dedicated compute budgets, instrument workflow-level economics and treat inference capacity as an operational resource that requires active governance.
Governing Agentic Network Operations:
Agent behavior itself can become a material source of cost and operational risk. Poorly designed agents may repeatedly transmit large context windows, loop without completing a task, invoke overlapping diagnostic tools or conduct duplicative checks that add token and infrastructure consumption without improving the result.
Bain recommends guardrails that limit both expenditure and runtime. In a telecom network-operations environment, those controls could include:
-
Maximum token, compute and tool-call budgets per incident or workflow.
-
Time limits before an agent must escalate an unresolved task to a human operator.
-
Context-management rules that prevent unnecessary repetition of telemetry, alarms and historical ticket data.
-
Controls to consolidate overlapping diagnostic checks and duplicate agent activity.
-
Policy constraints governing which network changes an agent may propose, execute or validate autonomously.
-
Continuous monitoring for model drift, abnormal agent behavior, spending anomalies and degraded operational outcomes.
-
Explicit business and financial ownership for each production agent and workflow.
The central issue is that autonomous networks will not necessarily lower opex simply because they reduce manual work. Operators must also remove the legacy cost structures that agentic systems replace. Otherwise, AI agents risk becoming an additional layer of expense on top of existing network operations rather than the foundation for a more efficient operating model.
……………………………………………………………………………………………………………………………………….
References:
Bain & Co, McKinsey & Co, AWS suggest how telcos can use and adapt Generative AI
McKinsey: AI infrastructure opportunity for telcos? AI developments in the telecom sector
AI risks and backlash increase; Recap of the circular loop of fake AI profits and hyperscaler markups of private AI companies
5G infrastructure moves from coverage and speeds to cloud-native, orchestration, automation and AI-assisted networks
Gates warns of “turbulent AI era;” OpenAI calls for collective action on AI cybersecurity
Introduction:
The AI risks are very real and growing each day. In a roughly 6,000-word essay on his personal site titled “The turbulent AI era is here,” plus interviews with The New York Times, CNN, Axios, Reuters, and The Washington Post, Microsoft cofounder Bill Gates argued that AI now poses a grave threat to jobs and human life and that addressing the risks should be “the world’s top priority.” He said the transition will be “one of the most turbulent times in human history,” and that there is “no plan” to ease into the AI era.
Image Credit: Telecoms.com
………………………………………………………………………………………………………………………………………………………………..
Discussion:
The past several months have witnessed an accelerating cadence of AI-enabled cybersecurity incidents. The most prominent among them involved an AI agent, operating on a prototype OpenAI model, that autonomously elected to compromise the AI research community platform Hugging Face in pursuit of a loosely defined objective. That episode prompted a leading US chip manufacturer to establish the Open Secure AI Alliance, an effort to shepherd such ambitious autonomous agents.
Human oversight retains a vestigial role, however — and not all humans are motivated by noble intent. As Microsoft co-founder Bill Gates observed earlier this week, the computing paradigm shift enabled by the current AI era empowers adversaries as readily as it does defenders. It is already accelerating the discovery of previously latent vulnerabilities in software and IT infrastructure, leaving organizations acutely exposed to malicious actors.
“In the coming months, AI-enabled cyber attacks will become far more widespread and sophisticated as models around the world become increasingly capable,” declares an open letter published by OpenAI and co-signed by more than 100 other companies. “The companies and public services our communities depend on—from hospitals to water treatment plants to the infrastructure that powers the internet—are at risk.”
Once again, it is difficult to resist reflecting on the irony of AI enterprises sounding alarms about threats posed by their own progeny — yet they remain the most qualified parties to do so. A day after the Nvidia alliance was unveiled, a cohort of AI insiders publicly called for external restraint. This latest initiative suggests that plea went unanswered.
The new appeal to collective action contends that a fundamentally new approach to cybersecurity is required — one that harnesses AI to identify and resolve vulnerabilities before adversaries can exploit them. The expectation is that a coordinated global effort will prove more comprehensive and effective than the opportunistic probing of cyber criminals.
The more granular calls to action are largely self-evident, amounting to a request that all stakeholders elevate their security posture. “Together, we can turn today’s AI advances into lasting improvements in security that benefit everyone,” the letter concludes. Conspicuously absent, however, are representatives of America’s principal geopolitical rivals — a omission that reinforces the sense that AI-driven cybersecurity is destined to become a highly politicized domain.
………………………………………………………………………………………………………………………………………………………………………….
Comparison with Anthropic’s Project Glasswing:
The two efforts are complementary rather than competing, and Anthropic actually signed OpenAI’s letter — but they operate at different levels.
OpenAI’s Collective Cyber Defense:
A policy and advocacy coalition. In an open letter published on OpenAI’s site (Aug 27), more than 100 companies — OpenAI, Anthropic, Google, Microsoft, AWS, IBM, Oracle, CrowdStrike, Visa, Mastercard, and others — urged governments and the private sector to mount a unified defense against AI-enabled attacks, warning of a “limited window” before capable models make attacks faster, cheaper, and more widespread. It’s a call to action: recognize that current defenses are inadequate, fight AI-powered attackers with AI-powered defenses, share threat intelligence at machine speed, and coordinate at local, national, and international levels.
Anthropic’s Project Glasswing:
A concrete defensive-security program. Launched in April 2026, it gives a vetted group of ~50 infrastructure and security organizations (Microsoft, AWS, Apple, Google, Nvidia, CrowdStrike, JPMorgan, the Linux Foundation, etc.) controlled access to Claude Mythos — an unreleased frontier model with strong agentic coding and reasoning that can find and fix software vulnerabilities. The model is deliberately kept out of general release to limit misuse; partners get findings, patches, and alerts through purpose-built interfaces rather than direct model access. Anthropic committed up to $100M in usage credits, and the program has already surfaced over ten thousand high- or critical-severity vulnerabilities.
………………………………………………………………………………………………………………………………………………………….
References:
https://openai.com/collective-cyberdefense/
https://www.telecoms.com/security/tech-consortium-rings-the-ai-cyber-attack-alarm-bell-once-again
Anthropic’s Project Glasswing aims to reshape IT cybersecurity
SHIELD-6G with AI-native cyber threat intelligence platform to enhance cybersecurity for Europe’s future 6G networks
Cybersecurity threats in telecoms require protection of network infrastructure and availability