Uncategorized
Analysis: Taara Demonstrates 14-km Free-Space Optical Link with AT&T and Nokia
Introduction:
Taara, an independent private company spun out of X, Google’s Moonshot Factory, and a developer of high-speed, high-capacity wireless optical communications, announced an expansion of its commercial activities targeting enterprise and federal government customers in the U.S. IEEE Techblog has written about the company previously (see References below).
Following a successful deployment with AT&T at the world’s largest soccer event at at MetLife Stadium, NJ, Taara demonstrated its Lightbridge Free Space Optics (FSO) system at Texas Tech University. The demonstration illustrated how narrow, invisible beams of light can deliver high-capacity connectivity where rapid deployment, security and operational flexibility are important for mission-critical applications.
Conducted in collaboration with AT&T and Nokia Federal Solutions, the demonstration carried data across a 14-km path between a university rooftop and a mobile cell site, known as a cell on wheels (COW). The demonstration was presented to enterprise, state and federal government stakeholders as part of Texas Tech University’s Critical Infrastructure Telecom Ecosystem Incubator.
The significance is that high-capacity optical connectivity can be established without installing fiber along the entire route or obtaining licensed radio-frequency spectrum. However, free-space optical communications have distinctive propagation and availability limitations that must be considered when evaluating their use in telecommunications infrastructure.
Free-Space Optical (FSO) Communications Explained:
Free-space optical communications transmit data using highly focused beams of invisible near-infrared light through the atmosphere rather than through a physical optical fiber. The basic architecture consists of two optical terminals, each containing an optical transmitter and receiver. The transmitting terminal converts electrical data into modulated optical signals, which are directed toward the receiving terminal. A photodetector at the receiving end converts the optical signal back into electrical data. Unlike conventional fiber-optic communications, the optical signal travels through an unguided atmospheric path. This eliminates the need to install physical cable between the two endpoints while retaining the potential for very high data rates and low latency.
Taara Lightbridge supports bidirectional transmission of up to 20 Gbps over distances of up to 20 km, according to the company’s published specifications. Its lightweight terminals can be installed on rooftops, towers and other elevated structures with a clear line of sight.

Image Credit: Communications Physics article “Towards high-capacity and robust free-space optical communications,” by Jian Wang, Jinfeng Liu & Chengkun Cai
……………………………………………………………………………………………………………………………………………………………………………..
FSO technology is particularly attractive for:
- Wireless backhaul and fronthaul connectivity for cellular networks.
- Temporary high-capacity connections for major events and emergency deployments.
- Enterprise and campus network extensions.
- Connectivity between data centers and other facilities.
- Physically diverse network paths that reduce dependence on a single fiber route.
AT&T’s 80,000-Spectator Deployment at MetLife Stadium in New Jersey:
An important commercial example involved AT&T’s deployment of two Taara Lightbridge links at MetLife Stadium in New Jersey. The installation connected more than 80,000 spectators during a major international soccer event. According to Taara, the links were installed in a matter of hours and delivered up to 20 Gbps during the event.
Importantly, the deployment combined the optical links with a millimeter-wave radio backup. Taara reported 99.999% availability for the combined hybrid connection. This distinction is important. The five-nines availability figure applies to the combined optical and millimeter-wave arrangement, not to the standalone optical link. The deployment illustrates the value of combining different transmission technologies to improve network resilience. AT&T is also evaluating Taara links for broader network applications.
Advantages of FSO Compared with Fiber and Radio:
FSO offers several potentially important advantages for telecommunications operators and enterprise network providers.
Rapid deployment: Unlike fiber construction, FSO does not require trenching, cable installation, or lengthy rights-of-way negotiations along the transmission path. This can be particularly valuable for temporary installations, disaster recovery and locations where fiber construction is difficult or expensive.
High capacity: Optical wavelengths provide substantial bandwidth potential. Taara specifies up to 20 Gbps bidirectional throughput for Lightbridge, making it relevant to high-capacity wireless backhaul applications.
No licensed RF spectrum: Because the transmission uses optical rather than radio-frequency signals, FSO does not require licensed RF spectrum. This can be advantageous in congested wireless environments.
Low latency: Optical propagation through air is close to the speed of light in vacuum, avoiding the additional propagation delay associated with optical fiber. Actual end-to-end latency also depends on terminal electronics and network equipment.
Physical network diversity: An FSO link can provide an alternative physical path alongside fiber infrastructure. This can reduce dependence on a single cable route, provided that the optical path itself is sufficiently protected and does not share the same physical vulnerabilities.
FSO’s Risks and Technical Limitations:
Despite its considerable potential, FSO is not a universal replacement for fiber or conventional wireless transmission. Its principal weakness is that the optical signal must propagate through an uncontrolled atmospheric environment. Taara’s own specifications acknowledge 90% average availability at 10 km for its Lightbridge system. That is a substantial limitation for a standalone carrier connection. Several engineering challenges affect link reliability and availability:
1. Atmospheric attenuation and weather
Fog is one of the most serious challenges for terrestrial FSO. Water droplets scatter and attenuate near-infrared optical signals, potentially reducing received optical power below the level required for reliable communications.
Heavy rain, snow, dust and other atmospheric conditions can also degrade performance. Atmospheric turbulence can cause fluctuations in signal intensity, beam distortion and variations in received optical power.
Taara’s own technical FAQ acknowledges these limitations. Its published averages indicate approximately 95% annual availability at 5 km and 90% at 10 km for Lightbridge links. The company also reports that fog causes significantly greater attenuation than is typically experienced by millimeter-wave systems.
These figures demonstrate why advertised maximum transmission distance should not be confused with guaranteed service availability.
2. Line-of-sight requirements and physical obstruction
FSO requires a clear optical path between the two terminals. Buildings, trees, construction equipment, vehicles and other physical obstructions can interrupt the connection.
Unlike radio systems that may support non-line-of-sight propagation through reflection or diffraction, a highly directional optical link generally cannot maintain its connection when the direct path is blocked.
Consequently, careful site surveys, rooftop placement and protection of the optical path are essential.
3. Pointing, acquisition and tracking
Because the optical beam is highly directional, the transmitting and receiving terminals must remain accurately aligned.
Wind-induced movement of towers, rooftop structures, mounting equipment and other mechanical disturbances can cause pointing errors. Building movement and thermal expansion can also affect alignment.
Automatic acquisition and tracking mechanisms are therefore important components of practical FSO systems. Maintaining alignment over long distances is a significant engineering challenge.
4. Availability and network redundancy
FSO should not automatically be treated as a fiber replacement for applications requiring continuous connectivity.
Operators need to engineer around atmospheric outages and physical obstructions through redundant paths, adaptive transmission rates, backup radio links or alternative fiber routes.
Taara’s AT&T stadium deployment provides a useful example: combining FSO with millimeter-wave radio backup allowed the network to achieve the vendor-reported five-nines availability figure.
For mission-critical applications, the relevant engineering metric is not simply peak throughput. It is sustained throughput and service availability under actual operating conditions.
5. Security considerations
The narrow, highly directional optical beam can make interception more difficult than with broadly propagated wireless signals. FSO also avoids the licensed RF spectrum and radio-frequency interference issues associated with conventional wireless links.
However, optical transmission should not be equated with inherently secure communications. Physical access to the optical path, endpoint compromise, deliberate obstruction and attacks on network equipment remain relevant security considerations.
Encryption, authentication, access controls and network monitoring are still necessary.
Taara’s Next Technology Development: Integrated Photonics and Optical Phased Arrays:
Beyond its deployed Lightbridge technology, Taara is developing a more compact integrated-photonics platform called Taara Photonics.
Introduced in February 2026, the platform moves important optical communication and beam-control functions into a small silicon-based photonic module. Its central technology is an optical phased array (OPA) containing more than 1,000 miniature, software-controlled light emitters.
By electronically controlling the phase of the emitted light, an OPA can steer and track optical beams without relying on conventional moving mechanical components.
Taara’s first product based on this platform, Taara Beam, is specified for up to 25 Gbps bidirectional throughput over distances of up to 10 km. The approach could eventually reduce terminal size, complexity and deployment costs while enabling more flexible optical wireless network architectures.
However, integrated photonics and electronic beam steering do not eliminate the fundamental atmospheric propagation challenges of FSO. Fog attenuation, turbulence, physical obstructions and link availability must still be addressed.
It is also important to distinguish this newer platform from the Lightbridge equipment used in the 14-km Texas demonstration. The Texas demonstration does not establish the operational performance or weather resilience of Taara Beam.
Wireless Telecom Industry Implications:
Taara’s demonstrations illustrate the potential role of wireless optical communications as another component of high-capacity telecommunications infrastructure.
FSO is particularly attractive where fiber construction is prohibitively expensive, deployment schedules are demanding, or an additional physically diverse connection is needed. It can complement fiber and millimeter-wave radio rather than compete with either technology in every application.
The technology could also become relevant to data-center interconnection, where increasing traffic volumes and the need for additional network capacity are creating demand for alternative connectivity solutions. However, practical deployment will depend on distance, atmospheric conditions, site geometry, redundancy requirements and total cost of ownership. The most important consideration for network operators is whether FSO can deliver sufficient sustained capacity and availability at a competitive cost under the specific environmental conditions of each deployment.
The company’s hybrid approach is probably the correct commercial direction, but it also suggests that FSO’s role is to complement fiber and RF, not replace them.
Conclusions:
Taara’s 14-km demonstration with AT&T and Nokia illustrates the growing potential of free-space optical communications to provide high-capacity connectivity without the construction costs, delays and physical constraints of fiber deployment. Taara appears to have made meaningful progress in equipment design, photonics integration, link planning and network redundancy. Its deployments deserve serious attention, rather than dismissal based on the failures of the earlier FSO industry from 1998-2002.
FSO is particularly attractive for wireless backhaul, temporary high-capacity links, enterprise connectivity and network-route diversity. However, impressive peak data rates and transmission distances do not establish carrier-grade reliability. Atmospheric attenuation—especially from fog—line-of-sight obstructions and precise beam-alignment requirements remain significant engineering challenges.
Consequently, FSO is best deployed with appropriate redundancy, including fiber or millimeter-wave backup where uninterrupted service is required. Taara’s newer integrated-photonics and optical phased-array development could make optical wireless terminals smaller, less mechanically complex and easier to deploy. But it does not eliminate the fundamental limitations of atmospheric optical transmission.
We believe that FSO is a promising complementary technology for expanding high-capacity network connectivity, not a universal replacement for fiber. Its commercial success will depend on demonstrating sustained throughput, predictable availability and competitive total cost of ownership under real-world operating conditions.
……………………………………………………………………………………………………………………….
References:
https://x.company/blog/posts/taara-graduation/
https://www.taaraconnect.com/post/introducing-taara-photonics-and-beam
https://support.taaraconnect.com/en/faq/design-specs
https://www.nature.com/articles/s42005-026-02947-3
Taara Lightbridge Pro: an ultra reliable wireless optical communications system for 5G mobile backhaul
Google X spin-out Taara and Digicomm International partner to offer high speed wireless communications
2021 Optical Fiber Conference (OFC) Highlights and Links to Videos
OIF Launches 7 New Projects Targeting 448G Electrical Interfaces, 200G Bidirectional Optics and Coherent Link Security
Editorial Note:
ChatGPT was used to assist with historical background research, technical analysis, and editorial suggestions concerning OIF’s role in optical networking interoperability and its relationship with ITU-T. The author reviewed and approved all additions with modifications for technical accuracy.
Introduction:
The Optical Internetworking Forum (OIF) has initiated seven new technical projects addressing the rapidly growing bandwidth, power-efficiency, optical connectivity and security requirements of AI infrastructure and next-generation data center networks. The projects were announced November 9th after the OIF Q4 2026 Technical and Market Awareness & Education Committees meeting, held November 2–5 in Bangkok, Thailand.
More than 200 representatives from OIF member companies attended the meeting. The seven initiatives span high-speed electrical interfaces, bidirectional optical transmission, external laser sources, pluggable module management and coherent optical security. Collectively, they address important interconnection challenges as AI computing architectures require increasingly high-bandwidth connections between processors, switches, servers and data centers. All seven initiatives are at project-start stage. No implementation completion dates or independently verified performance gains were announced.
OIF’s Role in Optical Networking Interoperability:
Founded in 1998 (this author attended the very first OIF meeting in September 1998), the Optical Internetworking Forum (OIF) has played an important role in advancing interoperable optical networking technologies. Its work has evolved from DWDM optical transport interfaces to optical control-plane technologies, including the ITU-T Automatically Switched Optical Network (G.ASON) and IETF Generalized Multi-Protocol Label Switching (GMPLS), and now encompasses high-speed electrical interfaces, coherent optics, advanced optical packaging and link security.
OIF’s industry-driven Implementation Agreements complement formal standards developed by organizations such as ITU-T and IEEE. By bringing network operators, system vendors, optical component suppliers and test-equipment manufacturers together, OIF helps translate emerging technology requirements into interoperable industry implementations.
Seven New OIF Technical Projects:
1. Energy Efficient Interfaces (EEI) – 448G Retimed Transmit Linear Receive (RTLR)
This project will develop an Implementation Agreement (IA) for a 448 Gbps-per-lane electrical interface using a half-retimed architecture. RTLR combines a retimed transmit path with a linear receive path, offering another architectural option alongside fully retimed and linear interfaces.
The objective is to support higher electrical bandwidth while addressing power consumption, signal integrity and implementation complexity. It complements OIF’s expanding CEI-448G portfolio, which is intended to support the next generation of AI data center interconnects.
2. Bidirectional O-band Single-Mode Fiber (SMF) 200G/Lane
OIF will develop an IA for bidirectional optical connectivity operating at 200 Gbps per lane over O-band single-mode fiber.
Bidirectional transmission offers the potential to increase fiber utilization by supporting two-way communications over a fiber connection. This is relevant to AI scale-up architectures, where large numbers of high-bandwidth connections must be established between compute devices and switching infrastructure.
The project addresses the need for greater optical bandwidth density without proportionally increasing fiber infrastructure.
3. External Laser Small Form Factor Pluggable (ELSFP) IA 3.0
This project will develop the third revision of OIF’s ELSFP Implementation Agreement to address evolving requirements for external laser sources.
External laser architectures are important to co-packaged optics (CPO) and other advanced optical packaging approaches. Separating laser sources from optical engines can provide flexibility in thermal management, laser replacement and system design.
4. Type-3 Elongated ELSFP Supporting Electrical Power Class 8 (40W)
A related project will define an elongated Type-3 ELSFP variant supporting Electrical Power Class 8, rated at 40W.
This higher electrical power capability addresses the requirements of increasingly demanding external laser applications. It is important to distinguish the 40W electrical power classification from optical output power: the announcement does not specify 40W of emitted optical power.
Together, the two ELSFP projects reflect the importance of external laser technology as optical connectivity moves toward higher bandwidth density and more advanced packaging architectures.
5. MACsec Management for Pluggable Modules
OIF will develop an IA addressing management of Media Access Control Security (MACsec) functionality within pluggable modules.
MACsec, specified by IEEE 802.1AE, provides Layer 2 Ethernet link security, including confidentiality, integrity and data-origin authentication.
Bringing MACsec management into pluggable modules creates additional opportunities for consistent security configuration and management across optical networking equipment. This is increasingly relevant as high-speed optical links become integral components of distributed AI and cloud infrastructure.
6. CMIS Management Communication Interface (MCI) over USB
The Common Management Interface Specification (CMIS) is widely used to manage optical and electrical pluggable modules and communicate their capabilities and operating status to host systems.
The new project will develop a USB-based Management Communication Interface for CMIS. This provides another mechanism for communicating with and managing pluggable modules.
Standardized module management is essential as networks incorporate increasingly sophisticated optical components from multiple suppliers. It can simplify system integration, diagnostics and maintenance while supporting interoperability across vendors.
7. ZRsec (FlexOsec) for Coherent Optical Interfaces
The final project will define a common implementation approach for FlexOsec Layer 1 encryption in ZR coherent optical applications.
ZR coherent interfaces have become important building blocks for high-capacity data center interconnect (DCI), allowing routers and switches to connect over single-wavelength optical links.
As these links carry increasingly valuable AI, cloud and enterprise traffic, standardized encryption becomes an important consideration. A common approach to Layer 1 security can help vendors develop interoperable coherent optical implementations with consistent security capabilities.
Comment & Analysis:
The Bangkok OIF meeting initiatives span several complementary technical domains rather than a single data rate transition.
- The EEI-448G RTLR effort adds another electrical interface option alongside conventional retimed and linear architectures. Signal integrity, component power and implementation complexity will determine its suitability in next-generation high-density network equipment; the completed specification and interoperability testing will determine practical operating boundaries.
- Bidirectional 200G-per-lane O-band optics could help engineers address fiber utilization in AI scale-up links, although the project announcement does not define a specific accelerator-fabric protocol or system deployment.
- The two ELSFP projects address external laser sourcing and electrical power delivery, considerations for advanced optical packaging architectures. Importantly, a 40W module electrical power class is not a statement of optical output power.
- Security and module management are becoming integral to interface standardization. MACsec management in pluggable modules addresses Ethernet link-level functionality, while ZRsec/FlexOsec targets encryption in coherent optical applications. CMIS communication over USB concerns management access rather than payload bandwidth.
An important aspect of these initiatives is their coverage of multiple layers of the optical networking ecosystem. The 448G electrical and 200G optical projects address physical-layer bandwidth scaling, while the ELSFP initiatives address optical source architecture and power delivery. CMIS and MACsec management address operational interoperability and Ethernet link security, while ZRsec/FlexOsec extends security into coherent optical transport. Collectively, these projects reflect OIF’s continuing role in coordinating industry requirements across electrical, optical and management interfaces.
Impact on the Optical Networking Industry:
The seven initiatives address several interdependent challenges facing the optical networking industry.
- Bandwidth scaling: The 448G-per-lane electrical interface project and 200G-per-lane bidirectional optical project address the need for higher bandwidth density in AI computing systems. As accelerator clusters grow, electrical and optical interconnects must support increasingly demanding traffic volumes without creating unacceptable power and latency penalties.
- Power efficiency and optical packaging: The two ELSFP projects highlight the importance of external laser architectures in advanced optical systems. Higher-power laser applications, co-packaged optics and increasingly dense optical engines require standardized interfaces and management capabilities. Power consumption and thermal management remain major engineering constraints.
- Interoperability and operational management: CMIS and MACsec management projects address the growing complexity of managing and securing pluggable optical modules. Standardized management interfaces can reduce integration difficulties and improve compatibility among equipment and component suppliers.
- Optical link security: ZRsec/FlexOsec extends the industry’s interoperability efforts into coherent optical link encryption. Security must evolve alongside bandwidth and reach rather than remain an afterthought in next-generation network architectures.
These developments reflect challenges discussed by OIF President Nathan Tracy and board member Cathy Liu of Broadcom in a February 19, 2026 Lightwave interview.
Mr. Tracy emphasized that AI and machine-learning operators face difficult trade-offs involving power consumption, transmission reach and the physical connections required between GPUs and other computing resources. He also noted that the industry must agree on electrical and optical interfaces, modulation approaches and latency requirements. The interview highlighted OIF’s ongoing work on CEI-448G, energy-efficient interfaces, coherent optics, CMIS and interoperability. It also emphasized that developing practical solutions requires collaboration among OIF, IEEE, the Ethernet Alliance and other industry organizations. The seven newly initiated projects represent concrete follow-on technical work addressing several of those challenges.
Conclusions:
OIF’s latest initiatives illustrate how optical networking requirements are evolving beyond simply increasing transmission speeds. AI infrastructure requires coordinated advances in electrical signaling, optical connectivity, laser technology, module management and security.
The 448G electrical and 200G bidirectional optical projects are particularly relevant to scaling high-density AI networks. Meanwhile, external laser source development and standardized module management address the power, packaging and operational challenges associated with increasingly sophisticated optical systems.
As coherent optical links become more integral to data center interconnection, strong security will be needed, especially standardized encryption and management capabilities.
As noted above, these seven initiatives are newly initiated technical projects, not completed Implementation Agreements or commercially deployed solutions. Their eventual industry impact will depend on technical consensus, specification development, multi-vendor interoperability testing and commercial implementation.
OIF’s work is important because it brings optical component suppliers, system vendors, network operators and test-equipment companies together to develop common technical approaches. In an AI infrastructure market increasingly constrained by bandwidth, power consumption, physical connectivity and security, that interoperability work is becoming essential to scaling optical networking.
Looking Ahead to 2027:
OIF’s 2027-Q1 Technical and MA&E Committees Meeting will take place Feb. 22–26, 2027, in Charleston, South Carolina.
OIF is where the optical networking industry’s interoperability work gets done. With more than 25 years of effecting forward change in the industry, OIF represents the dynamic ecosystem of 180+ industry leading network operators, system vendors, component vendors and test equipment vendors collaborating to develop interoperable electrical, optical and control solutions that directly impact the industry’s ecosystem and facilitate global connectivity in the open network world. Connect with OIF on LinkedIn, on X, on Bluesky and at https://www.oiforum.com/.
………………………………………………………………………………………………………………………………………………………………………………………………
Sidebar: OIF–ITU-T relationship today (November 2026):
The OIF and ITU-T Study Group 15 (SG15) maintain an active, formal technical liaison relationship. They coordinate optical transport standards, interface specifications, management and interoperability—not by duplicating each other’s work, but by exchanging requirements, technical information and implementation experience. Current evidence includes SG15’s March 2026 liaison to OIF on timestamping accuracy with optical pluggables, followed by OIF’s June 2026 response. OIF is also listed as a liaison organization for current SG15 work on the G.709.1 and G.709.5 optical transport Recommendations.
SG13’s relationship with OIF is less direct. SG13 develops broader future-network architecture, AI-native networking and computing/network integration requirements. Those requirements feed into SG15’s optical-network work, including its ION-2030 framework. SG15 identifies OIF as a potential cooperating organization for optical transport and AI-related optical networking. Thus, the practical OIF relationship today is centered on SG15, with SG13 influencing the broader architectural and requirements environment.
OIF Implementation Agreements are industry-developed specifications intended to facilitate interoperable implementations; they are not ITU-T Recommendations. Liaison and technical coordination between the organizations help ensure that industry implementation requirements and international standards development remain aligned.
| Organization / area | Primary responsibility today | Relationship with OIF |
|---|---|---|
| OIF | Industry-driven implementation agreements and interoperability for optical and electrical interfaces, coherent optics, pluggable modules and related technologies | Develops specifications and implementation agreements; coordinates with standards bodies to promote interoperable implementations |
| ITU-T SG15 | Optical transport, OTN, optical access, fibers, components, physical infrastructure, transport control and management | Direct, active liaison. Exchanges technical liaison statements; OIF is identified in relevant SG15 standards work, including G.709.1 and G.709.5 |
| ITU-T SG13 | Future network architecture, AI/ML for networks, network softwarization, orchestration and computing/network integration | Primarily indirect coordination. Its future-network and AI requirements inform SG15’s optical-network work; current evidence does not establish the same level of direct OIF liaison as SG15 |
In summary, OIF remains an industry implementation and interoperability forum, while ITU-T SG15 provides the international standards framework for optical transport and infrastructure. Their relationship is complementary and active. ITU-T SG13 shapes the broader future-network requirements that increasingly influence this work.
…………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………….
References:
https://convergedigest.com/oif-seven-projects-448g-ai-optics-zrsec-2026/
OIF Project Highlights: Interoperable 1600ZR+ & Retimed Tx Linear Rx Specs Energy Efficient Interfaces; Common Management Interface Specification (CMIS) Whitepaper
Light Counting: optical transceiver sales surge; IEEE 802.3 and ITU-T optical transport standards explained/UEC addendum
Verizon’s $1 Billion Google Dark Fiber Deal Highlights Importance of Optical Networks
Analysis: Nokia’s strong growth in Optical Networks and AI network infrastructure
NTT’s IOWN is (finally) evolving to an All Photonics Network (APN); Physics based AI for enterprise OT
PsiQuantum Targets AI Data Center Networks with Silicon-Photonic Optical Switching
Industry Analysts: Important Optical Networking Trends for 2023
AT&T’s Fiber Expansion Strengthens Its Converged Wireless and Home Broadband Strategy
Introduction:
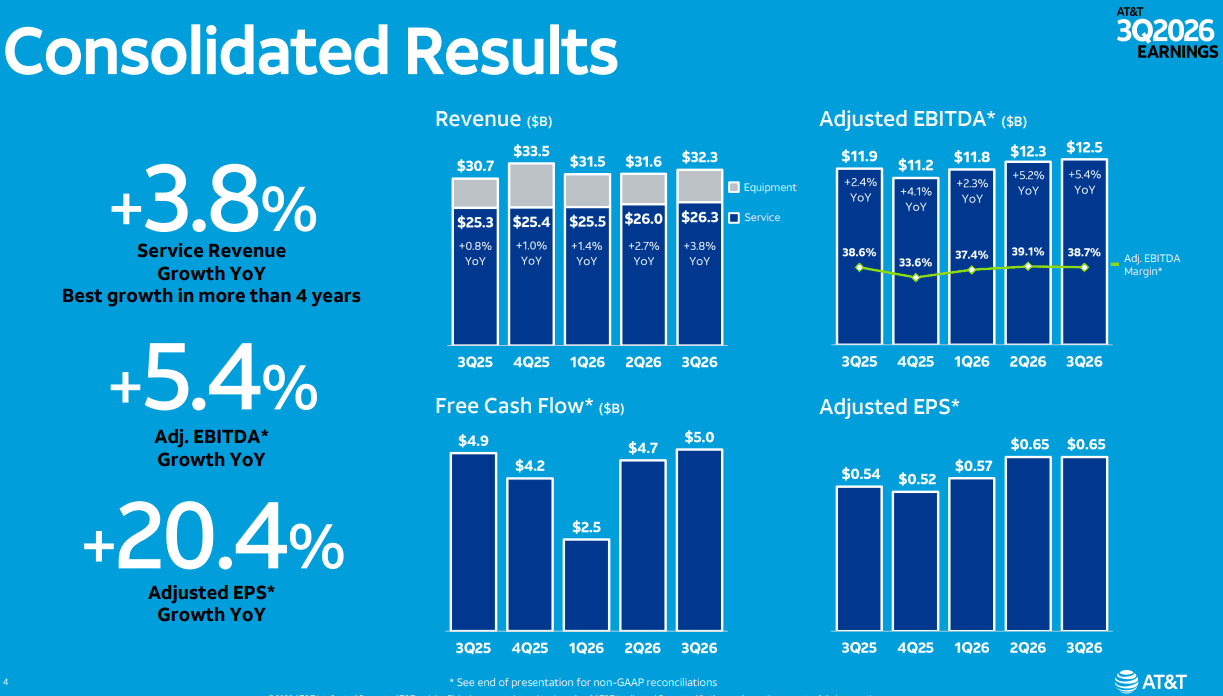
Revenue at AT&T rose 5.3% annually in the 3rd quarter 2026to $32.3 billion, beating estimates among analysts surveyed by FactSet of $31.69 billion. Adjusted earnings per share of 65 cents topped analysts’ forecasts of 60 cents a share. The company sees adjusted earnings in the $2.40 a share range for 2026, ahead of the $2.25 to $2.35 range it guided in July.
AT&T’s third-quarter results show its convergence strategy gaining scale: expanding fiber availability, adding broadband subscribers, and converting more households into customers for both home internet and mobile service. On its October 21 earnings call, the company reported approximately 350,000 additional converged customer relationships. At quarter-end, 42.8% of its advanced home internet connections also had an AT&T consumer postpaid wireless account.
AT&T recorded 1.148 million net additions across fiber, fixed wireless access (FWA), and postpaid cellular phone subscribers—the second consecutive quarter above 1 million. That total comprised 442,000 consumer and business fiber connections, 327,000 fixed wireless connections, and 379,000 postpaid phone subscriptions. These are service net additions, not necessarily distinct customers or households. AT&T added 379,000 postpaid phone subscribers in the quarter vs. 432,000 postpaid adds in the 2nd quarter.
For telecommunications engineers and network planners, the results highlight three interdependent priorities: 1.] extending the fiber footprint, 2.] improving returns through multiproduct customer relationships, and 3.] eliminating the cost of maintaining parallel legacy copper infrastructure.
Fiber Buildout Expands Reach While Deployment Efficiency Improves:
AT&T reached more than 39 million consumer and business locations with fiber at the end of the third quarter. It remains on track to exceed 40 million by year-end 2026 and 60 million by the end of 2030, while reducing its planned annual capital investment for 2027 and 2028. CFO Pascal Desroches attributed the improvement to greater efficiency in planning, construction, installation, and deployment scheduling.
“We believe this positions us to reach 60 million+ locations with fiber by the end of the decade, with annual capital investment that is roughly $1 billion lower than we previously planned.”
— Pascal Desroches, Chief Financial Officer
The revised outlook calls for annual capital investment of $22 billion to $23 billion in 2027 and 2028, compared with $23 billion to $24 billion in 2026. AT&T’s capital-investment measure includes both capital expenditures and cash payments for vendor financing; it should not be treated as synonymous with reported capital expenditures.
The footprint also requires careful interpretation. AT&T’s “locations reached” metric includes its owned-and-operated fiber network and locations available through its Fiber Ventures category, including the acquired Lumen footprint, Gigapower, and other commercial open-access providers. It measures service availability—not connected subscribers or exclusively AT&T-owned construction.
To support further expansion, AT&T announced an agreement with Global Infrastructure Partners and CPP Investments to establish a joint venture combining Gigapower with the fiber assets acquired from Lumen. It also secured a multiyear fiber-supply agreement with Corning. Together, these arrangements support deployment beyond AT&T’s traditional operating territories.
Fiber and Wireless Reinforce the Converged Customer Model:
AT&T’s commercial strategy uses home broadband as an anchor for a broader customer relationship, then adds wireless and other services. Management argues that owning and operating both fiber and mobile infrastructure provides local operating scale and greater control over service delivery and economics.
“In the dense, urban and suburban areas where we deploy both fiber and 5G infrastructure at scale, we believe that our competitors cannot and will not match our operating proficiency, network performance, or exceptional converged value proposition.”
— John Stankey, Chairman and Chief Executive Officer
The quarter provides measurable evidence of cross-selling momentum. Converged relationships increased by approximately 350,000, and management said convergence penetration in the acquired Lumen territories had risen 2.5 percentage points since the transaction closed in February. AT&T’s convergence metric includes both AT&T Fiber and Internet Air households with a qualifying postpaid wireless account; it is not a fiber-only measure.
Importantly, this is a measure of commercial convergence, not proof of a particular fixed-mobile core-network architecture. The reported indicator tracks customers taking both services. AT&T’s strategic claim is that the combined infrastructure and customer relationship improve competitiveness and lifetime value.
The economics nevertheless involve a near-term tradeoff. Fiber average revenue per user declined 4% year over year, reflecting introductory pricing, converged-account discounts, and lower-ARPU customers in the acquired Lumen markets. Management is prioritizing total account value, service-revenue growth, and margins rather than maximizing standalone broadband ARPU. Advanced Connectivity service revenue increased 6.1%, while segment EBITDA rose 7.3%.
Copper Retirement Removes the Cost of Parallel Legacy Networks:
Fiber expansion is only part of AT&T’s network transformation. The company is also migrating customers away from copper-based services so that it can retire legacy infrastructure and remove associated operating costs.
“Our progress here is picking up momentum, and we now have more than 100 wire centers with no customers supported by legacy services.”
— John Stankey, Chairman and Chief Executive Officer
That milestone does not necessarily mean those facilities have closed or that all equipment has been removed. It means no customers in those wire centers remain supported by legacy services—a prerequisite for subsequent infrastructure decommissioning and cost elimination. AT&T identifies customer migration and regulatory approvals as dependencies in removing legacy fixed costs.
Management targets discontinuation of copper-based services in 50% of wire centers outside California by the end of 2027 and substantially all of those wire centers by the end of 2029. Copper retirement is one component of the broader program targeting $4 billion in annual consolidated cost savings by the end of 2028; that figure is not a copper-only savings target.
Outlook: Monetizing Fiber Reach and High-Capacity Connectivity:
AT&T’s operating results indicate that subscriber growth and cost transformation are translating into improved segment profitability.
“We exited the third quarter with great operating momentum, and we continue to expect full-year Advanced Connectivity service revenue growth of 5%+ and EBITDA growth of 6%+.”
— Pascal Desroches, Chief Financial Officer
The next execution test is converting additional fiber availability into sustained penetration and profitable multiproduct relationships. CEO Stankey said AT&T evaluates fiber investments against a terminal penetration assumption of 40%, while pursuing higher take rates over time. He also left open the possibility of wholesale access in selected markets to improve utilization and returns.
Conclusions:
Beyond residential broadband, management sees its metropolitan fiber footprint supporting enterprise and AI-related connectivity. Stankey said more than 90% of mapped U.S. data centers are within 10 miles of AT&T fiber and more than 80% are within one mile. He identified AWS and Microsoft as customers for high-capacity connectivity supporting their expanding requirements. Proximity, however, should not be confused with an installed connection or a contracted service.
“This asset base puts us in a leading position to serve converged consumer and business customers today and well into the future, as AI becomes a key driver of their connectivity needs and requires ever-improving high-performance networking.”
— John Stankey, Chairman and Chief Executive Officer
The concrete AI-related opportunity is not simply increased household data consumption. AT&T is positioning its fiber infrastructure for business endpoints, metro aggregation, and managed multi-cloud connectivity—extending the potential revenue base beyond residential access while continuing to expand its converged fiber-and-wireless customer relationships.
“The accelerated growth we delivered this quarter shows our structural advantages to lead the next era of connectivity,” CEO Stankey said in a statement. “We are accelerating the pace of our planned share repurchases this year to approximately $10 billion, reflecting our confidence in our market position,” he added.
……………………………………………………………………………………………………………………………………………………………………
References:
https://about.att.com/story/2026/3q-earnings.html
https://markets.ft.com/data/announce/detail?dockey=600-202610210630CANADANWCANADAPR_C2239-1
AT&T Exits Mexico in $2B Deal with Televisa and Fintech Holdings
AT&T’s 600 MHz Deployment with Ericsson: Turning Low-Band Spectrum Into Coverage and Uplink Capacity
AT&T/Ericsson Demonstrate 5G-Based ISAC for Drone Detection at World Cup Stadium
Network X Americas: AT&T and Comcast reveal huge AI impact on network operations
Analysis: AT&T 1Q-2026 results: increased fiber penetration, FWA momentum, D2D deals, and mobile/home internet bundles
AT&T grows fiber revenue 19%, 261K net fiber adds and 29.5M locations passed by its fiber optic network
AT&T sets 1.6 Tbps long distance speed record on its white box based fiber optic network
Lumen launches Multi-Cloud Gateway (MCGW) and expands metro fiber network after selling consumer FTTH business to AT&T
Light Counting: optical transceiver sales surge; IEEE 802.3 and ITU-T optical transport standards explained/UEC addendum
Sales of All Types of Optical Transceivers Set New Records:
Light Counting reports that the sales of optical transceivers, shown in the first figure below, illustrates the new record set in Q2 2026 and estimates for the rest of 2026. Sales of Ethernet transceivers currently account for about 80% of the total market. Shipments of “legacy products”—800G 2xDR4 and 2xFR4, as well as 400ZR/ZR+, were up sharply in Q2, by up to 3x year-over-year in terms of units, well ahead of the market research firm’s expectations. Unit shipments of 100G and 400G Ethernet transceivers also set new records. Even 10G Ethernet was up. Volume shipments of 1.6T Ethernet transceivers and 800ZR/ZR+ are off to a great start this year, but this was less surprising.
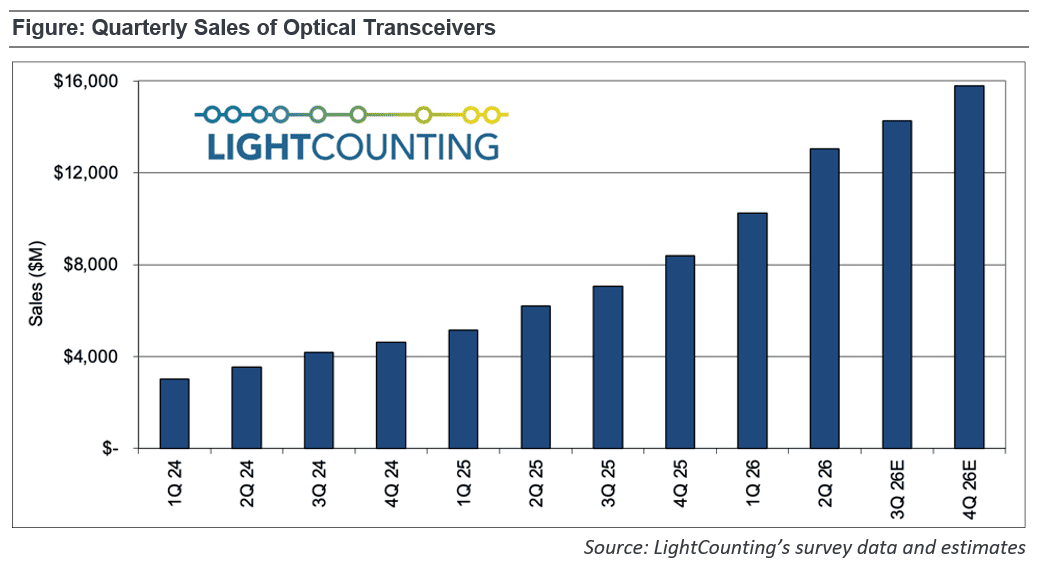
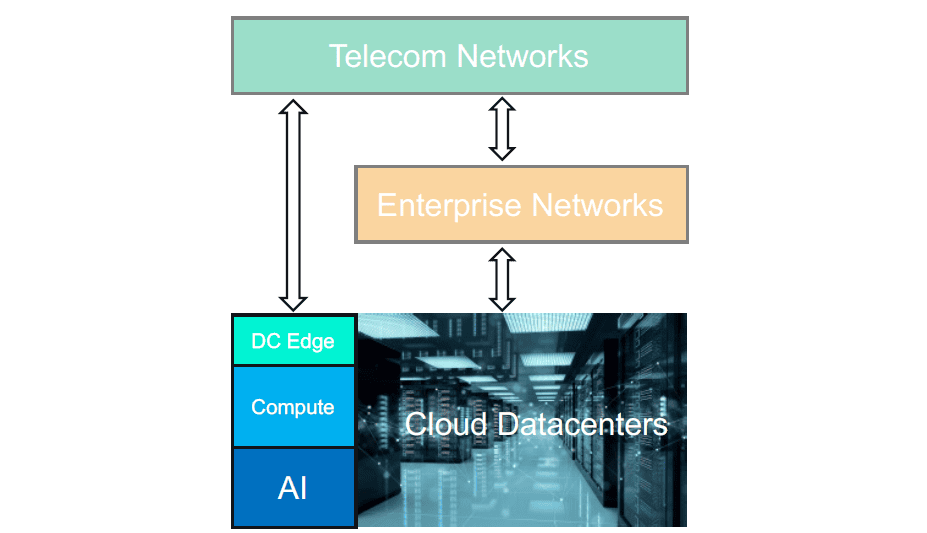
Image Credit: Light Counting
……………………………………………………………………………………………………………………………………………………………………………………………………………………………………………
Leading suppliers of optical transceivers reported record revenues and profits, despite component shortages. Here are Q2-2026 results for the top two suppliers:
- Innolight achieved a record revenue of $3.3 billion in Q2, up 192% year-over-year and up 16% sequentially. The company’s net income was $1.16 billion, up 249% year-over-year and up 40% sequentially. Gross margin increased this quarter, driven by sequential volume growth of 1.6T products.
- Eoptolink reported a record revenue of $1.8 billion in Q2, up 109% year-over-year and up 53% sequentially. The company’s net income was $698 million, up 113% year-over-year and up 74% quarter-over-quarter.
| Supplier | Estimated 2025 Sales / Segment Revenue | Market Context & Performance |
|---|---|---|
| InnoLight Technology | $5.3 Billion | Market Leader (#1); revenue surged 61% year-over-year driven by mass delivery of 800G and 1.6T modules. |
| Eoptolink | $3.5 Billion | Moved to #2 globally; registered an astonishing ~188% segment surge supplying 400G/800G optics to Amazon and Nvidia. |
| Coherent Corp. | ~$4.0 – $4.5 Billion (Data Center & Comm. Segment) | Coherent was overtaken by Eoptolink in pure transceiver rankings, but its broader communications segment generated massive revenues (including a record $1.2 Billion in Q4 2025 alone). |
| Cisco Systems | ~$1.5 – $2.0 Billion (Optical/Acacia) | Cisco captures a massive chunk of the telecom and coherent pluggable market through its internal networking sales and Acacia subsidiary. |
| Lumentum Holdings | ~$1.0 – $1.3 Billion | Reported record revenues and high double-digit growth by the end of 2025, heavily buoyed by their NeoPhotonics integration. |
| Broadcom | ~$800 Million – $1.1 Billion (Modules/Engines) | While Broadcom generates over $18B+ quarterly in overall networking/AI silicon, its specific optical transceiver and co-packaged optical engine sales represent a smaller, premium segment. |
| Accelink Technologies | ~$600 – $800 Million | Maintained a steady footprint setting new shipping records for Chinese domestic cloud providers and 5G operators. |
| Sumitomo Electric | ~$400 – $500 Million | Holds a reliable niche focused primarily on specialized telecom optical components and compact Japanese network infrastructure deployments. |
This demand is being driven primarily by AI data-center build-outs, where the scaling of accelerator clusters requires concurrent investment in compute, switching, optical interconnect, power, and cooling. Ethernet is increasingly central to scale-out fabrics and, in some architectures, to emerging scale-up designs.
The reported growth at leading suppliers illustrates how rapidly demand is propagating through the component supply chain. As note above, Innolight reported nearly 200% year-over-year growth in optical-transceiver sales during the first half of 2026. Such results are consistent with an industry that is simultaneously absorbing high volumes of 800G modules and preparing the supply chain for 1.6T transitions.
Optical Transceiver Standards:
The standards baseline spans both Ethernet and optical transport.
- For intra-data-center connectivity and some point-to-point data-center-interconnect applications, IEEE 802.3df-2024 standardized Ethernet MAC parameters for 800GbE, together with physical-layer and management specifications for 400GbE and 800GbE operation.
- IEEE P802.3dj is developing 200 Gb/s-per-lane electrical and optical interfaces for 200GbE, 400GbE, 800GbE, and 1.6TbE Ethernet operation.
- For carrier optical-transport and WDM applications, ITU-T G.709 defines the OTN digital transport hierarchy and interfaces; ITU-T G.959.1 specifies OTN physical-layer interface application codes; and ITU-T G.698.2 defines single-channel optical-interface parameters for amplified DWDM “black-link” applications.
- A carrier can transport an Ethernet PHY signal directly over a coherent wavelength. The clearest standardized example is OIF 400ZR, which carries a 400GBASE-R host signal transparently over a single coherent DWDM carrier. It is explicitly specified as a 400G BASE-R PHY interface, rather than as a full ITU-T G.709 OTUk line signal.
Optical Ethernet Standards and Product Transition:
The current optical upgrade cycle spans multiple Ethernet (IEEE 802.3) generations:
It is important to distinguish standardized Ethernet interface rates from the broader product roadmap of optical suppliers. IEEE 802.3df standardized 800 GbE, while IEEE P802.3dj addresses 1.6 TbE and the associated 200 Gb/s-per-lane physical-layer ecosystem. By contrast, 2.4T and 3.2T transceiver products may be relevant to future system architectures, but they should not be presented as ratified IEEE Ethernet rates at this stage. Please see the Addendum below for an explanation of he Ultra Ethernet Consortium.
ITU-T OTN and WDM Recommendations:
While IEEE 802.3 specifications define Ethernet MAC and PHY operation, they are not the only standards framework relevant to high-speed optical modules. In optical transport networks, ITU-T Recommendations define the digital transport structure, optical-channel parameters, WDM frequency plans, and interoperable line-side interface requirements. Optical transceivers must meet the requirements of the applicable interface standard (IEEE 802.3 or ITU-T) or implementation agreement for their intended deployment. For intra-data-center Ethernet links, this normally means IEEE 802.3 PHY specifications and applicable MSAs. For OTN, WDM, or carrier interdomain applications, the relevant requirements may additionally include ITU-T G.709, G.959.1, G.698.2, and G.694.1.
- ITU-T G.709 specifies the interfaces and digital hierarchy of the Optical Transport Network (OTN), including optical transport units and associated overhead, forward-error-correction, and multiplexing structures. An Ethernet client signal may therefore be mapped into an OTN container for transport across a metro, regional, long-haul, or subsea optical network.
- ITU-T G.959.1 specifies Optical Transport Network physical-layer interfaces, including interdomain interface requirements for single-channel and multichannel optical systems. Its application codes define parameters such as nominal bit rate, reach class, wavelength range, transmitter characteristics, receiver tolerance, and optical power budgets. The recommendation is intended to enable transverse, or multivendor, compatibility at optical interfaces crossing administrative-domain boundaries; it can also be used for intra-domain interfaces where appropriate. The current G.959.1 edition, issued in 2024 and subsequently amended, includes interfaces relevant to high-speed PAM4-based optical transport applications.
- ITU-T G.698.2 is also relevant where pluggable coherent or direct-detect modules connect into amplified DWDM systems. It specifies single-channel optical-interface parameters for amplified multichannel DWDM applications, using a “black-link” model that defines interoperability at the transmitter-side and receiver-side reference points while allowing the intervening photonic line system to remain implementation-specific. The recommendation addresses metro-oriented amplified DWDM applications and defines channel spacings based on the ITU-T G.694.1 frequency grid. Consequently, an optical transceiver used entirely within a hyperscale data-center Ethernet fabric will typically be specified primarily against IEEE 802.3 PHY requirements and relevant multi-source agreements.
In summary, a coherent pluggable used as a router-to-ROADM, router-to-transponder, or interdomain line-side interface may additionally need to comply with ITU-T OTN and DWDM interface requirements—particularly G.709, G.959.1, G.698.2, and the G.694.1 frequency-grid framework. Compliance depends on the intended application code and reference point, rather than on the module form factor alone.
Standards framing:
A concise way to explain the division of responsibility is as follows:
…………………………………………………………………………………………………………………………………………………………………………………………………………………………………………..
Cloud Capex is Through the Roof:
The magnitude of current cloud capital expenditure is exceptional and is the primary driver for the optical transport market. For example, Oracle, reported $28.5 billion in capital expenditures in its most recent quarter, up 235% year over year, against quarterly revenue of $19.3 billion, up 30%. This illustrates the extent to which an established enterprise-software supplier is being repositioned around AI infrastructure and cloud capacity. See References below for more examples of hyperscaler’s enormous capex.
Chinese hyperscalers are pursuing a similar, if less publicly transparent, investment pattern. Tencent’s capex surged 194% y-o-y in Q2, reaching $7.7 billion, up 68% sequentially. Alibaba’s capex was $9.9 billion for the quarter, up 86% year-over-year and up 156% compared to the previous quarter, used primarily to build AI compute infrastructure. Baidu’s capex for the quarter reached $1.67 billion, surging 219% year‑on‑year and 96% quarter‑on‑quarter. Alibaba and Tencent’s reported capital-expenditure percentage increases greatly exceed their revenue growth, which remained closer to the 15%–20% range. The widening gap between capital intensity and near-term revenue growth is a defining characteristic of the present AI infrastructure cycle.
Nvidia commented that it expects to see another 70% growth in capex of cloud companies for 2027—similar to the growth reported by the TOP 4 Cloud companies in 2026. Nvidia must know this well, since the company is engineering multiple financial projects to support the hyper growth.
Super-cycle, but not in a straight line:
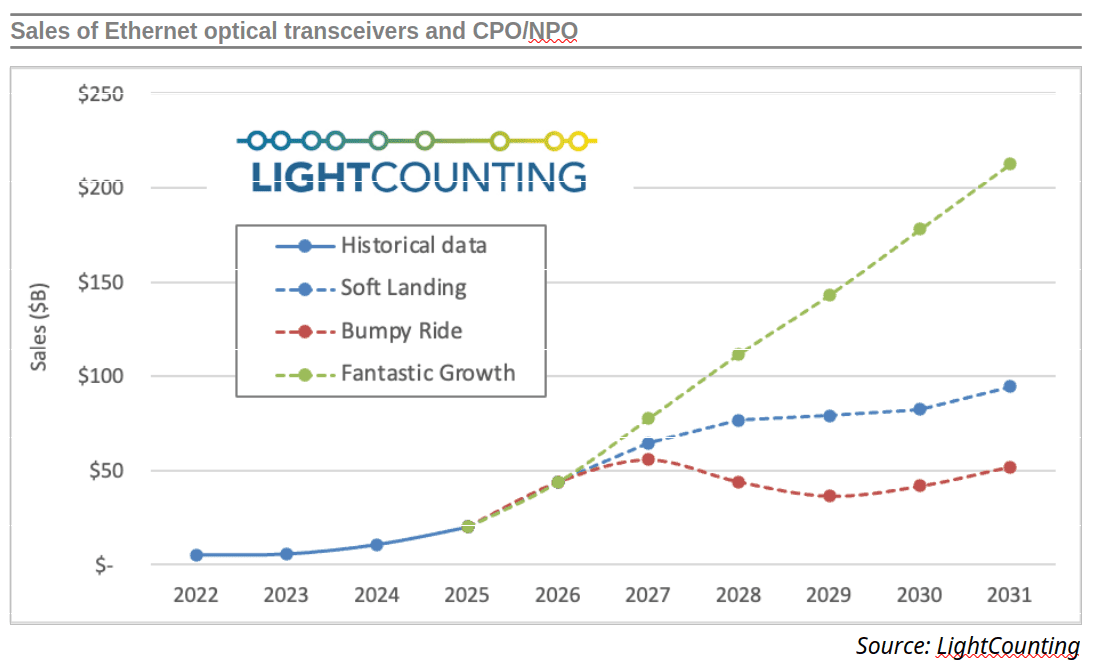
The market is clearly in an optical-interconnect supercycle. However, the present rate of expansion is unlikely to persist indefinitely. Even under a continued high-growth scenario, the forecast assumes that growth moderates from 120% in 2026 to 76% in 2027 and to approximately 20% by 2031.
The base-case forecast adopts a soft-landing assumption: cloud capital expenditure remains strong, but procurement normalizes as the supply chain expands, deployment schedules mature, and customers improve utilization of installed infrastructure. The forecast model assumes a 50% increase in cloud capital expenditure in 2027—below the roughly 70% growth contemplated by the most bullish industry forecasts.
That assumption is deliberately more conservative because optical-component supply chains historically respond aggressively to changes in customer procurement signals. Current conditions already show evidence of this effect: suppliers are expanding capacity and product portfolios rapidly in response to exceptional demand for high-speed pluggable optics.
Historical transceiver sales data from 2004 through 2025 also indicate that the sector is cyclical. Periods of two to three years of strong growth have frequently been followed by flat or declining years as inventory, manufacturing capacity, and end-market deployment plans return to balance. In that context, a soft landing is possible, but a more volatile bumpy-ride scenario—characterized by a supply-chain correction during 2027–2030—remains plausible.
Architecture matters:
The forecast also incorporates a structural counterweight to unit demand: optical-interconnect efficiency is improving. AI-cluster architectures are evolving in ways that can reduce the number of optical transceivers required per accelerator, even as total cluster bandwidth continues to rise.
Several developments are relevant:
-
TPU-based and other tightly integrated accelerator systems can reduce the optical-interconnect requirement per XPU relative to more externally networked cluster designs.
-
Multi-plane network topologies can improve path diversity and bisection bandwidth while reducing the need for redundant interconnect resources in certain deployments.
-
Higher-radix switch silicon enables flatter fabrics, reducing the number of network tiers, hop count, and associated optical interfaces.
-
The transition from 100 Gb/s-per-lane to 200 Gb/s-per-lane signaling—under development in IEEE P802.3dj—raises port density and system bandwidth, but also changes the optics-per-bandwidth relationship.
Accordingly, the relevant demand metric is not simply accelerator count. It is the interaction among accelerator architecture, scale-up versus scale-out topology, switch radix, oversubscription design, optical reach, packaging approach, and the extent to which the deployment uses pluggable optics, linear-drive optics, linear-receive optics, co-packaged optics, or near-packaged optics.
Light Counting Report Scope:
The report covers more than 100 Ethernet optical-interconnect product categories, including:
-
100G, 200G, 400G, 800G, 1.6T, 2.4T, and 3.2T retimed transceivers.
-
Linear pluggable optics and linear-drive/linear-receive optical architectures, including LPO and LRO.
-
Co-packaged optics and near-packaged optics, including CPO and NPO.
-
Products segmented by reach, interface technology, and application.
The market analysis is segmented by end customer into cloud, telecommunications, and enterprise markets. The cloud segment is further divided by customer group—top-five U.S. cloud providers, top-five Chinese cloud providers, and other cloud operators—and by application: conventional cloud and front-end networking, AI scale-out networks, and AI scale-up networks.
Conclusions:
The Ethernet optical transceiver market is benefiting from an AI-driven infrastructure build-out that is materially stronger than expected only six months ago. Yet the same intensity that creates the 2026 upside also increases the risk of a later inventory, capacity, or capital-expenditure correction. The key analytical question for 2027–2031 is no longer whether the market will grow; it is whether the industry can transition from extraordinary demand acceleration to a sustainable deployment cadence without repeating the supply-chain overshoots that have characterized prior optical-networking cycles.
Addendum – The Ultra Ethernet Consortium (UEC):
The UEC is separate from IEEE 802.3, but its work is deliberately built on—and coordinated with—the IEEE Ethernet PHY and MAC ecosystem. UEC is not an IEEE 802.3 task force and does not itself ratify IEEE 802.3 amendments. Instead, it publishes an Ethernet-based AI/HPC networking specification across multiple layers and works with relevant standards-development organizations where changes or formal standardization are needed. UEC uses and extends Ethernet, rather than that UEC defines a separate Ethernet PHY.
Division of responsibility:
How UEC relates to IEEE 802.3:
UEC’s stated premise is an Ethernet-based, open, interoperable stack for AI and HPC. Its work is designed to retain compatibility with the broad Ethernet ecosystem while optimizing behavior above—and in selected optional cases at—the PHY/link boundary. It does not replace IEEE 802.3-defined Ethernet port rates or optical PMDs.ultraethernet+1
That means:
-
IEEE 802.3df supplies the standardized 800GbE Ethernet MAC/PHY foundation.
-
IEEE P802.3dj is developing 200 Gb/s-per-lane electrical and optical interfaces for 200GbE through 1.6TbE operation.
-
UEC defines how AI/HPC systems can use such Ethernet links more effectively: particularly host-to-network interaction, RDMA-oriented transport, congestion control, traffic distribution, reliability behavior, and large-scale fabric operation.ieee802+2
UEC Specification 1.0 was released in June 2025, with Version 1.0.2 published in January 2026. UEC describes the result as a full communications stack, with scope extending from applications and transport through switching, link behavior, optics/cables integration, management, and security. UEC 1.0 is designed to operate with Ethernet-compatible physical-layer technology. It contemplates 100 Gb/s-per-lane and 200 Gb/s-per-lane signaling, which aligns naturally with the industry transitions covered by IEEE 802.3df and P802.3dj. However, UEC does define optional Ethernet PHY and link-layer features, so it is not accurate to say that it has no Layer 1 or Layer 2 relevance whatsoever.
……………………………………………………………………………………………………………………………………………………………………………………………………………..
References:
https://www.lightcounting.com/newsletter/en/september-2026-quarterly-market-update-371
https://www.lightcounting.com/report/september-2026-ethernet-optics-372
Dell’Oro: Data Center capex grew 92% in 2Q-2026 (caveats galore)
Hyperscaler capex > $600 bn in 2026 a 36% increase over 2025 while global spending on cloud infrastructure services skyrockets
Dell’Oro: 2H2026 Data Center Capex to Accelerate due to massive AI Deployments
Alphabet’s 2026 capex forecast soars; Gemini 3 AI model is a huge success
Bain & Co: AI Infrastructure Buildout Will Require $6 Trillion Revenue by 2031 to Support Massive CAPEX
Impact of optical component shortages & bottlenecks explained + Hyperscaler’s CAPEX
Hyperscaler AI Race: Soaring Capex Wipes Out Free Cash Flow; AGI and Digital Gods
How will fiber and equipment vendors meet the increased demand for fiber optics in 2026 due to AI data center buildouts?
Huawei’s Ascend Silicon Roadmap Extends From AI Chips to Cluster-Scale Infrastructure
Note: Perplexity.ai was use to research this article.
……………………………………………………………………………………..
Executive Summary:
Huawei is accelerating development of an indigenous AI-computing platform intended to reduce China’s reliance on U.S.-supplied accelerators, networking technologies, and associated software ecosystems. The effort aligns with the company’s stated strategy of becoming a full-stack supplier of AI-era computing and connectivity infrastructure—rather than primarily a developer of frontier foundation models.
Huawei said it plans to introduce two new Ascend AI accelerators in 2027: the Ascend 960DT in the first quarter and the Ascend 960PR in the third quarter. The company also disclosed a longer product roadmap extending through 2029 and said it has shipped more than 1,000 AI-computing systems to over 370 customers.
A necessary distinction is that Huawei designs its Ascend processors through HiSilicon, its semiconductor-design subsidiary, but does not own or operate leading-edge chip fabrication facilities. Production therefore depends on external foundry, memory, advanced-packaging, and equipment supply chains—areas that remain materially constrained by U.S. export controls and by the capabilities of China’s domestic semiconductor ecosystem. For example, Huawei can’t use TSMC to make its silicon so must rely on Chinese chipmakers.
As per an earlier IEEE Techblog post this week, Guo Ping, chairman of Huawei’s supervisory board, told new employees that Huawei’s objective in computing and communications is to “become Nvidia.” In technical terms, Huawei is not attempting merely to replicate a GPU. It is seeking to assemble an alternative AI-infrastructure stack: Ascend accelerators; Kunpeng general-purpose processors; servers and rack-scale systems; high-speed interconnect; storage; cloud services; and the CANN software environment that must serve, in China, some of the platform role CUDA performs globally for Nvidia.

Visitors tour Huawei’s Ascend AI exhibition booth during a conference last year. Andy Wong/
From accelerator to system architecture:
Huawei’s principal response to a per-device performance gap is system-scale integration. Rather than relying exclusively on the performance of a single accelerator generation, the company is assembling larger clusters of Ascend devices and attempting to improve the efficiency of communication, memory access, workload partitioning, and collective operations across those systems.
This is strategically relevant because training and serving large AI models are increasingly limited not only by floating-point throughput, but also by memory capacity and bandwidth, interconnect latency, bisection bandwidth, power delivery, cooling, and software efficiency. A large accelerator cluster can only approach the behavior of a unified computing resource if its networking and systems software prevent communication overhead from overwhelming the benefits of adding more processors.
Huawei has promoted UnifiedBus as an architectural approach for improving communication among processors, memory, and devices across server and rack boundaries. The underlying objective is familiar to data-center architects: reduce data-movement overhead and make a distributed accelerator cluster behave more like a coherent, programmable system. Whether Huawei can deliver this at scale will depend on achievable latency, bandwidth, congestion control, fault tolerance, topology-aware scheduling, and software maturity—not simply on the number of accelerators installed.
That systems emphasis is consistent with Huawei’s established position in telecom infrastructure. Unlike a pure-play AI-chip supplier, Huawei can combine AI computing with data-center networking, optical transport, IP infrastructure, cloud platforms, mobile networks, and edge-computing systems. The potential differentiator is therefore architectural integration, particularly for AI-RAN, autonomous network operations, edge inference, digital twins, and operator cloud deployments where AI workloads must interact with network telemetry and real-time control functions.
Interconnect and optics matter:
The company is also pursuing near-packaged optics, an approach intended to shorten electrical paths between switching or compute silicon and optical transceivers. In principle, placing optical components close to high-speed silicon can reduce electrical-channel loss and potentially improve energy efficiency as link speeds and port densities rise.
Huawei’s terminology should not be conflated automatically with co-packaged optics. Co-packaged optics generally integrates optical engines and switch or compute ASICs in a common package or closely coupled assembly; near-packaged approaches may retain more physical separation while still reducing copper reach. The key engineering question is not the label, but the extent to which the architecture can deliver lower power per transmitted bit, higher density, manufacturability, serviceability, and operational reliability at scale.
For large AI clusters, the interconnect fabric is increasingly a first-order design constraint. As clusters expand, network performance determines how effectively distributed training workloads can scale. The challenge is particularly acute where a vendor seeks to compensate for lower accelerator performance by deploying more devices: more devices can increase aggregate compute capacity, but they also increase synchronization traffic, power consumption, cabling complexity, failure exposure, and the burden on cluster-management software.
Constraints remain substantial:
Huawei’s roadmap should be assessed as a bid to establish a credible domestic alternative AI platform, not as evidence that it has achieved parity with Nvidia’s highest-end systems. Its Ascend roadmap faces several interdependent constraints:
-
Advanced fabrication remains dependent on external foundry capacity and equipment availability, even though HiSilicon can design sophisticated processors.
-
High-bandwidth memory availability, yield, packaging capability, and supply-chain scale can materially affect system output and performance.
-
Cluster-level competitiveness depends on interconnect bandwidth, latency, memory architecture, power efficiency, and the ability to operate reliably at very large scale.
-
CANN must attract developers, framework integrations, tools, libraries, and application vendors in an ecosystem where CUDA remains deeply embedded.
-
Customer adoption will depend on total cost of ownership, application portability, model performance, support quality, and availability of hardware at predictable volumes.
The strategic rationale is nonetheless clear. Export controls have increased the value of a domestically supplied AI-computing stack, even if individual components or systems lag the frontier in some metrics. As Huawei rotating chairman Eric Xu put it, the company’s concern is not only whether it can access the most advanced technology, but whether it can avoid strategic dependence on supply decisions made elsewhere.
For telecom operators, the central issue is whether Huawei can turn this silicon-and-systems program into deployable AI infrastructure for network operations. A credible offering would require more than Ascend processors. It would require validated reference architectures for AI-RAN and telco cloud, high-performance east-west networking, operational automation, observability, model lifecycle management, security controls, and a software ecosystem that can support carrier-grade availability.
Huawei’s advantage is that it already participates across many of those domains. Its challenge is proving that the integrated stack can deliver competitive performance, efficiency, ecosystem breadth, and supply assurance under sustained technology restrictions. That is the practical test of its ambition to become China’s Nvidia-equivalent in AI infrastructure.
……………………………………………………………………………………………………………………………………………………………..
References:
https://www.wsj.com/tech/ai/huaweis-plan-to-become-chinas-nvidia-8af8d8a1 [paywall]
https://www.wsj.com/tech/chinas-huawei-develops-new-ai-chip-seeking-to-match-nvidia-8166f606 [paywall]
Huawei Chairman: Strategic Focus on AI Computing & Connectivity Infrastructure
Huawei unveils AI Centric Network roadmap, U6 GHz products, 5G Advanced strategy and SuperPoD cluster computing platforms
Key take-aways: “16th Smart City and Intelligent Economy Expo” for Huawei, Alibaba & China’s three state backed carriers
Omdia’s 2025 Mobile Core Network Leaders: Huawei #1 in market share; Nokia #1 for portfolio competitiveness
Analysis: Huawei”s upgraded Xinghe Intelligent Network Solution for South Africa
Huawei’s AI-Centric Network Vision: Six Imperatives for the Next Decade; Critical Questions for IEEE Techblog Community
Huawei FY2025: 2.2% YoY revenue increase; strategic pivot to AI and intelligent automotive solutions
Huawei, Qualcomm, Samsung, and Ericsson Leading Patent Race in $15 Billion 5G Licensing Market
Huawei Cloud Review and Global Sales Partner Policies for 2026
Huawei’s Electric Vehicle Charging Technology & Top 10 Charging Trends
Huawei to Double Output of Ascend AI chips in 2026; OpenAI orders HBM chips from SK Hynix & Samsung for Stargate UAE project
4.8 GHz to 4.9 GHz frequency band uses & Verizon Wireless experimental license for testing ISAC with Ericsson
Introduction:
The 4.8 GHz to 4.9 GHz frequency band is a critical slice of mid-band spectrum located within the larger IEEE C-band (4.0 to 8.0 GHz) and the ITU Ultra High Frequency (UHF)/Super High Frequency (SHF) boundary. It is currently used primarily for public safety operations (especially the 4.9 GHz portion allocated to FirstNet for drone control and crisis response) and select 5G deployments (part of 3GPP 5G NR Sub-6 GHz Band n79 in parts of Asia). It is extensively deployed for commercial 5G networks across Asia (such as China and Japan) and Europe, while in the United States, it is being studied for repurposing and testing advanced 5G/6G integrated sensing and communication (ISAC). Finally, it is actively being studied for future 5G-Advanced and 6G mobile broadband and sensing use cases.
Executive Summary:
| Region / Country | 5G Spectrum Range | Mid-Band Status |
|---|---|---|
| China | 4.8 GHz – 4.9 GHz (and 3.3–3.6 GHz) | Actively deployed for 5G NR Band n79 |
| Japan | 3.6–4.1 GHz & 4.5–4.9 GHz | Allocated to major carriers (e.g., NTT Docomo) |
| United States | 4.4 GHz – 4.94 GHz | Historically Federal/Military; currently under review for commercial 5G/6G |
- Favorable Propagation: It provides a strong balance between coverage area and high data throughput (bandwidth). [1]
- Capacity: This frequency handles heavy data loads—like high-definition real-time video streaming—much better than lower bands (like 700 MHz). [1]
- Indoor Penetration: It experiences higher atmospheric and structural attenuation compared to 2.4 GHz or 3.5 GHz, meaning it requires denser small-cell deployments for deep indoor coverage
Verizon’s Experimental License for the 4.8GHz-4.9GHz Band:
Verizon Wireless (under the company name Cellco Partnership) has applied to the FCC for an experimental license to use the 4.8GHz-4.9GHz band in and around its lab in Los Angeles, California. Verizon Wireless’s request is temporary, expiring one year from grant. The application is pending approval, but the license is expected to be granted soon, according to Steve Crowley.
Verizon said, “this experimental authorization is necessary to test Ericsson software and hardware in a noncommercial environment. Verizon Wireless requests this authorization to demonstrate 5G advanced technology use cases such as object sensing as a precursor to 6G Integrated Sensing and Communication (ISAC). This work will facilitate the adoption of use cases across commercial, public safety, and defense sectors.”
Grant of the experimental authorization will allow Verizon Wireless to set up hardware radiating in 4.8-4.9 GHz as part of a private network not connected to commercial operators. The radios are certified for use under 47 C.F.R. Part 27 and Part 96. The testing will be conducted using varying bandwidths to allow for range, resolution, and confidence assessments. Testing will occur outdoors and all transmissions will be controlled at the locations provided in the application. The fixed base stations will employ directional antennas and will have a maximum antenna elevation as described in the application. The base station antenna has a half-power beam width of approximately 24º vertically and 65º horizontally.
Verizon Wireless is unable to determine the incumbent users in the 4.8-4.9 GHz band. Verizon Wireless will coordinate with the incumbents once the FCC and NTIA have provided the agencies impacted, and prior to commencing testing, to avoid any potential disruptions to their operations. If incumbent licensees experience interference, Verizon Wireless will cease interfering operations.
Verizon is one of the first companies to apply for a test license in 4.4GHz specifically for 6G-related trials, according to Crowley. He noted it is also first time the carrier has requested a test license in any of the frequencies under study, which include 1.6GHz, 2.7GHz, 4.4GHz and 7GHz.
Other Entities Pursuing the 4GHz Band:
Samsung Research America requested an experimental license this month to use 4720MHz-4820MHz in Plano, Texas, but its application did not specify use cases to be tested.
The 4.8GHz-4.9GHz spectrum falls within the so-called 4.4GHz band (4400MHz-4940MHz) that the NTIA has identified for study to repurpose for commercial licensed use as part of the U.S. plan to make more frequencies available for 5G and 6G.
The CTIA refers to the band as 4GHz, rather than 4.4GHz. The group published a report this week to make an economic and technical case for the “prime midband spectrum” and urged policymakers to move quickly on studies this fall. They described 4GHz as the “a cornerstone” of the US spectrum pipeline, along with upper C-band, 2.7GHz and 7GHz, because it offers potential 400MHz of bandwidth and already has some equipment and device support. Further, it is a “compelling alternative” to China’s push for licensed use of the 6GHz band in spectrum negotiations at ITU World Radiocommunication Conference 2027 (ITU WRC-27).
Will It Be Used for 6G?
- International Consideration: The ITU-R and organizations like Nokia are studying the 4.4–4.8 GHz and neighboring ranges as potential mid-band spectrum for future IMT-2030 (6G) services. There are several ongoing compatibility studies in ITU-R WP 5d between terrestrial, maritime and satellite use of this band. They are in preparation for ITU WRC-27 which will specify IMT 2030 (6G) frequencies.
- Industry Support: Industry groups like the CTIA advocate for the broader 4 GHz mid-band range as a prime, lower-risk spectrum for wide-area mobile capacity to bridge 5G-Advanced and early 6G rollouts.
- Global Hurdles: Formal decisions regarding international mobile allocation for this band will be evaluated globally at the ITU-R World Radiocommunication Conference (WRC-27), though support varies by region due to existing incumbent and defense users.
-
Verizon added nine new members to its 6G Innovation Forum this week and signaled intent to test more use cases in the areas of ISAC, digital twins, robotics, AI and wearables. The new members are Amazon Web Services (AWS), Cisco, Intel, Keysight Technologies, MediaTek, Nvidia, Palo Alto Networks, Rohde & Schwarz and Viavi Solutions. They join founding members Ericsson, Samsung, Nokia, Meta and Qualcomm Technologies.
References:
https://x.com/StevenJCrowley/status/2097450891444142433
https://apps.fcc.gov/els/GetAtt.html?id=412698&x=
https://www.lightreading.com/6g/verizon-seeks-fcc-approval-to-test-6g-use-cases-in-4ghz
https://urgentcomm.com/network-tech/an-introduction-to-4-9-ghz
ETSI Integrated Sensing and Communications ISG targets 6G
Key take-aways: “16th Smart City and Intelligent Economy Expo” for Huawei, Alibaba & China’s three state backed carriers
Analysis: Cohere’s $28M U.S. DoD FutureG ISAC contract; OTFS vs OFDM; 6G-NR/IMT 2030 RIT standards outlook
3GPP approves timelines for Release 21 which will specify 6G RAN, Core and 5G Advanced
After Bell Labs: Telecom Industry Funds Only a Fraction of the Innovation Needed
Many telecom analysts have noted former Bell Labs CTO and President Marcus Weldon scathing linkedin post, sharply criticizing deep staff cuts and warnings of “erasure” at the iconic research division. Weldon said he believes Bell Labs staffing has been cut to nearly half of the 1,200 strong workforce that was in place during his tenure (2013-to-2021). While he acknowledged that restructuring could account for some of those changes, he argued a 50% reduction in force in five years “is both shocking and unprecedented.”
An unidentified Nokia spokesperson told Fierce that Bell Labs “remains a deeply important part of Nokia, with a long track record of turning world-class research into technologies that deliver commercial impact and move our industry forward.” However, the company acknowledged that the hundred-year-old Bell Labs is “entering a new chapter.”
It’s important to recognize that Bell Labs is not the only big research house that’s disappeared. There’s also Bellcore/Telcordia, Nortel Networks R&D (Bay Street Labs), Xerox PARC, HP Labs, Telco labs (e.g. Pac Bell/SBC, Ameritech, Bell South, Bell Northern Research, GTE Labs, Sprint Labs, and many more).
Meanwhile, telecom analyst Sebastian Barros states “the $1.3 trillion telecom industry is funding only a fraction of the innovation it will need for whatever comes after 6G.” It appears to us that the industry’s economic model is badly failing to fund future innovation needed for growth.
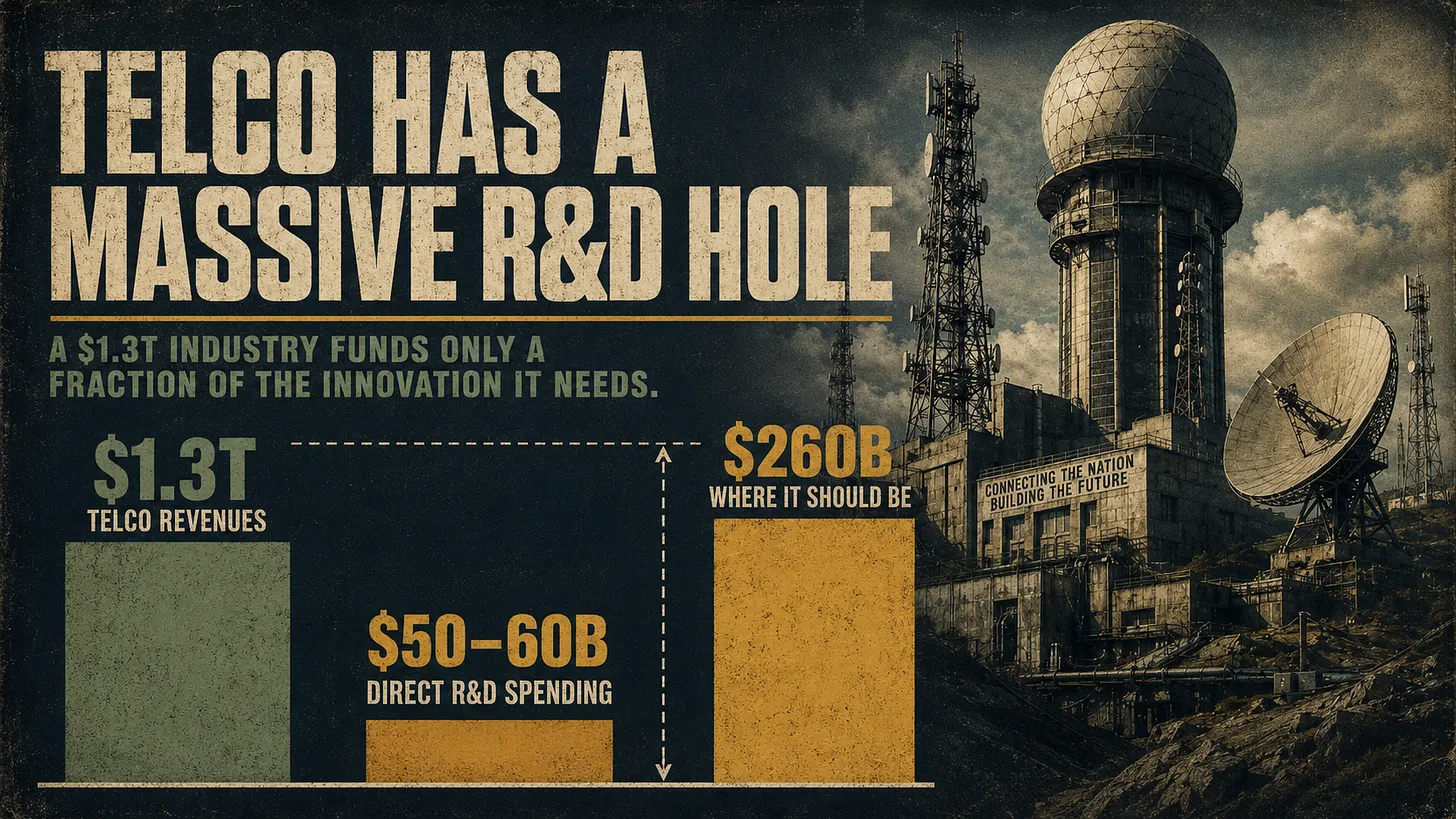
Image Credit: Sebastian Barros
………………………………………………………………………………………………………………………………………………………………………………………………
Our Analysis:
The core problem — R&D was outsourced and never replaced. After the 1984 Bell System breakup and liberalization in Europe and Asia, operators pivoted to customers, spectrum, deployment, and operations, while Ericsson, Nokia, Huawei, Qualcomm, ZTE, Samsung, and a long tail of suppliers took over most technology development. Operators became buyers of innovation rather than creators of it.
The Bell Labs model that produced the transistor, information theory, Unix, and modern AI is gone. That institution ran on an economic engine that no longer exists: in 1974 AT&T booked about 1.4% of US GDP, with Bell Labs alone spending roughly 2% of revenue on nonmilitary R&D — over four cents of every AT&T dollar. That stable, massive funding let researchers pursue problems that wouldn’t become products for fifteen years. Expecting a vendor like Nokia (€19.9B annual sales) to recreate that under today’s competitive economics ignores the financial logic of modern telecom. The contraction is visible: Marcus Weldon estimates Bell Labs research staff has fallen from over 1,200 to roughly 600 since he left the labs.
The industry is capex-heavy but R&D-light. Telecom invests more in capital expenditures than almost any other sector — over $350 billion per year — yet only the top 10 technology providers collectively spend around $50 billion annually on R&D. The capex money flows into deploying networks, not inventing or researching new technologies.
–>Yet in 2025, Huawei invested $27.5 billion in R&D. That was ~22% of its total revenue for that year.
The next cycle looks even more disciplined. Analysts expect 6G RAN capex to ramp only toward the end of the decade, with cumulative 6G RAN revenue in the first six years projected 10–20% lower than the comparable 5G period. Nearly 400 organizations are investing in 6G R&D, but venture-backed startups barely participate in a material way, leaving innovation concentrated among incumbents.
The takeaway: a $1.3 trillion industry funds only a fraction of the innovation it needs because its institutional R&D engine was dismantled decades ago and never rebuilt — operators spend on capex, vendors own the R&D, and the pipeline of disruptive new entrants is thin. That’s why “whatever comes after 6G” may arrive with far less foundational research behind it than the generations that preceded it.
Telecom Capex vs. AI Hyperscaler Capex:
The headline shift is quite stark. In 2026, the AI hyperscalers alone are on track to outspend the entire global telecom industry on capital investment — roughly doubling their own 2025 figures while telecom capex flattens or edges down. Here are the numbers side by side:
-
Hyperscalers are sprinting. Amazon alone plans ~$200B in 2026 capex (up from ~$125–132B), Alphabet $175–185B, Meta $115–135B, Microsoft $110–120B, and Oracle ~$50B. The vast majority goes to AI compute, data centers, and networking.
-
Telecom is grinding. Analysts see global operator capex edging down slightly by 2026, with spending holding near 20% of sales as fiber completion and 5G Standalone upgrades wind down. US telco capex was $80.5B in 2024.
-
Capital intensity is extreme. 2026 hyperscaler capex runs at roughly 86% of revenue for Oracle, 54% for Meta, and 46–47% for Microsoft and Alphabet.
Why this matters for the Barros argument: This is the flip side of the underinvestment thesis. Hyperscalers are channeling unprecedented capital into AI infrastructure — funded increasingly by debt, with incremental borrowing as a share of hyperscaler capex rising from ~9% in FY-2024 to ~32% by mid-2026 — while telecom operators, the sector that historically built the networks, are cutting back. The investment gravity has shifted from connectivity infrastructure to AI models andcompute, which is exactly why a $1.3 trillion industry funds only a fraction of the innovation it will need after 6G.
References:
https://sebastianbarros.substack.com/p/telecom-is-massively-underinvesting
https://www.fierce-network.com/wireless/nokia-defends-bell-labs-future-after-ex-chief-blasts-cuts
Dell’Oro: 6G RAN Capex to reach $500 billion by 2034 + Counterpoint
Dell’Oro: 2H2026 Data Center Capex to Accelerate due to massive AI Deployments
Hyperscaler AI Race: Soaring Capex Wipes Out Free Cash Flow; AGI and Digital Gods
China’s state owned telcos slash CAPEX to the lowest in decades!
Dell’Oro: Global telecom CAPEX declined 10% YoY in 1st half of 2024
Nvidia CEO Huang: AI is the largest infrastructure buildout in human history; AI Data Center CAPEX will generate new revenue streams for operators
Ericsson and MediaTek Demonstrate 3GPP-Based GNSS RTK Positioning with Sub-30cm Accuracy Over a Commercial 5G Network
Ericsson and MediaTek have completed a world-first end-to-end demonstration of high-precision outdoor positioning over a commercial 5G network, using standardized 3GPP Global Navigation Satellite Systems (GNSS) Real-Time Kinematic (RTK) assistance. The trial achieved stable outdoor positioning accuracy below 30 cm using a handset’s integrated antenna, demonstrating a scalable path to decimeter-level positioning without proprietary positioning infrastructure or dedicated external GNSS hardware.
The demonstration validates how 5G networks can distribute GNSS RTK correction information efficiently to devices for industrial automation, autonomous mobility, drones, robotics, and other applications requiring reliable, mission-critical location awareness.
Image courtesy of Ericsson
………………………………………………………………………………………………………………………………………………………………………………………………………………………
Technical highlights:
-
Sub-30 cm positioning performance: The device achieved stable outdoor accuracy below 30 cm with its built-in antenna. With a geodetic-grade GNSS antenna, the same RTK approach can support centimeter-class positioning performance.
-
3GPP-standardized architecture: The solution uses capabilities specified in 3GPP Release 16 for GNSS positioning assistance, enabling an interoperable architecture across compatible networks, positioning servers, chipsets, and devices.
-
End-to-end unicast and broadcast validation: Both delivery modes were demonstrated end to end:
-
Unicast GNSS RTK: LPP assistance messages are delivered through Secure User Plane Location (SUPL) over standard IP connectivity, enabling targeted delivery to individual UEs.
-
Broadcast GNSS RTK: RTK assistance data is transmitted through Positioning System Information Blocks (PosSIBs), allowing common assistance information to be delivered simultaneously to all capable devices within a cell.
-
-
Efficient scaling model: Broadcast delivery can reduce repeated transmission of identical RTK correction data in high-density areas, while unicast can be used for lower-traffic scenarios, individualized service handling, or LTE-connected devices. This supports flexible selection of the most efficient assistance-delivery method based on coverage, device population, and radio-resource conditions.
-
Secured broadcast operation: While broadcast information is radio-accessible to devices in the coverage area, 3GPP mechanisms support encrypted positioning assistance. Authorized subscribers obtain the required decryption material through the 5G Core, including the Access and Mobility Management Function (AMF), protecting access to premium high-precision positioning services.
GNSS correction support:
The trial supports two standardized GNSS correction-data models:
-
Observation State Representation (OSR): Provides corrections derived for a specific receiver or location context, including GNSS observation-related corrections.
-
State Space Representation (SSR): Delivers correction parameters associated with GNSS satellite orbit, clock, bias, and atmospheric error states. SSR is particularly suitable for scalable service delivery because the common state information can be applied by many devices across a service area.
In both cases, the UE applies the received RTK assistance in real time to mitigate satellite, orbital, clock, ionospheric, tropospheric, and other GNSS error sources that limit conventional standalone GNSS accuracy.
Network and device implementation:
The test used Ericsson’s 5G Core, Ericsson Network Location (ENL), Ericsson 5G Advanced Location Services, and Ericsson RAN to generate, manage, and distribute OSR and SSR correction information through the mobile network. MediaTek validated the device side using its latest 5G modem technology with integrated GNSS capability, including real-time processing of advanced GNSS correction data with power-optimized implementation.
“This is a milestone for the 5G ecosystem,” said Johan Hultell, Head of Product RAN Software at Ericsson. “Together with MediaTek, we make high-precision location more accessible to device makers and enterprises, accelerating use in manufacturing, transport and beyond.”
Dr. HC Hwang, General Manager of Wireless Communication Systems and Partnerships at MediaTek, added: “The collaboration with Ericsson demonstrates how 5G Advanced technology can unlock new value for consumers and enterprises alike. Our modems with integrated GNSS are ready to support these advanced positioning services, paving the way for the next generation of intelligent devices.”
Technology backgrounder:
Conventional standalone GNSS typically provides positioning accuracy in the range of several meters. RTK improves this performance by using measurements from accurately surveyed reference stations to generate correction assistance. In the 3GPP architecture, this assistance is delivered through the cellular network using LPP-based positioning procedures and, where applicable, broadcast system information.
By standardizing the delivery of GNSS RTK assistance over 4G and 5G networks, operators can offer high-precision location capabilities at network scale. This creates a standards-based foundation for digitalized industrial operations, autonomous systems, intelligent transportation, asset tracking, and spatially aware consumer devices.
Accuracy to within tens of centimeters is a significant improvement compared to traditional GNSS, which is accurate to within several meters, and therefore paves the way for more advanced use cases. These include the safe operation of autonomous vehicles, drones and industrial robots in complex outdoor environments, Ericsson said. Complex environments encompasses places like factories, logistics hubs, ports, and mines etc.
…………………………………………………………………………………………………………………………………………………………………………………………………………………………………………
References:
https://www.ericsson.com/en/news/2026/8/ericsson-and-mediatek-raise-the-bar-for-location-accuracy
https://www.telecoms.com/5g-6g/ericsson-and-mediatek-put-precise-5g-positioning-through-its-paces
MediaTek overtakes Qualcomm in 5G smartphone chip market
MediaTek will use TSMC to make its Dimensity SoC’s in 2024
AT&T’s 600 MHz Deployment with Ericsson: Turning Low-Band Spectrum Into Coverage and Uplink Capacity
AT&T/Ericsson Demonstrate 5G-Based ISAC for Drone Detection at World Cup Stadium
Ericsson leads SK Telecom AI RAN vs. NVIDIA’s GPU centric AI RAN Alliance
AI-RAN and Agentic AI get real: Ericsson, Nokia, Verizon & other operators enter into a new network automation era
Analysis: Ericsson’s leading role in French INTENTION 6G project
Telefónica incorporates AI for businesses voice communications vs. 3GPP/ITU specifications
Executive Summary:
Telefónica España made an announcement this week which indicates that Voice could be an important AI monetization opportunity for telcos. The Spain based telecom group is positioning its business voice portfolio around a key differentiator: the ability to embed AI-enabled capabilities directly into conventional fixed and mobile telephony, without requiring enterprises to migrate users or workflows to a separate communications platform. It is incorporating generative AI features into its network for things like call transcription and summarization, which it says is will transform “every voice conversation into usable, structured and actionable information,” as week as virtual assistants on fixed-line and mobile.
Targeted at large enterprises, public-sector organizations, and mid-sized businesses, the enhanced portfolio is intended to shorten call-response times, increase the proportion of calls handled, and convert voice interactions into structured, actionable business information. Telefónica reports that the AI-enabled tools can reduce time spent managing calls by an average of 60%, enabling organizations to handle a higher volume of customer interactions.
Telefónica has integrated artificial intelligence across its business voice offerings—from basic mobile services to advanced PBX and cloud-based telephony platforms—as part of its evolution toward intelligent voice communications. The proposal incorporates generative-AI functions within the Telefónica network, including call transcription, automated summarization, and virtual-agent capabilities. These functions are designed to preserve information that might otherwise remain unstructured within voice conversations, while helping organizations reduce missed opportunities and improve operational responsiveness.
Javier Pascual, Director of Product, Pre-sales and Provisioning at Telefónica Spain, said:
“We are the only operator that offers intelligent transcription and summarization of calls over fixed and mobile voice, making us the best way for companies to access digital technologies. This pioneering solution, which integrates generative AI into standard telephony, allows our clients to summarize and transcribe calls, as well as integrate 100% of virtual agents using natural language, thus improving productivity and agility.”
Cross-Portfolio Intelligent Voice:
Telefónica’s approach spans enterprise, public-administration, corporate-mobile, and mid-market customer segments. It applies to traditional and cloud-based voice solutions, including:
-
Centrex IP, Telefónica’s converged fixed-mobile business voice platform.
-
Centrex 365, a Microsoft-based cloud voice offering integrated with collaboration tools.
-
Enterprise mobile voice services.
A core capability is AI-based transcription and summarization of calls. By transforming voice conversations into searchable and structured records, the feature can support knowledge capture, customer-service follow-up, compliance-related documentation, and analytics workflows.
The company is also introducing Centrex AI, a virtual-agent capability based on advanced language models. Centrex AI is designed to support next-generation generative-AI interactions across channels beyond voice and to integrate with customer business applications. The virtual agents are intended to interpret natural-language requests in context, automate repetitive interactions, and provide faster, more consistent responses.
Telefónica states that the platform supports more than 100 languages and can operate continuously, enabling 24/7 multilingual customer engagement.
Operational and Vertical Use Cases:
Telefónica reports that the AI-enabled capabilities can improve agent efficiency by as much as 60% by reducing time devoted to repetitive tasks. The company also cites potential increases of more than 10% in the number of interactions managed, reflecting improved call-handling capacity.
Initial use cases focus on healthcare, public administration, retail, and industrial enterprises:
-
In healthcare, a WhatsApp-based AI agent can schedule appointments, provide immediate confirmations, and support multilingual exchanges.
-
For municipal governments, voice agents can address common citizen queries in multiple languages and route calls to the appropriate department.
-
For automotive dealerships, virtual agents can help manage service appointments and customer inquiries related to vehicle sales.
By integrating generative AI functions into the existing voice network and service portfolio, Telefónica is seeking to extend intelligent automation to established telephony environments rather than treating AI communications as a standalone application layer.
…………………………………………………………………………………………………………………………………….
Editorial Analysis:
Telefónica’s offer as an operator-integrated, proprietary AI overlay on existing fixed/mobile and cloud voice services, rather than as a service defined by 3GPP or ITU. The business voice offering builds on standardized fixed/mobile voice and cloud-telephony foundations, while its generative-AI functions—call transcription, summarization, and virtual-agent integration—appear to be operator- and vendor-implemented capabilities. Current 3GPP work provides enabling mechanisms for AI/ML in 5G systems, whereas ITU-R’s AI-related IMT work addresses radio-network evolution rather than AI-enhanced enterprise telephony.3GPP.
Relevant 3GPP specifications:
3GPP’s AI/ML work is primarily focused on network and RAN optimization, AI/ML model transfer and lifecycle management, data collection, and interoperability. Notably, 3GPP has stated that it does not plan to standardize the AI/ML models themselves; it instead standardizes the supporting mechanisms and controls.3gpp
ITU-R versus ITU-T:
ITU-R: There are no ITU-R Recommendations specifically governing AI-based telephony, generative-AI call summarization, or virtual agents. This is consistent with ITU-R’s mission: spectrum, radio propagation, and IMT radio-interface frameworks. Its IMT-2030/6G work includes integrated AI and communication as a broad capability area, but that concerns wireless-system capabilities such as distributed training and inference—not enterprise voice-service features.
ITU-T: This is the more relevant ITU sector for AI telephony and conversational AI, although its work is still largely horizontal rather than specific to IMS/PSTN calling:
-
ITU-T F.748.46 (2025) specifies requirements and evaluation methods for AI agents based on large-scale pre-trained models. Its scope includes recognition, comprehension, dialogue, generation, and reasoning—capabilities directly relevant to virtual voice agents.
-
ITU-T E.AIQ, Framework for quality evaluation of conversational AI systems, is under study in Study Group 12. It proposes KPIs and an “AI Quotient” approach for assessing AI systems in relation to QoS and QoE.itu
-
ITU-T Y.3178 defines a functional framework for AI-based network-service provisioning in future networks.itu
-
ITU-T Y.3661 (2025) specifies an architecture and mechanisms for customer-oriented intelligent network operation, including AI-supported recognition of user intent; this is adjacent to, but not a telephony-service specification
References:
Telefónica incorpora la IA a todas sus comunicaciones de voz para empresas
https://www.telecoms.com/ai/telef-nica-upgrades-business-voice-services-with-integrated-ai
Vodafone Spain (Zegona), MasOrange and Telefonica in possible RANco joint venture
Telefónica and Nokia partner to boost use of 5G SA network APIs
Ericsson and O2 Telefónica demo Europe’s 1st Cloud RAN 5G mmWave FWA use case
Telefónica launches 5G SA in >700 towns and cities in Spain
Telefónica and Nokia partner to boost use of 5G SA network APIs
Enable-6G: Yet another 6G R&D effort spearheaded by Telefónica de España
Dell’Oro: Enterprise PON Deployments expected to increase 844% year-over-year
According to a new Dell’Oro Group report, “PON in the Data Center and Premise Advanced Research Report“ recently published, total 2026 Data Center PON equipment revenues are expected to increase 844% year-over-year (Y/Y), driven by hyperscalers looking to use the point-to-multipoint technologies to reduce the cabling and power consumption requirements of their out-of-band management networks.
“PON technologies are increasingly moving from traditional residential networks to enterprise and data center applications, providing additional growth opportunities for PON equipment providers,” said Jeff Heynen, Vice President of Broadband Access and Home Networking market research at Dell’Oro Group. “We see hyperscalers and enterprises, both large and small, increasingly deploying PON technologies for passive fiber distribution that is lower cost and that maintains its value far longer than traditional copper infrastructure,” added Heynen.
Additional highlights from the PON in the Data Center and Premise Advanced Research Report:
- Total cumulative spending on data center PON equipment from 2026 to 2030 is expected to exceed $3 billion, as hyperscalers, neocloud providers, and colocation providers all deploy PON for their out-of-band and infrastructure management networks.
- Enterprises are increasingly deploying Passive Optical LAN (POL) as the long-term benefits of increased speeds and lower operational costs outweigh the costs of deploying fiber in the building.
- Chinese operators continue to deploy tens of millions of master and subtended ONTs to deliver fiber-to-the-room (FTTR) services to their residential broadband customers.
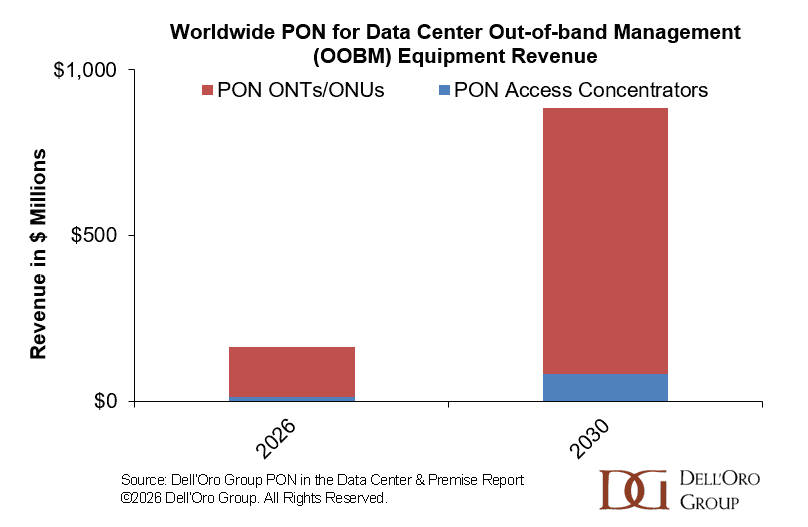
………………………………………………………………………………………………………………………………………………………………………………
Editorial Analysis:
This extremely bullish forecast points to a potentially important new use case for PON: not as a replacement for the high-bandwidth, low-latency Ethernet fabric that interconnects servers and storage, but as an economical physical layer for the separate networks used to monitor, provision, and recover data-center infrastructure. In that role, a passive optical distribution architecture can consolidate fiber runs and avoid electrically powered aggregation equipment in parts of the management network, potentially simplifying expansion and reducing operational overhead.
Dell’Oro’s projected 844% year-over-year revenue increase should be read in the context of an early-stage market: the percentage reflects rapid adoption from a comparatively small base rather than an indication that PON will displace mainstream data-center switching. Nevertheless, the report’s forecast of more than $3 billion in cumulative 2026–2030 spending indicates that hyperscale, neocloud, and colocation operators are sufficiently interested to make data-center PON a material adjacent market for OLT, ONT, and ONU suppliers.
The enterprise opportunity is somewhat different. Passive Optical LAN can extend fiber deeper into commercial buildings, with optical terminals serving end-user areas rather than relying entirely on copper horizontal cabling and access switches. The principal trade-off is front-loaded installation complexity—especially where fiber pathways must be added or upgraded—against the prospect of longer infrastructure life, higher available access speeds, and lower energy use over the building lifecycle. Dell’Oro also includes enterprise/MDU POL and business FTTR applications in its five-year forecast coverage, suggesting that it views these segments as part of the same widening PON equipment ecosystem.
China’s large-scale FTTR deployments provide a useful volume counterweight to these specialized data-center and enterprise applications. Master and subtended ONT architectures enable operators to extend fiber connectivity from the residence gateway to individual rooms, creating another demand source for optical endpoints and related PON equipment. Together, these developments suggest that future PON market growth will depend increasingly on diversification beyond conventional residential FTTH—while also requiring vendors to address application-specific management, installation, and interoperability requirements.
The Dell’Oro Group PON in the Data Center and Premise Advanced Research Report includes 5-year market forecasts for PON Optical Line Terminals (OLTs), and PON Optical Network Terminals (ONTs) and Optical Network Units (ONUs) used in Data Center [Out-of-band management (OOBM), infrastructure management (DCIM)], Enterprise/MDU [Passive Optical LAN (POL), Fiber-to-the-room for business (FTTR-B)] , and Fiber-to-the room (FTTR) applications. To purchase this report, please contact us by email at [email protected].
References:
PON in Data Centers Expected to Grow at 52 Percent CAGR from 2026-2030, According to Dell’Oro Group
Dell’Oro: 2H2026 Data Center Capex to Accelerate due to massive AI Deployments
Analysis: Broadcom’s end-to-end 50G PON Edge AI portfolio with WiFi 8 support
Highlights of FiberConnect 2024: PON-related products dominate
Nokia and Google Fiber trial 50G PON – first in the U.S.
Nokia and Hong Kong Broadband Network Ltd deploy 25G PON
HKT is first to deploy 50G PON technology in Hong Kong