Author: Alan Weissberger
Dell’Oro: Global telecom capex increased ~5% YoY; other reports show uneven telco capex
According to a recently published report from Dell’Oro Group, worldwide telecom capex increased about 5% year-over-year (YoY) in the first half of 2026. The stronger-than-expected start to the year follows several years of declining investment and marks an improvement relative to expectations at the beginning of 2026.
Telecom equipment trends remain closely aligned with capex. Aggregate manufacturer revenues across the six telecom equipment programs tracked by Dell’Oro Group—Broadband Access, Microwave Transport, Optical Transport, Mobile Core Network (MCN), Radio Access Network (RAN), and High End Router & Aggregation—also increased approximately 5% YoY in 1H2026.
“The first half was stronger than we expected, but the improving near-term trajectory does not materially change the longer-term capex story,” said Stefan Pongratz, Vice President at Dell’Oro Group. “Operators are in a stronger capacity position following the 5G and fiber investment cycles, and the focus is gradually shifting from coverage toward capacity, modernization, automation, and efficiency. At the same time, improving operator revenues are helping to reduce capital intensity ratios even as network investments remain flat.”
Additional highlights from the September 2026 Telecom Capex report:
- Despite the stronger start to 2026, Dell’Oro Group made only negligible revisions to its longer-term forecast. Worldwide telecom capex is projected to grow at a 0 to 1% CAG between 2025 and 2030, reflecting a more mature investment environment following the major 5G and fiber coverage cycles.
- Capital intensity, which peaked at 18% in 2022, is projected to decline to around 14 percent in 2028, before increasing modestly as early 6G investment emerges.
- Telecom equipment revenues are projected to grow at a 2 to 3% CAGR between 2025 and 2030, outpacing CSP capex, partly reflecting incremental demand from cloud providers.

The Dell’Oro Group Telecom Capex Report provides in-depth coverage of more than 50 telecom operators, highlighting carrier revenue, capital expenditure, and capital intensity trends. The report provides actual and 5-year forecast details by carrier, by region, by country (United States, Canada, China, India, Japan, and South Korea), and by technology (wireless/wireline). To purchase this report, please contact us by email at [email protected]
…………………………………………………………………………………………………………………………………….
Other Voices:
1. Telecoms capex worldwide: trends and forecasts 2020–2032, Rupert Wood, September 15, 2026.
The publicly available summary makes two relevant observations:
-
Telecoms capex has declined since 2022, and whether it will rebound remains an open question.
-
“The useful economic life of telecoms assets is lengthening, and for that reason capex is slowing.”
Its coverage includes eight global regions, 13 individual countries and the EU, with spending broken down by funding source—operators, infrastructure companies, content and application providers, and enterprises—and by network asset type. It also distinguishes infrastructure from technology, new from legacy networks, and growth from maintenance spending.analysysmason
This report provides an independent structural explanation for subdued investment, rather than another operator-specific snapshot. Its inclusion of nontraditional investors also helps clarify why equipment demand and operator capex can diverge. However, the public summary does not disclose an aggregate growth forecast; I would not attribute a numerical forecast to Analysys Mason without access to the report.
2. Primary financial reports from Deutsche Telekom, Orange and Nokia add useful independent context: investment trends differ substantially by network operator and geography, capital intensity can fall even while spending rises, and equipment suppliers increasingly benefit from cloud demand—not just carrier network investment.
- Deutsche Telekom’s cash capex excluding spectrum fell 4.9% to €7.8 billion in the first half of 2026, primarily reflecting the timing of German fiber investment, while group revenue increased 2.4%.
- Orange’s economic capex rose 2.7% on a comparable basis to €3.2 billion, driven by higher investment in Africa and the Middle East; spending excluding that region declined 2.4%. Orange’s revenue grew faster than investment, allowing its comparable capex-to-revenue ratio to edge down to 15.2%.report.
3. Network Equipment supplier results also highlight a source of equipment demand beyond traditional carrier budgets. Nokia reported first-half sales growth of 6%, while second-quarter Optical Networks and IP Networks sales increased 20% and 16%, respectively, at constant currency. Sales to AI and cloud customers more than doubled, and orders from those customers reached €2.8 billion in the quarter. These results support a distinction between a selective recovery in operator investment and stronger demand for optical and IP infrastructure serving AI and cloud networks.
……………………………………………………………………………………………………………………………………………………………………….
References:
https://www.linkedin.com/feed/update/urn:li:activity:7513319856398610432/
https://www.analysysmason.com/research/content/regional-forecasts-/telecoms-capex-forecast/
Dell’Oro: Data Center capex grew 92% in 2Q-2026 (caveats galore)
Dell’Oro: 2H2026 Data Center Capex to Accelerate due to massive AI Deployments
Dell’Oro: Global telecom CAPEX declined 10% YoY in 1st half of 2024
Dell’Oro: 6G RAN Capex to reach $500 billion by 2034 + Counterpoint
Deutsche Telekom: Device-to-Cloud AI Traffic Won’t Force RAN Upgrades or Increase CAPEX
Hyperscaler AI Race: Soaring Capex Wipes Out Free Cash Flow; AGI and Digital Gods
SpaceX Moves to Acquire Nationwide 800 MHz Spectrum for Starlink Mobile D2D Service
Introduction:
SpaceX announced an agreement on Thursday to acquire Grain Management’s nationwide 800 MHz spectrum portfolio, expanding the spectrum resources available for its Starlink Mobile direct satellite-to-device (D2D) service [1.]. The transaction would give SpaceX a low-band complement to its existing global 2 GHz mid-band spectrum holdings and strengthen its position as a potential competitor to established U.S. wireless operators. The agreement covers 100% of Space X’s nationwide 800 MHz spectrum portfolio. Financial terms were not disclosed, and the acquisition remains subject to Federal Communications Commission (FCC) approval.
Note 1. Starlink’s satellite connectivity plans extend beyond cellphones to broader direct-to-device end points. IoT support is explicitly part of its published roadmap; smartwatch support has yet to be confirmed for general capability. Starlink’s “Direct to Cell” branding describes a cellular satellite-access system, not a smartphone-only endpoint strategy. Starlink’s official Direct to Cell page states:
“In addition to expanding mobile coverage, Direct to Cell will enable ubiquitous Internet of Things (IoT) connectivity outside of terrestrial coverage, connecting millions of devices across critical global industries.”
………………………………………………………………………………………………………………………………………………………………
Low-band spectrum complements 2 GHz capacity:
The acquisition would add a coverage layer to Starlink Mobile’s spectrum strategy. While its existing 2 GHz spectrum is intended to support higher-bandwidth services, the 800 MHz portfolio would provide more favorable propagation characteristics, including improved penetration through obstacles such as foliage and building materials.
Those characteristics could help address signal attenuation—a significant constraint for satellite-to-smartphone connectivity. However, favorable low-band propagation should not be equated with assured indoor service; the announcement does not establish the coverage or performance that Starlink Mobile would deliver inside buildings.
The acquisition could expand SpaceX’s ability to provide mobile coverage from orbit, but it does not establish that the company intends to dispense with terrestrial infrastructure.
Regulatory approval and competitive implications:
Separately, the FCC approved Starlink Mobile’s Gen2 constellation application this week, according to the supplied Reuters report. That authorization permits SpaceX to launch 15,000 satellites optimized for operation in the 2 GHz band globally. The constellation authorization and the proposed 800 MHz acquisition are distinct regulatory matters: approval of the former does not constitute approval of the spectrum transaction.
Shares of T-Mobile US, Verizon and AT&T each fell more than 5% in extended trading today. The declines reflected investor concerns that SpaceX’s expansion into mobile connectivity could intensify price competition and pressure incumbent operators’ market share in the mature U.S. wireless market.
The strategic significance is the combination of additional low-band spectrum and an expanded satellite constellation. Whether those assets translate into a competitive alternative to terrestrial mobile networks will depend on regulatory approval and the coverage, capacity and service performance SpaceX ultimately delivers.
Technical implications: propagation, capacity and handset compatibility:
The engineering significance of the acquisition extends beyond improved signal penetration. Satellite-to-smartphone services must accommodate propagation distances far greater than those in terrestrial cellular networks, while maintaining reliable communication with ordinary handsets. Operating frequency, satellite altitude, antenna design and beam geometry therefore jointly determine the achievable coverage and service performance. Lower-frequency spectrum offers a useful propagation advantage, but it does not eliminate those system-level constraints.
Capacity is a separate issue. The description of 800 MHz as a coverage layer and 2 GHz as a capacity layer is a useful shorthand—not an intrinsic division between the two frequency bands. Available bandwidth and the ability to form and reuse satellite spot beams matter alongside propagation. Narrower beams can improve spatial isolation and help manage satellite-link impairments, but they require larger antennas; maintaining coverage with smaller beam footprints can also require more beams or additional satellites. Consequently, nationwide spectrum holdings should not be confused with nationwide terrestrial-equivalent capacity.
Satellite operation requires more than a compatible frequency band:
Direct-to-device systems must compensate for the propagation delay and Doppler shift associated with rapidly moving low-Earth-orbit satellites. In systems serving unmodified LTE smartphones, the network performs that compensation. Residual timing and frequency errors vary across the satellite beam and can disrupt initial access, while longer round-trip delays can reduce the efficiency of retransmission protocols. Low-band spectrum does not remove these protocol constraints.ericsson
Handset compatibility also requires a distinction between two approaches. Satellite systems using a conventional LTE air interface can serve existing smartphones in supported terrestrial cellular bands. By contrast, 3GPP Release 17 NR-NTN introduces satellite-specific capabilities, including handset-based timing and frequency compensation using the device’s location and satellite orbital information. These capabilities require compatible chipsets and devices; support for an 800 MHz cellular band alone does not establish support for NR-NTN. The spectrum acquisition therefore should not be characterized as a 5G NTN deployment without disclosure of the intended air interface and device requirements.ericsson
Nationwide spectrum helps—but does not eliminate interference constraints:
Nationwide exclusive access to terrestrial mobile spectrum can simplify satellite deployment by reducing domestic co-channel coexistence problems. However, satellite beams do not stop at national borders. Operations still require interference controls and coordination to protect terrestrial systems in neighboring countries. Depending on the authorization and deployment model, those controls can include geographic exclusion zones and restrictions on satellite transmission parameters.
Indoor Coverage is Highly Unlikely:
Improved propagation is an engineering advantage; reliable indoor service remains a performance claim that needs supporting specifications or measurements. The technical evidence instead emphasizes the interdependence of frequency, antenna design, satellite geometry and protocol behavior.
………………………………………………………………………………………………………………………………………………
Grain Management Backgrounder:
“For nearly twenty years, we have built Grain to see opportunity where others see complexity,” said David Grain, Founder and Chief Executive Officer of Grain Management. “Our spectrum expertise allows us to connect the strategic value of these assets with the technologies and operators that can realize their potential. This agreement with SpaceX brings that capability to bear at extraordinary scale, with the potential to change where and how Americans connect.”
Grain combines deep sector experience, strategic insight, and capital to unlock spectrum value, advance its productive use, and help operators meet evolving connectivity needs. Grain’s acquisition of the nationwide 800 MHz portfolio from T-Mobile in August 2026 extends that approach – the firm acquired the portfolio in exchange for cash and Grain’s 600MHz spectrum, then pursued multiple use cases that would expand connectivity for American consumers and create value for the industry, Grain’s investors, and the people whose futures they support.
“Spectrum is a finite resource with an expanding role in the economy,” Grain added. “As terrestrial and space-based networks converge, we see a new horizon globally for our spectrum strategy, building on our experience to address larger industry challenges and help shape the next generation of connectivity.”
…………………………………………………………………………………………………………………………………………………………
Separately, Space X today signed a fleet-wide deal with American Airlines to equip over 1,000 mainline aircraft with Starlink internet access. Starlink will bring fast, reliable Wi-Fi to customers throughout their journey, making it easier to stay connected from gate to gate. Whether responding to emails, catching up on messages, streaming favorite shows, browsing the web or keeping the family entertained, customers can enjoy a seamless online experience in the air.
“Our customers have told us that dependable connectivity can make a meaningful difference in how they spend their time in the air,” said American’s Chief Customer Officer Heather Garboden. “Whether they are livestreaming a favorite show, gaming, collaborating in real time on an important work deal, scrolling social media or online shopping, Starlink will give our customers countless options to make the most of their time while traveling. Just as importantly, it provides the foundation for future innovations that will further enhance the customer experience.”
“We’re thrilled to bring Starlink across American’s mainline fleet,” said Lauren Dreyer, Vice President of Starlink Business Operations at SpaceX. “Customers will have fast, reliable internet from gate to gate, whether they are streaming, working, or staying connected to family and friends throughout their travel.”
……………………………………………………………………………………………………………………………………………….
References:
Starlink Mobile: NTN–Terrestrial Convergence, Network Capacity, and the Limits of Disruption
FT: SpaceX considering Starlink Direct-to-Consumer mobile service & terrestrial cellular network infrastructure in the U.S.
Ookla: Starlink a viable competitor for hybrid 5G/NTN services due to network performance improvements and larger coverage area
Ookla: D2D satellite connectivity surged 24.5% during last 9 months; Starlink’s footprint expansion leads the way
US Mobile’s new bundle combines its multi-network mobile service with Starlink residential internet
Direct-to-Device (D2D) satellite network comparison: Starlink V2 (Starlink Mobile) vs “Satellite Connect Europe”
Blue Origin announces TeraWave – satellite internet rival for Starlink and Amazon Leo
China ITU filing to put ~200K satellites in low earth orbit while FCC authorizes 7.5K additional Starlink LEO satellites
Starlink doubles subscriber base; expands to to 42 new countries, territories & markets
Amazon Leo (formerly Project Kuiper) unveils satellite broadband for enterprises; Competitive analysis with Starlink
Deutsche Telekom: Device-to-Cloud AI Traffic Won’t Force RAN Upgrades or Increase CAPEX
Introduction:
Deutsche Telekom is in the process of “upgrading mid-range plans,” according to Dhananjay Mirchandani, DT’s senior VP for group controlling and the group’s next CFO from May 1, 2027. “I cannot recall a single conversation in which Alex Jenbar [CTO of Telekom Deutschland] … or somebody else approached us and said, ‘in addition to whatever we currently have on our roadmaps for RAN modernization, that there is an incremental requirement for an investment to be able to prepare ourselves for additional uplink/AI-related traffic,'” he said. “[That’s] just to give you a sense of the degree of confidence we have in terms of our own capex planning, specifically related to mobile network capacity,” he added.
His assessment on medium-term mobile capacity is bound to be sobering for its radio access network (RAN) vendors in Germany: Ericsson, Huawei and Nokia.
The rise of agentic and physical AI could upend decades of mobile network design that dedicates most bandwidth to download speeds (i.e., downlink) and much less to the data channels for uploads (i.e., uplink). It’s not certain how or when traffic patterns will change in a big way, but telcos are talking about preparing for a wave of AI-fueled traffic coming from smartphones, smart glasses or robots.
The Reality Check – No Incremental RAN Capex:
During an investor event, financial analysts directly pressed Deutsche Telekom’s incoming CFO, Srinivas Mirchandani, on whether capital intensity would escalate after 2027 to handle the upstream traffic generated by physical AI, wearables, and smartphone-based LLM queries.
• The Stand: Mirchandani honestly noted that he could not recall a single internal conversation where the CTO of Telekom Deutschland (Alex Jenbar) requested incremental investment beyond their existing radio access network (RAN) modernization roadmaps to handle AI uplink traffic.
• The Baseline Numbers: DT’s long-term guidance (established at its 2024 Capital Markets Day) mandates that capital spending outside the U.S. and spectrum will sit at 21% of service revenue by 2027. While DT is trading slightly above that now, it is entirely due to heavy fiber-optic rollouts in Germany, not mobile radio expansions.
| Attribute | Deutsche Telekom (Europe Group) | T-Mobile US |
|---|---|---|
| Capex Stance | Rigid cap on mobile intensity; excess savings diverted strictly to German landline fiber infrastructure. | Confirmed network architecture expansion funded via standardized 5G-Advanced cycles. |
| AI Traffic Philosophy | Believes traffic peaks are manageable within existing, scheduled modernization roadmaps. | Views the network explicitly as the “connective tissue for physical AI and AI wearables.” |
| Uplink Solutions | Delaying heavy structural changes; emphasizing spectrum efficiency under legacy boundaries. | Implementing Uplink Carrier Aggregation, Uplink MIMO, and Transmit Switching under 5G-Advanced. |
- Delaying Capex via Software: Panelists from across the telco ecosystem—including Turkcell and Deutsche Telekom’s own group partnering division—noted that AI is actually delaying capex cycles rather than accelerating them. Operators are deploying AI algorithms inside the radio access network to optimize power consumption, conduct predictive capacity planning, and boost edge throughput. In short: AI software is making existing hardware last longer.
- The Opex ROI Conundrum: Telcos are seeing immediate financial returns from “AI for the network” (e.g., DT projects €2.5 billion in cumulative cost savings by 2030 through AI automation). However, the business model for a “network for AI”—where consumers or enterprise clients pay a premium for high-speed, low-latency uplink to feed remote LLMs—remains entirely unproven.
- The 6G Boundary Wall: Based on this author’s carrier checks, most Tier-1 network operators now view massive, structural upstream re-architecting as a “6G-era investment narrative” rather than an immediate 5G sub-6GHz demand. Until dedicated enterprise use cases validate moving further up the value chain, hardware vendors will have to wait for a significant revenue lift from device-to-cloud AI traffic.

Source: Deutsche Telekom, Photo: Norbert Ittermann
…………………………………………………………………………………………………………….
Conclusions:
Deutsche Telekom (DT) indicates that rising device-to-cloud traffic volumes will not necessitate premature radio access network (RAN) upgrades. Technical analyses suggest that upcoming capacity demands driven by agentic AI may not immediately accelerate RAN capital expenditure.
DT does not see AI uplink traffic driving an incremental increase to its RAN capex plans in the medium term. DT is holding a rigid perimeter around its long-term financial guidance. By 2027, capital intensity (excluding the U.S. and spectrum) is strictly capped at 21% of service revenues. Excess capital is not being funneled into expanding cell site capacities for upstream AI traffic; it is being aggressively diverted toward landline fiber-optic buildouts in Germany.
-
- Uplink Carrier Aggregation (CA): Allows the network to combine multiple frequency bands (e.g., mid-band and low-band) exclusively for the upstream path. This maximizes the utilization of already-deployed spectrum without requiring operators to acquire or build new macro tower infrastructure.
- Uplink MIMO & Transmit Switching: Enhances data throughput from consumer AI wearables and smartphones back to the cloud by multiplying the data paths between the device and the tower antenna arrays. [
- Network Slicing: Under 5G SA, carriers can allocate a virtualized, highly efficient “slice” of the existing spectrum explicitly for low-latency AI queries. Slicing can improve resource allocation and protect selected service requirements, but it is not a substitute for sufficient uplink capacity. However, it isolates upstream data paths without needing incremental physical hardware upgrades.
References:
https://www.openranforum.com/home
AI-RAN and Agentic AI get real: Ericsson, Nokia, Verizon & other operators enter into a new network automation era
Cisco Execs: New “Network Supercycle” as Agentic AI Workloads Reshape Telecom Infrastructure
Cisco report: Agentic AI to reshape WAN traffic, AI inference will be ~25% of total traffic by 2035
Nokia’s AI Applications Study: “Physical AI” may require RAN redesign to support high‑volume, low‑latency uplink traffic
STL Partners webinar: Agentic AI needed for RAN autonomy & efficiency
The Financial Trap of Autonomous Networks: Scaling Agentic AI in the Telecom Core
AT&T’s 600 MHz Deployment with Ericsson: Turning Low-Band Spectrum Into Coverage and Uplink Capacity
SoftBank’s Transformer AI model boosts 5G AI-RAN uplink throughput by 30%, compared to a baseline model without AI
T‑Mobile achieves record 5G Uplink speed with 5G NR Dual Connectivity
Telstra achieves 340 Mbps uplink over 5G SA; Deploys dynamic network slicing from Ericsson
Finland’s Elisa, Ericsson and Qualcomm test uplink carrier aggregation on 5G SA network
ITU-R WP5D & 3GPP work schedules for development of IMT-2030 terrestrial radio interface (RIT/SRIT) recommendations
Explanation: This post is an update of an IEEE Techblog published October 20, 2025. It also includes the 3GPP Release 21 timeline, which was previously published (see References below). This author expects that the proposed IMT 2030 RIT/SRIT specs submitted will be primarily from 3GPP (contributed to ITU-R WP5D by ATIS). However, any ITU member is invited to submit proposals.
IMT 2030 (6G) Backgrounder:
- Resolution ITU-R 65-1 on the “Principles for the process of future development of IMT-2020 and IMT-2030” outlines the essential criteria and principles that will be used in the process of developing the Recommendations and Reports for IMT-2020 and IMT-2030, including Recommendation(s) for the radio interface specification.
- Recommendation ITU-R M.2160, “Framework and overall objectives of the future development of IMT for 2030 and beyond” identifies six usage scenarios for IMT-2030 and envisions a broad variety of capabilities, tightly coupled with intended usage scenarios and applications for IMT-2030, resulting in a great diversity/variety of requirements. Recommendation ITU-R M.2160 also identifies the capabilities of IMT-2030, recognizing that they will have different relevance and applicability for the different use cases and scenarios addressed by IMT-2030, some of which are currently not foreseen. In addition, IMT-2030 can be applied in a variety of scenarios, and therefore different test environments are to be considered for evaluation purposes.
- A test environment is defined as the combination of usage scenario and geographic environment as described in Report ITU-R M.[IMT-2030.EVAL].
- IMT-2030 Minimum Technology Performance Requirements for Radio Interface Technologies is a report which outlines 20 technical performance requirements (TPR). Seven of them are new and specific to describe the 6G performances. Those IMT 2030 technical performance requirements will be used as unified requirements to evaluate the 6G radio interfaces (RITs/SRITs).
- WP 5D completed the draft IMT-2030 minimum technical performance requirements in February 2026 and the draft evaluation guidelines in June 2026. Both have been submitted to ITU-R Study Group 5 for approval in December 2026.
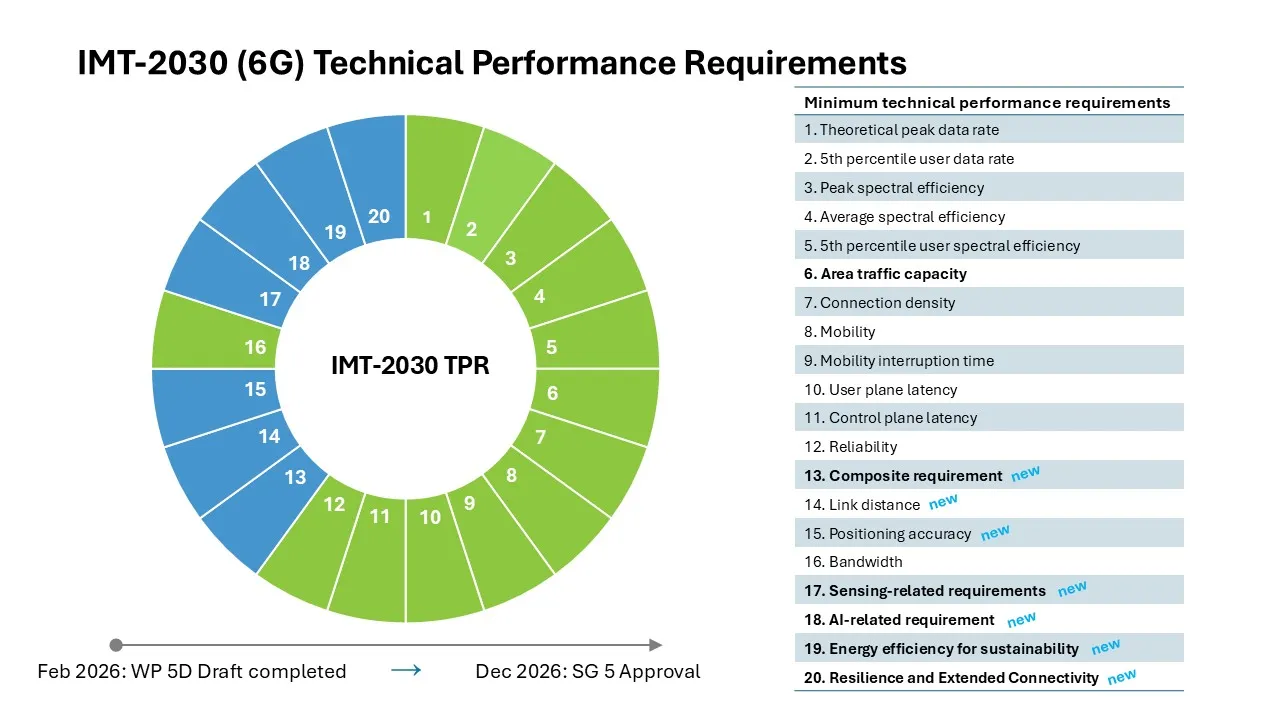
Image Credit: ITU-R WP5D
………………………………………………………………………………………………………………………………………………………………………………………………
ITU-R WP 5D Work Plan for IMT-2030 RIT/SRITs:
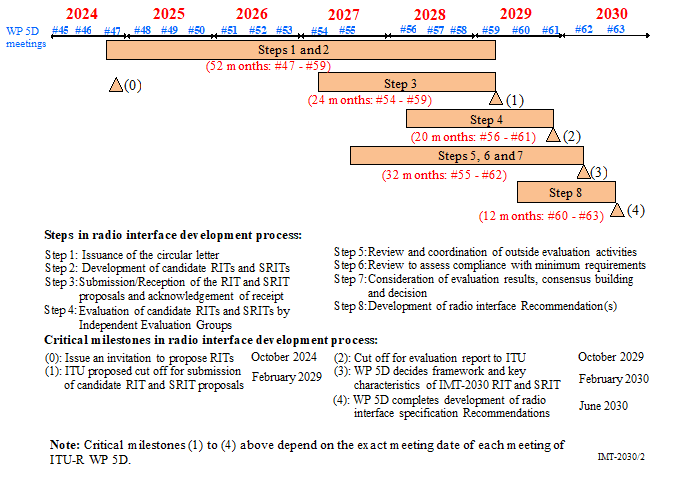
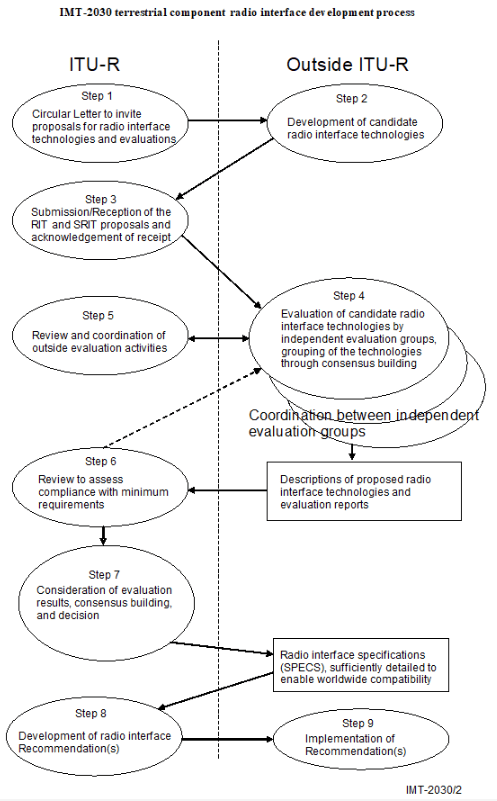
Submission of IMT 2030 RIT/SRIT proposals will begin at 54th meeting of Working Party (WP) 5D (currently planned for February 2027). The final deadline for submissions is 12 calendar days prior to the start of the 59th meeting of WP 5D in February 2029. The evaluation of the proposed RITs and SRITs by the independent evaluation groups and the consensus-building process will be performed throughout this time period and thereafter. The detailed schedule and development process are shown in the two figures below.
 ………………………………………………………………………………………………………………………………………………………………………………
……………………………………………………………………………………………………………………………………………………………………….
Follow on Process for IMT-2030 Final Approval (author’s conjecture):
- The IMT 2030 RIT/SRITs development are scheduled to be completed at WP5D Meeting #63 in June 2030.
- At the next 5D meeting (#64), likely to be in October 2030 (but not yet scheduled), any draft revisions and specification updates will be reviewed and finalized.
- Following completion in WP 5D, the draft IMT 2030 RIT/SRITs and IMT 2030 Frequency Arrangements [1.], recommendations would proceed to ITU-R SG5 (Terrestrial Services) for adoption and then approval under the applicable ITU-R procedure. The dates and approval route remain to be confirmed. However, final approval is likely to be in November or December of 2030.
Note 1: These two IMT 2030 companion recommendations should be finalized and approved as a package (that didn’t happen with IMT 2020 because the ITU-R M.1036-7 Frequency Arrangements recommendation was approved after ITU-R M.2150 was finalized and approved).
………………………………………………………………………………………………………………………………………………………………………………………………
3GPP Release 21 (6G)Timeline:
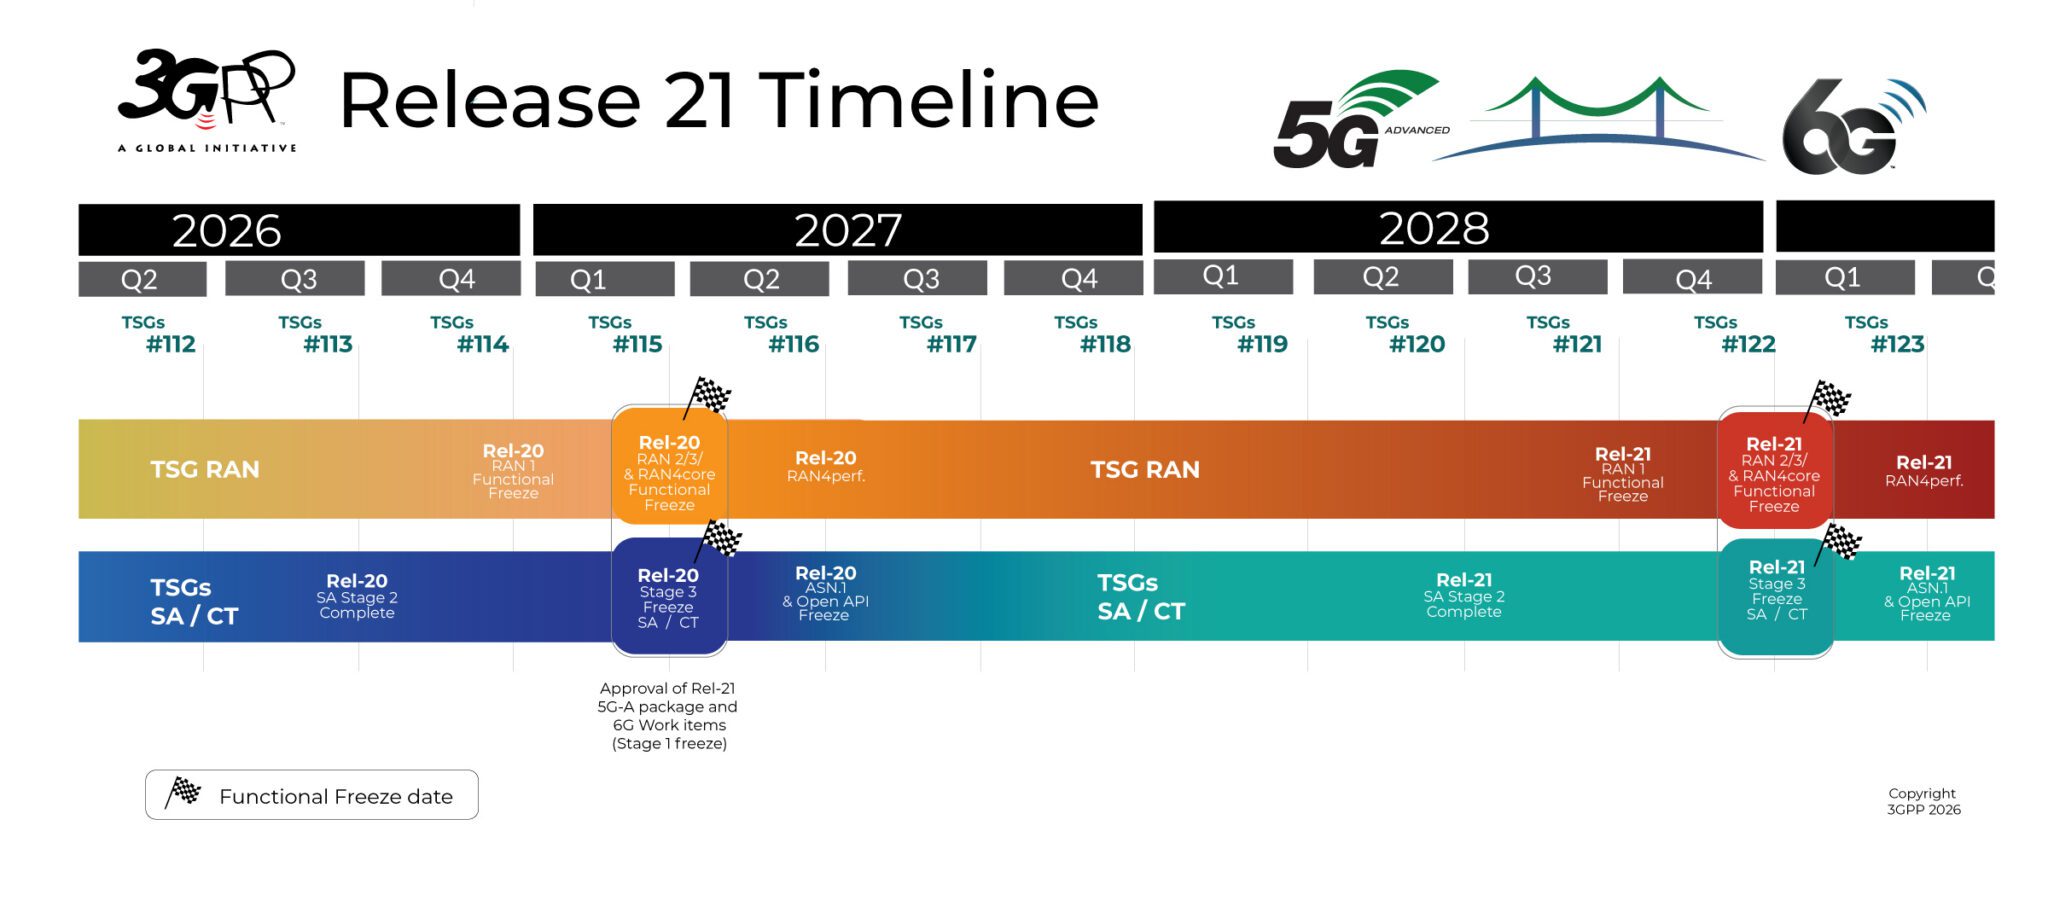
The crucial ITU-R/3GPP schedule relationship:
Here is how the ITU-R submission deadline relates to the 3GPP Release 21 freeze:.
…………………………………………………………………………………………………………………………………………………………….
References:
https://www.itu.int/en/ITU-R/study-groups/rsg5/rwp5d/imt-2030/pages/default.aspx
ITU-R WP 5D Timeline for submission, evaluation process & consensus building for IMT-2030 (6G) RITs/SRITs
Roles of 3GPP and ITU-R WP 5D in the IMT 2030/6G standards process
IMT-2030 (“6G”) Minimum Technology Performance Requirements for Radio Interface Technologies
ITU-R M.[IMT-2030.EVAL] & ITU-R M.[IMT-2030.SUBMISSION] reports: Evaluation & Submission Guidelines for 6G RIT/SRITs (6G)
Sept 2026 3GPP meeting updates for 5G Advanced and 6G planning (with timeline for submisson to ITU-R WP 5D via ATIS)
3GPP approves timelines for Release 21 which will specify 6G RAN, Core and 5G Advanced
Warning: 6G core network must not repeat the 5G SA 3GPP architecture specs vs lack of interoperable standards
FCC plans 6G spectrum auctions before IMT 2030 frequencies have been identified and without a 6G frequency arrangement standard
How NTIA “Call to Action for 6G Leadership and Security” might influence 6G/IMT-2030 standards and 3GPP specifications
Comparing AI Native mode in 6G (IMT 2030) vs AI Overlay/Add-On status in 5G (IMT 2020)
AI-Native 6G RAN in Practice: Research and Validation Insights from 6G-MIRAI-HARMONY
Warning: 6G core network must not repeat the 5G SA 3GPP architecture specs vs lack of interoperable standards
Introduction:
As the global telecom ecosystem pivots from 5G/IMT 2020 towards normative studies for IMT-2030 (6G) in 3GPP Release 20 and Release 21, the air interface (IMT 2030 RIT/SRITs forthcoming recommendation) naturally commands the spotlight. Discussions are dominated by IMT 2030 Technical Performance Requirements like sub-millisecond latencies, Integrated Sensing and Communication (ISAC), and AI-native physical layers. Yet network architects must confront a sobering historical reality: a brilliant radio access network is utterly paralyzed without a functional, universally interoperable core network.
If the telecom industry intends to realize the true commercial and operational promises of 6G, we must urgently dismantle the architectural precedent set during the 5G Standalone (SA) core (lack of) standardization cycle. By bypassing traditional global transport gatekeepers and prioritizing abstract logical modeling over concrete implementation realities, the industry traded the promise of an open, multi-vendor cloud ecosystem for a return to legacy vendor lock-in.
The ITU-T Bypass and the 5G SA Core Network Standardization Gap:
The fragmentation of the 5G SA core network can be traced directly to a structural and geopolitical power struggle.
- Historically, ITU-T Study Group 13 held the global mandate for establishing international standards for non-radio, architectural, and transport layers of all next generation networks. This governance ensured deep multi-vendor interconnectivity and data-plane uniformity across sovereign networks.
- During the development of the 5G Service-Based Architecture (SBA), 3GPP effectively insulated the core network design from ITU-T oversight. 3GPP executives told this author that they did not trust ITU-T to generate the 5G core network standards.
- Instead, the 3GPP specifications (such as TS 23.501 and TS 23.502) were kept entirely in-house and on completion were rubber-stamped by ETSI, 3GPP’s venue host. While this bypass accelerated time-to-market, it created a catastrophic standards-to-implementation gap. 3GPP defined network functions—such as the Access and Mobility Management Function (AMF), Session Management Function (SMF), and User Plane Function (UPF)—as highly abstract, logical blocks.
- While the control plane mandated modern tools like HTTP/2 and RESTful OpenAPIs, this framework merely established interface syntax. It completely omitted the exhaustive behavioral guardrails, edge-case definitions, and low-level realization mechanics required to build a production-ready, cloud-native core. That disconnect led to different network operator implementations of the 5G SA Core, depending on the vendor(s) they selected.
The Illusion of Interoperability:
The practical consequence of this abstraction is well known to any tier-1 network operator that has attempted a multi-vendor 5G SA core network deployment. On paper, the 5G SBA is modular. In reality, an operator cannot reliably procure an AMF from Vendor A, an SMF from Vendor B, and a UPF from Vendor C, connect them via standard 3GPP interfaces, and achieve a stable, carrier-grade network. The specifications are simply too loose.
Crucial underlying implementation details—such as cloud-native container orchestration pipelines, state database synchronization, database persistence layers, and hardware-accelerated UPF data planes—were left entirely outside the scope of the standard. To fill this vacuum, major infrastructure vendors engineered proprietary software logic beneath the “open” APIs. Consequently, multi-vendor core deployments required immense, custom, and cost-prohibitive systems integration efforts. For most operators, the path of least resistance was a return to single-vendor silos.
When 3GPP kept the Service-Based Architecture (SBA) work entirely in-house, they defined the network functions (like AMF, SMF, and UPF) as abstract, logical blocks rather than concrete blueprint specifications:
-
- The Interface Gap: 3GPP dictated the use of HTTP/2 and RESTful OpenAPIs for the control plane. While that sounds open, it merely defined the syntax, not the exhaustive behavior required when edge cases or multi-vendor implementations collided.
- No Implementation Blueprint: Crucial components required to construct an actual, production-ready 5G SA core—such as cloud-native container orchestration pipelines, underlying state database synchronization, database persistence layers, and low-level User Plane Function (UPF) acceleration mechanics—were entirely omitted.
The Practical Outcome: A Return to Vendor Lock-In:
Because 3GPP’s architectural specs lacked concrete realization guidelines and strict inter-vendor edge-case definitions, a major interoperability gap emerged:
- Custom Customization: An operator cannot realistically buy an AMF from Vendor A, an SMF from Vendor B, and a UPF from Vendor C, plug them together over standard 3GPP interfaces, and expect a stable network. The specs are too loose.
- The “Joint Specification” Reality: In practice, every major 5G SA core deployed requires extensive, customized, and often proprietary software engineering ironed out directly between the wireless operator and a single primary core vendor (such as Huawei, Ericsson, or Nokia).
- Network Slicing Disarray: This gap severely crippled Network Slicing. While 3GPP authored elegant logical diagrams for end-to-end network slicing, the absolute lack of unified, cross-domain transport realization standard meant that slicing remained confined to single-vendor testbeds and highly customized, non-scalable deployments for years.
Source: Siarhei Yurchanka/Alamy Stock Photo
The Warning Signs for IMT-2030:
As we look ahead to 6G and IMT 2030 recommendations, the ITU-T remains largely sidelined from mobile core network architecture. 3GPP operates as the de facto absolute authority on both the radio and the cloud core stack. If left uncorrected, the structural loop will repeat. 3GPP will deliver an idealized, highly complex, AI-driven 6G core architecture on paper, leaving actual functional implementations to be sorted out via proprietary vendor middleware.
Light Reading reports, that there are currently three competing 6G core architectures within 3GPP, which threatens to splinter their specs for 6G core networks. Most network operators prioritize affordable evolution, but debates over who controls device intelligence and revolutionary design risk causing divergence. Two fundamental points have emerged: how to handle or embed AI functionality and what to do with non-access stratum (NAS) signaling. NAS is the secure signaling pipeline between the device and core network, handling authentication, encryption, mobility management and session setup. Mobile architectures have relied on it as a foundational pillar since 2G (GSM), embedding it in device baseband silicon and SIM security frameworks.
Reworking NAS requires modem redesign, core security procedure overhaul and device backward-compatibility planning. Inside 3GPP SA2, the study phase has identified three candidate directions for the core network (based on AI functionalities):
- Direction 1 – Separate AI domain: A dedicated AI domain for intent handling independent of the packet-switched network, with the AMF routing NAS signaling while AI fulfillment occurs via SBI; backed by Nokia, T-Mobile USA, Verizon, NVIDIA, Deutsche Telekom, Apple, Qualcomm, Ericsson and NEC, though implementation requires complex UE AI domain client integration.
- Direction 2 – AI functionality in 6G NFs approach: Integrates AI through dedicated 6G network functions following standardized 3GPP procedures with flexible NAS routing (standalone or combined with core functions like AMF); supported by NTT DOCOMO, Samsung, LG Electronics, NEC, IIT Bombay, Vodafone, Apple and China Telecom (partly).
- Direction 3 – AI/agent-handled connectivity approach: Deeply integrates AI/agents into network procedures with dynamic coordination of capabilities and tool invocation, utilizing a signaling routing function (SRF) independent of AMF with user/control plane integration; aligned with Huawei, HiSilicon, China Mobile, ZTE, vivo, CATT, ETRI, Ewha Womans University and OPPO (partly), though it introduces high procedural disruption.
Of these three paths, the first (Direction 1, separate AI domain) has gained the most traction among Western operators and vendors (T-Mobile USA, Verizon, Deutsche Telekom, Nokia, Ericsson, NEC, NVIDIA and, to some extent, Apple). Anchoring the core to the 5G service-based architecture (SBA) interface preserves 5G core investments while letting intent handling mature alongside existing services. However, choosing a direction without standardizing the underlying AI Model Interchange Formats or Agent-to-Agent telemetry will create a brand new flavor of proprietary vendor lock-in.
Conclusions & Engineering Mandates for the 6G Core:
To prevent an amplification of the 5G SA core interoperability deficit, the global engineering community must pivot away from abstract logical modeling. If 3GPP selects an architectural path for IMT-2030 without standardizing the deep execution and semantic layers, we will simply replace legacy infrastructure silos with an unmanageable layer of proprietary AI middleware.
We must advocate for four critical shifts in our approach to 6G core network standardization:
- Mandate Behavioral, State, and Data Realization: Future core specifications must move beyond simple API syntax definitions and logical block diagrams. 3GPP must explicitly standardize end-to-end state-machine behaviors, cross-vendor error-handling conditions, and database synchronization baselines—specifically defining the realization mechanics for stateless network functions and the Unstructured Data Storage Function (UDSF) layer across multi-vendor boundaries.
- Standardize AI Semantic Frameworks and Agent Telemetry: Choosing a 6G core direction without anchoring it to open, deterministic data layers will trigger an unprecedented form of algorithmic vendor lock-in. Standards must rigidly define AI Model Interchange Formats, intent-handling taxonomies, and Agent-to-Agent telemetry protocols. If an autonomous agent invokes a tool or alters network routing dynamically, its procedural boundary conditions must be universally verifiable across competing vendor stacks.
- Bridge the Transport and Cloud-Native Infrastructure Void: 3GPP must abandon its isolationist posture and actively co-author implementation blueprints with open-source infrastructure bodies (such as the Linux Foundation’s telecom initiatives and the Cloud Native Computing Foundation). Specifications must establish standardized, open baselines for underlying container orchestration, state-data persistence, and low-level user-plane hardware acceleration using eBPF (Extended Berkeley Packet Filter) or DPDK (Data Plane Development Kit) architectures.
- Prioritize Cross-Domain Transport Mapping from Day One: Inter-operator roaming and cross-domain networking cannot be treated as downstream implementation details or left to bilateral vendor agreements. 3GPP must natively bake the mapping mechanics between mobile network slices (S-NSSAI) and IETF-defined transport network layers (such as Segment Routing over IPv6 – SRv6) directly into the initial 6G core architecture.
If 6G is to debut as a truly transformative, global platform rather than an incremental upgrade to radio spectral efficiency, we must bridge the chasm between paper standards and software reality. The architecture of the 6G core must be built from its inception for actual cloud realization, absolute multi-vendor interoperability, and rigorous operational clarity. We cannot afford another ghost in the machine.
If 6G is to be a truly transformative global platform rather than an incremental upgrade to radio efficiency, we must bridge the gap between paper standards and software reality. The architecture of the 6G core must be built for actual realization, true multi-vendor interoperability, and absolute operational clarity. We cannot afford another ghost in the machine like we had with the 5G SA core network specs.
References:
https://www.lightreading.com/6g/the-6g-core-divide
https://techblog.comsoc.org/2024/12/18/5g-network-slicing-progress-report-with-a-look-ahead-to-2025/
Building and Operating a Cloud Native 5G SA Core Network
Evaluating Gaps and Solutions to build Open 5G Core/SA networks
Omdia’s 2025 Mobile Core Network Leaders: Huawei #1 in market share; Nokia #1 for portfolio competitiveness
Telco investments in mobile core networks surge 83% in 2025-Q4, but what about ROI?
Téral Research: 5G SA core network deployments accelerate after a very slow start
Dell’Oro: RAN market stable, Mobile Core Network market +14% Y/Y with 72 5G SA core networks deployed
Huawei–Qualcomm Patent Deal: a reset for 5G, AI, and Networked Computing IP
Executive Summary:
On October 5th, Huawei and Qualcomm announced a multi-year, broad patent-license agreement spanning 5G, computing, artificial intelligence, and networking. The agreement provides cross-licenses to the two companies’ patent portfolios and includes Qualcomm’s purchase of certain Huawei U.S. patents in computing, AI, networking, and unspecified additional technical fields. Closing remains subject to required regulatory approvals, and neither company disclosed the financial value, patents transferred, geographic scope, royalty structure, term, or product-specific rights.
The companies framed the arrangement as consistent with fair, reasonable and non-discriminatory licensing principles. That language matters. FRAND commitments normally attach to standard-essential patents, or SEPs, whose use is unavoidable when implementing a technical standard. Yet the stated scope reaches beyond conventional cellular SEP licensing into computing, AI, and networking—areas likely to include a mixture of SEP and non-SEP implementation, architecture, semiconductor, and systems patents.
For the telecom sector, the central significance is not that Huawei and Qualcomm have suddenly become commercial partners. The companies did not announce a chip supply agreement, joint product development effort, network-equipment integration program, or relaxation of U.S. technology controls. Rather, they have reduced one category of strategic uncertainty: reciprocal exposure to patent claims across a widening set of overlapping technology markets.
At a glance:
-
The agreement includes Qualcomm’s purchase of certain Huawei US patents related to computing, AI and networking, Huawei said in a statement.
-
It is Huawei’s first patent licensing deal with Qualcomm that covers 5G technologies.
-
Huawei said the deal is expected to push the total value of its patent licensing agreements to more than $6.9 billion once completed.
-
The company said its intellectual property licensing business has generated positive revenue since 2021, reflecting years of heavy investment in research and development.
-
Huawei ramped up R&D spending in recent years, as US trade restrictions since 2019 have limited its ability to buy advanced chips and crucial software.
-
Huawei made its first licensing payment to Qualcomm in 2001, while it received its first licensing income in 2011 from Motorola.
-
The Qualcomm agreement follows a licensing deal with HP Inc announced by Huawei in August 2026.

Why the patent licensing scope matters:
The announced scope—5G, compute, AI, and networking—tracks the technological convergence reshaping telecom infrastructure.
This is the practical backdrop to the agreement. The industry is moving from a model in which cellular patent licensing could be discussed principally in terms of handsets and modem technology to one in which radios, accelerators, devices, private networks, edge systems, AI infrastructure, and enterprise networking increasingly interact.
A future 5G-Advanced or 6G deployment may incorporate AI-based radio-resource management, cloud-native network functions, edge inference, high-speed fronthaul and backhaul, specialized processors, and new interconnect architectures. Patent boundaries do not necessarily follow clean organizational boundaries between a handset modem supplier, a network-equipment vendor, a data-center platform provider, and an AI-compute company.
The Huawei–Qualcomm accord reflects that reality. It addresses IP access across the technical layers rather than treating 5G as a self-contained radio-standard licensing category.
A significant shift in Huawei’s licensing posture:
Huawei’s intellectual-property licensing business has become strategically more visible as U.S. export restrictions have constrained the company’s access to advanced chips, design tools, and other technology inputs. Reuters reported that Huawei said the Qualcomm agreement, once complete, is expected to bring the total value of its patent-licensing agreements above $6.9 billion. Huawei also said that its IP licensing business has generated positive revenue since 2021.
That does not disclose the value of the Qualcomm transaction itself. It does, however, demonstrate that Huawei views patent licensing as more than a defensive function. The company is using its accumulated R&D output as a commercial asset, especially in markets and technology segments where product sales are shaped by geopolitical restrictions or procurement barriers.
Huawei has long argued that it has made substantial standards contributions in cellular technology. In the joint announcement, Huawei highlighted its work in 4G and 5G, including polar codes, while Qualcomm emphasized its own foundational wireless technologies and the global acceptance of its 5G SEP licensing program.qualcomm+1
The mutual recognition is revealing. Qualcomm’s licensing organization, Qualcomm Technology Licensing, has historically been one of the industry’s most important SEP licensors. Huawei, meanwhile, has worked to establish itself as a major technology contributor and licensor rather than solely as a licensee of Western-originated communications IP. The new agreement positions both companies as holders and users of strategically valuable portfolios across the broader compute-network-AI stack.
The 5G dimension:
Reuters described the transaction as Huawei’s first patent licensing deal with Qualcomm that covers 5G technologies. That point is more material than it may initially appear. 5G licensing is not simply a continuation of earlier 3G and 4G licensing arrangements. It encompasses a more diverse implementation landscape:
-
Massive-MIMO and advanced antenna systems.
-
Flexible numerology and broader spectrum support.
-
Ultra-reliable and low-latency communications features.
-
Network slicing and service-based core architectures.
-
Virtualized and cloud-native RAN and core implementations.
-
Private-network and industrial deployments.
-
Fixed wireless access, integrated access and backhaul, and increasingly AI-assisted optimization.
The licensing challenge is therefore expanding in parallel with the market. In earlier cellular generations, the primary commercial unit was often a phone or modem-equipped device. In 5G, relevant implementation questions can also arise in enterprise gateways, fixed-wireless equipment, industrial modules, routers, private-network infrastructure, distributed RAN systems, and cloud-hosted network functions.
The agreement could reduce licensing friction in technology areas where both companies have extensive engineering programs and potential freedom-to-operate concerns. It does not establish a universal industry royalty benchmark, nor does it reveal either company’s licensing terms. But it removes the prospect of bilateral patent disputes becoming another source of uncertainty in 5G infrastructure and connected-computing markets.
AI and wireless networking are strategic markets:
The inclusion of AI and wireless networking should not be treated as decorative language appended to a cellular patent deal. It signals that both companies see IP value moving into the architecture around wireless connectivity.
For Qualcomm, the expansion aligns with its effort to participate more broadly in AI-enabled computing, industrial systems, edge platforms, and infrastructure—not only smartphone application processors and cellular modems. Qualcomm characterized itself in the announcement as a computing company operating across personal devices and large-scale infrastructure.
For Huawei, AI and networking patent rights are strategically important because the company remains active across telecom equipment, enterprise networking, cloud, data centers, AI hardware and software, and edge infrastructure. Its IP portfolio is therefore likely to span elements relevant to AI-enabled networks, high-performance networking, acceleration, orchestration, and systems integration.
The agreement does not specify the assets involved, making it impossible to assess whether the transferred U.S. patents concern AI accelerators, interconnect technologies, network control, edge architectures, processor design, or software implementation. It would be premature to infer a specific product strategy from the deal.
Still, Qualcomm’s decision to purchase Huawei U.S. patents indicates that it identifies value in owning—not merely licensing—selected IP assets. In practical terms, acquired patents can strengthen a company’s defensive position, broaden its licensing portfolio, support cross-licensing negotiations, or provide potential enforcement rights in relevant markets. The transaction is subject to regulatory approvals, so even this aspect remains incomplete.
Huawei R&D and Patent Policy:
According to its annual report, Huawei invested 192.3 billion yuan (US$28.7 billion) into research and development in 2025, equal to nearly 22 per cent of its total revenue. One of the world’s largest patent holders, Huawei held 165,000 active granted patents worldwide as of 2025.
In 2022, Huawei founder Ren Zhengfei urged the company’s intellectual property team to step up efforts to turn its vast pool of patents into revenue via “reasonable pricing” and to “generate an appropriate return” on its investments.
In June 2026, Huawei announced that it would start charging royalties for its Wi‑Fi 7 [aka IEEE 802.11be Extremely High Throughput (EHT)] technologies, the newest wireless standard, with the rate set at 50 US cents per unit. A key player in Wi-fi licensing, Huawei’s patent licensing deals covered 1.6 billion devices globally by the end of 2025, the firm said.
Executive Quotes:
“Qualcomm has invested in foundational wireless technologies that have enabled successive generations of mobile innovation and earned broad recognition across the global wireless industry. This agreement reaffirms industry recognition of Qualcomm’s 5G technology leadership and the success of Qualcomm’s 5G SEP licensing program,” said John Han, Executive Vice President and General Manager of Qualcomm Technology Licensing. “This agreement likewise reflects Qualcomm’s recognition of Huawei’s continued innovation and intellectual property in 5G and other technology fields.”
“Huawei’s decades of sustained investment in fundamental R&D have driven innovation and progress in mobile communications and other technology fields. Huawei’s broad contributions to the 4G/5G standards, such as the near-physical-limit signal transmission technology using polar codes, have established Huawei’s leadership in the mobile communications industry, and continuously transformed the way people communicate and live,” said Alan Fan, Huawei’s Chief Intellectual Property Officer. “This agreement not only demonstrates the value of Huawei’s innovations, but also recognizes Qualcomm’s foundational contributions to modern communication technologies.”
Conclusions:
The Huawei–Qualcomm agreement is best viewed as a strategic IP normalization deal at the intersection of 5G, AI, compute, and networking. It recognizes that the center of gravity in communications technology is shifting from isolated wireless functions toward integrated systems that combine radios, processors, AI workloads, cloud software, and high-speed networks.
Its most important immediate effect is to reduce uncertainty between two major patent holders. Its most important broader message is that the next phase of telecom innovation—and of telecom IP licensing—will not be confined to the air interface.
The deal also underscores a practical reality for 5G-Advanced and emerging 6G ecosystems: the relevant IP stack increasingly extends from spectrum-efficient radio techniques and network protocols to AI inference, accelerator architectures, cloud-native control systems, edge platforms, and data-center interconnect. Companies that treat these as separate legal, technical, or commercial domains may be working from an outdated map.
……………………………………………………………………………………………………………………………
References:
https://www.huawei.com/en/news/2026/10/qualcomm-broad-patent-agreement
Huawei, Qualcomm, Samsung, and Ericsson Leading Patent Race in $15 Billion 5G Licensing Market
Huawei and Ericsson renew global patent cross-licensing agreement
5G Specifications (3GPP), 5G Radio Standard (IMT 2020) and Standard Essential Patents
Huawei or Samsung: Leader in 5G declared Standard Essential Patents (SEPs)?
AI Debt Wave Implications: Higher interest rates with enormous AI sales required for ROI
Executive Summary:
Artificial Intelligence (AI) debt fueled infrastructure buildouts have become a broad fixed-income-market supply shock. The Wall Street Journal reports that 49% of new investment-grade bond issuance year to date in 2026 has been AI-linked—a figure that underscores how the financing of data centers, compute infrastructure and supporting power systems is reshaping bond market fundamentals and technical factors.
As the supply of long-dated bonds rises, prices fall and yields rise until investors are compensated enough to absorb them. The AI buildout is adding enormous corporate debt from hyperscalers, data-center developers, semiconductor and networking suppliers, and utilities—while also driving public borrowing for grid, power, water and transportation infrastructure. This is putting upward pressure on yields across Treasuries, corporate bonds and municipal debt. This heavy concentration of long-dated supply creates a crowding-out effect that forces non-AI issuers to compete against elevated benchmark yields and potentially stifles broader economic growth, especially for companies not involved in circular AI funding deals (see References).
AI is capital intensive (see Table 1. below). Building data-center capacity requires cash not only for GPUs and servers, but also for land, buildings, fiber, networking, cooling, power procurement, backup generation, substations, transmission and water systems. The major hyperscalers can fund part of that investment from cash flow, but they are also issuing lots of new bonds and notes to preserve liquidity and accelerate buildouts. Their suppliers, data-center partners and power providers are doing the same. Much of this borrowing is long dated—exactly where the Treasury is issuing heavily to finance federal deficits.
The result is an expanding pool of long-duration debt competing for the same institutional buyers: insurers, pension funds, mutual funds, banks, foreign investors and asset managers. When those buyers do not increase their allocations at the same pace as supply, issuers must offer higher yields. Here’s the flow chart that loops around indefinitely until there is an AI crash!:
More AI related bond supply→lower prices→higher yields→higher term premium for U.S. Treasuries→higher budget deficits to finance the increased debt→more bond supply→etc.
……………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………………….
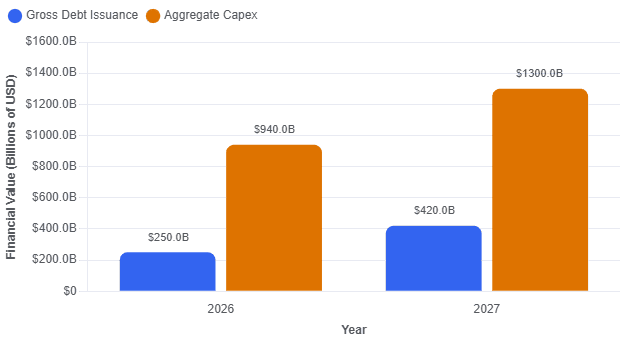
- 2026 Debt Issuance: Projected between $220 billion and $250+ billion for major US hyperscalers (Alphabet / Google, Amazon, Meta, Microsoft, and Oracle), with broader AI-related market debt reaching up to $570 billion.
- 2027 Forecast: Goldman Sachs projects direct hyperscaler debt issuance to nearly double to around $400 billion (Jeff Pu estimates $419 billion) as companies finance over a third of their infrastructure needs.
- Aggregate Capex: Combined capital expenditures are expected to hit roughly $940 billion in 2026 and scale past $1.3 trillion in 2027.
- Market Share: Hyperscaler investment-grade bond sales have jumped from roughly 2% of total US supply (2022–2024) to roughly 9% in 2026.
- Credit Impact: Credit spreads on a 10-year hyperscaler credit basket have widened from historical 40–75bp ranges toward 90bp+, driven by leverage concerns.
- Cash Flow Outlook: S&P Global Ratings expects all major hyperscalers to run negative free operating cash flow through 2026 and 2027, with a cash-flow inflection point not projected until 2028–2029.
Hyperscaler Funding Boom: Debt vs. Capex Projections (2026–2027):
Source: Google Gemini
……………………………………………………………………………………………………………………………………………………………………………………………………………………………………
Corporate Borrowing Negatively Impacted by AI Debt Financing:
Corporate bonds face the most direct effect. When hyperscalers, data-center operators, chip suppliers and utilities all enter the fixed income market at once, they compete for investor capital and dealer balance sheets.
The bond market adjusts through the following mechanisms:
- Larger new-issue concessions, meaning issuers must offer higher yields than comparable bonds already trading.
- Lower prices for outstanding corporate bonds as investors sell them to make room for new issues.
- Wider credit spreads, particularly for lower-rated investment-grade borrowers.
- Higher borrowing costs for non-AI companies that must compete with AI-linked supply for investor allocations.
The pressure is not limited to companies directly building AI agents or systems. A telecom operator, industrial firm, REIT or consumer company will likely pay more to borrow because investors can buy a new, liquid, highly rated hyperscaler bond at a potentially higher and attractive yield. That discourages non-AI corporate borrowing and leads to slower economic growth.
………………………………………………………………………………………………………………………………………………………………………………………………
AI Pain Points Personified:
1. Ares reports, “We documented well more than 100 digital-infrastructure financings from just the past twelve months… Despite different issuers, different structures, different rating agencies and different credit markets, all of the risk converges on just eight (AI tech) names: Meta, Oracle, Microsoft, Amazon, Google, Nvidia, and, on a look-through basis, OpenAI and Anthropic.”
2. Analysts at Goldman Sachs Group and elsewhere have calculated that more than $1 trillion has already been spent on the data center build-out since the launch of ChatGPT in late 2022. Presumably, other large American businesses would need to pay for AI tools to justify all of this investment. That money needs to come from somewhere. but who’s going to pay for those AI tools?
3. From Greg Ip of the WSJ: “Will America Spend 9% of Its GDP on AI? The Industry Is Counting on It“:
“Is it plausible that Americans will spend as much of their income on this one technology as they do on food? Roughly twice what the nation pays for all forms of energy or all computers and software? Seven times what consumers spend on phone, streaming, and internet services combined?”
“You should be skeptical. Even the most transformative inventions eventually run into the law of diminishing returns: each additional dollar a user spends yields less additional productivity (or enjoyment) than the last. That imposes a natural ceiling. The question, of course, is where that ceiling is. Whether or not you think 9% of GDP is right, you have to care, because this figure isn’t some fever dream: it is implicit in the dollars that investors and companies are committing right now.”
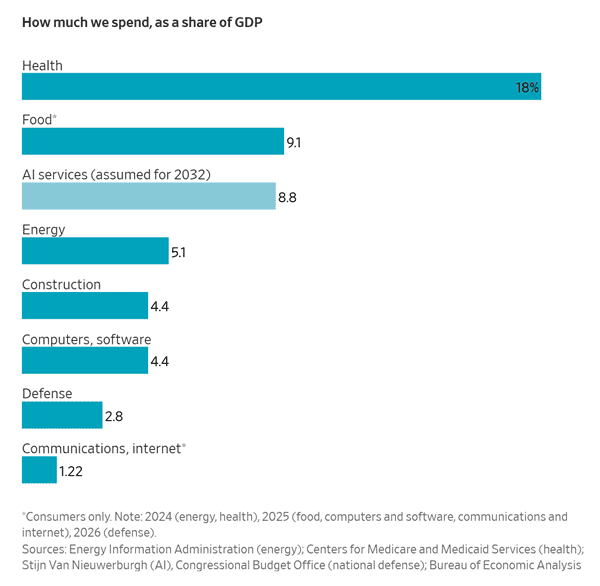
Chart Credit: Greg Ip, Wall Street Journal
………………………………………………………………………………………………………………..
Dire Warnings:
Nobel laureate Daron Acemoglu writes about “Distorted Intelligence at the AI Frontier” (emphasis added):
“The real problem for the frontier AI labs is not that their models are too powerful and already “misaligned” with the goals their creators set for them. Rather, it is that the models are being trained in ways that may be leading to a type of intelligence that will become less predictable. AI frontier labs are training their models in ways that may be leading to a type of distorted intelligence.
“This is what I mean by distorted intelligence. If my suspicion is correct, what we are dealing with is not a model racing toward superintelligence, but a brittle house of cards that becomes more and more likely to malfunction and collapse as we demand more from it.”
Conclusions:
The above analysis outlines critical structural risks and concerns directly related to the AI infrastructure (capex) spending boom. It references several articles which highlight the risks of circular financing loops where hardware suppliers (like Nvidia and Broadcom) fund their buyers (like Anthropic and Open AI). Additionally, hyperscalers face structural cash deficits with negative free operating cash flows projected through 2027, alongside rising sovereign risk and potential conflicts of interest from intertwined debt and leasing arrangements. This table balances the author’s views with a counter-perspective:
| IEEE Techblog Warning | The Nuanced Counter-Perspective |
|---|---|
| Circular Funding Risk: Massive vendor lending deals (like Broadcom lending Anthropic $42 billion) are artificially inflating revenue and building a brittle house of cards. | Balance Sheet Cushion: Unlike the 2000 Dot-Com crash where telecom infrastructure was built on speculative, junk-rated leverage, 2026 hyperscalers possess massive cash-generative core businesses (search, cloud, e-commerce) to subsidize their debt service even if AI returns are delayed. |
| Diminishing Returns: Society cannot plausibly spend 9% of GDP on AI, meaning demand will hit a hard ceiling and spark a debt bust. | Productivity Deflation: AI infrastructure spending may not need to justify itself through direct “software sales.” If the technology lowers the baseline operating costs of the global services economy, the ROI manifests as structural corporate margin expansion rather than retail sales. |
………………………………………………………………………………………………………………………………………………………………………………………………
References:
Curmudgeon: Caveat Emptor: Huge Debt and Circular Financing Deals Dominate AI Build-Outs (07/23)
Broadcom lending Anthropic up to $42 billion in yet another AI circular financing deal
Bain & Co: AI Infrastructure Buildout Will Require $6 Trillion Revenue by 2031 to Support Massive CAPEX
The AI Infrastructure Build-Out: A $10 Trillion Bet on Compute, Power, and Networks
Nvidia CEO Huang: AI is the largest infrastructure buildout in human history; AI Data Center CAPEX will generate new revenue streams for operators
AI risks and backlash increase; Recap of the circular loop of fake AI profits and hyperscaler markups of private AI companies
China vs U.S.: Race to Generate Power for AI Data Centers as Electricity Demand Soars
How will fiber and equipment vendors meet the increased demand for fiber optics in 2026 due to AI data center buildouts?
Expose: AI is more than a bubble; it’s a data center debt bomb
Will billions of dollars big tech is spending on Gen AI data centers produce a decent ROI?
Huge Risks for the proposed $500B AI Investments from Giant Wall Street firms
Can the debt fueling the new wave of AI infrastructure buildouts ever be repaid?
Light Counting: optical transceiver sales surge; IEEE 802.3 and ITU-T optical transport standards explained/UEC addendum
Sales of All Types of Optical Transceivers Set New Records:
Light Counting reports that the sales of optical transceivers, shown in the first figure below, illustrates the new record set in Q2 2026 and estimates for the rest of 2026. Sales of Ethernet transceivers currently account for about 80% of the total market. Shipments of “legacy products”—800G 2xDR4 and 2xFR4, as well as 400ZR/ZR+, were up sharply in Q2, by up to 3x year-over-year in terms of units, well ahead of the market research firm’s expectations. Unit shipments of 100G and 400G Ethernet transceivers also set new records. Even 10G Ethernet was up. Volume shipments of 1.6T Ethernet transceivers and 800ZR/ZR+ are off to a great start this year, but this was less surprising.
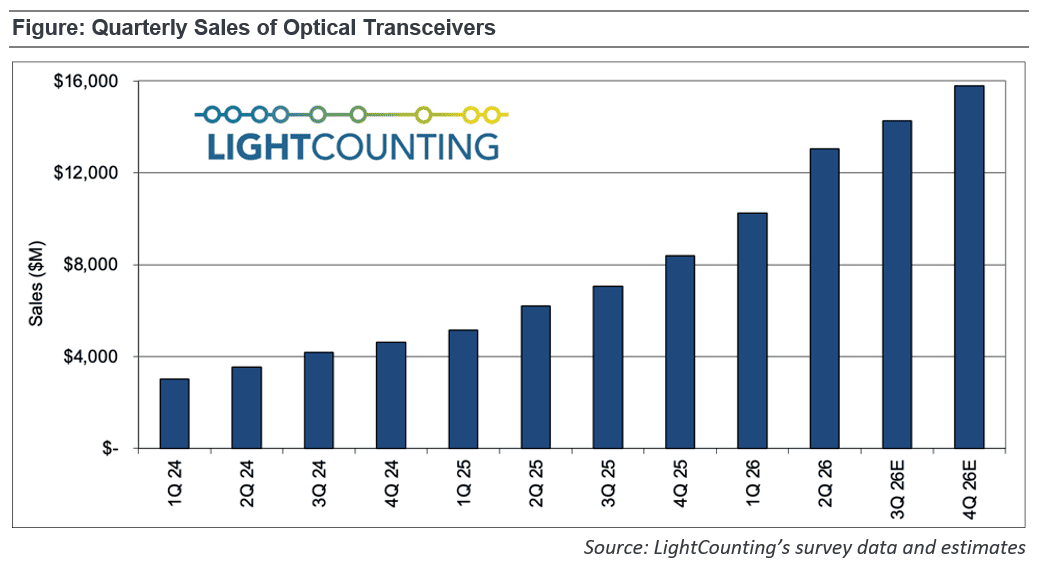
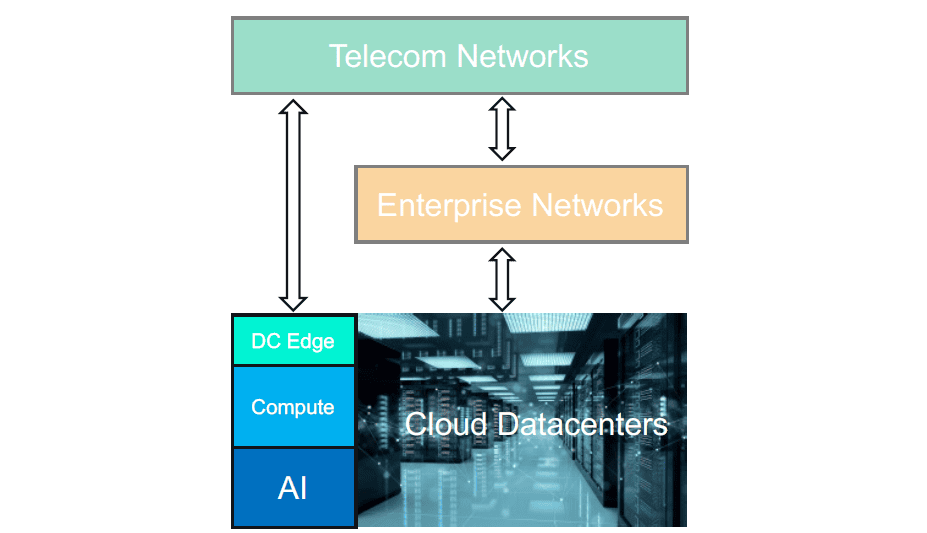
Image Credit: Light Counting
……………………………………………………………………………………………………………………………………………………………………………………………………………………………………………
Leading suppliers of optical transceivers reported record revenues and profits, despite component shortages. Here are Q2-2026 results for the top two suppliers:
- Innolight achieved a record revenue of $3.3 billion in Q2, up 192% year-over-year and up 16% sequentially. The company’s net income was $1.16 billion, up 249% year-over-year and up 40% sequentially. Gross margin increased this quarter, driven by sequential volume growth of 1.6T products.
- Eoptolink reported a record revenue of $1.8 billion in Q2, up 109% year-over-year and up 53% sequentially. The company’s net income was $698 million, up 113% year-over-year and up 74% quarter-over-quarter.
| Supplier | Estimated 2025 Sales / Segment Revenue | Market Context & Performance |
|---|---|---|
| InnoLight Technology | $5.3 Billion | Market Leader (#1); revenue surged 61% year-over-year driven by mass delivery of 800G and 1.6T modules. |
| Eoptolink | $3.5 Billion | Moved to #2 globally; registered an astonishing ~188% segment surge supplying 400G/800G optics to Amazon and Nvidia. |
| Coherent Corp. | ~$4.0 – $4.5 Billion (Data Center & Comm. Segment) | Coherent was overtaken by Eoptolink in pure transceiver rankings, but its broader communications segment generated massive revenues (including a record $1.2 Billion in Q4 2025 alone). |
| Cisco Systems | ~$1.5 – $2.0 Billion (Optical/Acacia) | Cisco captures a massive chunk of the telecom and coherent pluggable market through its internal networking sales and Acacia subsidiary. |
| Lumentum Holdings | ~$1.0 – $1.3 Billion | Reported record revenues and high double-digit growth by the end of 2025, heavily buoyed by their NeoPhotonics integration. |
| Broadcom | ~$800 Million – $1.1 Billion (Modules/Engines) | While Broadcom generates over $18B+ quarterly in overall networking/AI silicon, its specific optical transceiver and co-packaged optical engine sales represent a smaller, premium segment. |
| Accelink Technologies | ~$600 – $800 Million | Maintained a steady footprint setting new shipping records for Chinese domestic cloud providers and 5G operators. |
| Sumitomo Electric | ~$400 – $500 Million | Holds a reliable niche focused primarily on specialized telecom optical components and compact Japanese network infrastructure deployments. |
This demand is being driven primarily by AI data-center build-outs, where the scaling of accelerator clusters requires concurrent investment in compute, switching, optical interconnect, power, and cooling. Ethernet is increasingly central to scale-out fabrics and, in some architectures, to emerging scale-up designs.
The reported growth at leading suppliers illustrates how rapidly demand is propagating through the component supply chain. As note above, Innolight reported nearly 200% year-over-year growth in optical-transceiver sales during the first half of 2026. Such results are consistent with an industry that is simultaneously absorbing high volumes of 800G modules and preparing the supply chain for 1.6T transitions.
Optical Transceiver Standards:
The standards baseline spans both Ethernet and optical transport.
- For intra-data-center connectivity and some point-to-point data-center-interconnect applications, IEEE 802.3df-2024 standardized Ethernet MAC parameters for 800GbE, together with physical-layer and management specifications for 400GbE and 800GbE operation.
- IEEE P802.3dj is developing 200 Gb/s-per-lane electrical and optical interfaces for 200GbE, 400GbE, 800GbE, and 1.6TbE Ethernet operation.
- For carrier optical-transport and WDM applications, ITU-T G.709 defines the OTN digital transport hierarchy and interfaces; ITU-T G.959.1 specifies OTN physical-layer interface application codes; and ITU-T G.698.2 defines single-channel optical-interface parameters for amplified DWDM “black-link” applications.
- A carrier can transport an Ethernet PHY signal directly over a coherent wavelength. The clearest standardized example is OIF 400ZR, which carries a 400GBASE-R host signal transparently over a single coherent DWDM carrier. It is explicitly specified as a 400G BASE-R PHY interface, rather than as a full ITU-T G.709 OTUk line signal.
Optical Ethernet Standards and Product Transition:
The current optical upgrade cycle spans multiple Ethernet (IEEE 802.3) generations:
It is important to distinguish standardized Ethernet interface rates from the broader product roadmap of optical suppliers. IEEE 802.3df standardized 800 GbE, while IEEE P802.3dj addresses 1.6 TbE and the associated 200 Gb/s-per-lane physical-layer ecosystem. By contrast, 2.4T and 3.2T transceiver products may be relevant to future system architectures, but they should not be presented as ratified IEEE Ethernet rates at this stage. Please see the Addendum below for an explanation of he Ultra Ethernet Consortium.
ITU-T OTN and WDM Recommendations:
While IEEE 802.3 specifications define Ethernet MAC and PHY operation, they are not the only standards framework relevant to high-speed optical modules. In optical transport networks, ITU-T Recommendations define the digital transport structure, optical-channel parameters, WDM frequency plans, and interoperable line-side interface requirements. Optical transceivers must meet the requirements of the applicable interface standard (IEEE 802.3 or ITU-T) or implementation agreement for their intended deployment. For intra-data-center Ethernet links, this normally means IEEE 802.3 PHY specifications and applicable MSAs. For OTN, WDM, or carrier interdomain applications, the relevant requirements may additionally include ITU-T G.709, G.959.1, G.698.2, and G.694.1.
- ITU-T G.709 specifies the interfaces and digital hierarchy of the Optical Transport Network (OTN), including optical transport units and associated overhead, forward-error-correction, and multiplexing structures. An Ethernet client signal may therefore be mapped into an OTN container for transport across a metro, regional, long-haul, or subsea optical network.
- ITU-T G.959.1 specifies Optical Transport Network physical-layer interfaces, including interdomain interface requirements for single-channel and multichannel optical systems. Its application codes define parameters such as nominal bit rate, reach class, wavelength range, transmitter characteristics, receiver tolerance, and optical power budgets. The recommendation is intended to enable transverse, or multivendor, compatibility at optical interfaces crossing administrative-domain boundaries; it can also be used for intra-domain interfaces where appropriate. The current G.959.1 edition, issued in 2024 and subsequently amended, includes interfaces relevant to high-speed PAM4-based optical transport applications.
- ITU-T G.698.2 is also relevant where pluggable coherent or direct-detect modules connect into amplified DWDM systems. It specifies single-channel optical-interface parameters for amplified multichannel DWDM applications, using a “black-link” model that defines interoperability at the transmitter-side and receiver-side reference points while allowing the intervening photonic line system to remain implementation-specific. The recommendation addresses metro-oriented amplified DWDM applications and defines channel spacings based on the ITU-T G.694.1 frequency grid. Consequently, an optical transceiver used entirely within a hyperscale data-center Ethernet fabric will typically be specified primarily against IEEE 802.3 PHY requirements and relevant multi-source agreements.
In summary, a coherent pluggable used as a router-to-ROADM, router-to-transponder, or interdomain line-side interface may additionally need to comply with ITU-T OTN and DWDM interface requirements—particularly G.709, G.959.1, G.698.2, and the G.694.1 frequency-grid framework. Compliance depends on the intended application code and reference point, rather than on the module form factor alone.
Standards framing:
A concise way to explain the division of responsibility is as follows:
…………………………………………………………………………………………………………………………………………………………………………………………………………………………………………..
Cloud Capex is Through the Roof:
The magnitude of current cloud capital expenditure is exceptional and is the primary driver for the optical transport market. For example, Oracle, reported $28.5 billion in capital expenditures in its most recent quarter, up 235% year over year, against quarterly revenue of $19.3 billion, up 30%. This illustrates the extent to which an established enterprise-software supplier is being repositioned around AI infrastructure and cloud capacity. See References below for more examples of hyperscaler’s enormous capex.
Chinese hyperscalers are pursuing a similar, if less publicly transparent, investment pattern. Tencent’s capex surged 194% y-o-y in Q2, reaching $7.7 billion, up 68% sequentially. Alibaba’s capex was $9.9 billion for the quarter, up 86% year-over-year and up 156% compared to the previous quarter, used primarily to build AI compute infrastructure. Baidu’s capex for the quarter reached $1.67 billion, surging 219% year‑on‑year and 96% quarter‑on‑quarter. Alibaba and Tencent’s reported capital-expenditure percentage increases greatly exceed their revenue growth, which remained closer to the 15%–20% range. The widening gap between capital intensity and near-term revenue growth is a defining characteristic of the present AI infrastructure cycle.
Nvidia commented that it expects to see another 70% growth in capex of cloud companies for 2027—similar to the growth reported by the TOP 4 Cloud companies in 2026. Nvidia must know this well, since the company is engineering multiple financial projects to support the hyper growth.
Super-cycle, but not in a straight line:
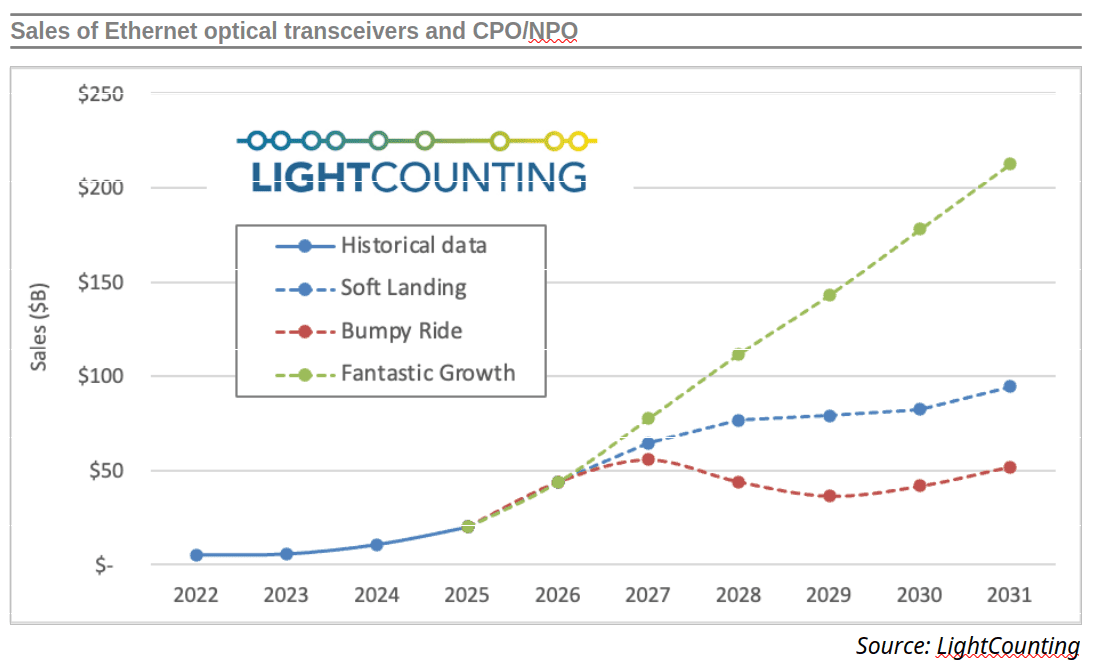
The market is clearly in an optical-interconnect supercycle. However, the present rate of expansion is unlikely to persist indefinitely. Even under a continued high-growth scenario, the forecast assumes that growth moderates from 120% in 2026 to 76% in 2027 and to approximately 20% by 2031.
The base-case forecast adopts a soft-landing assumption: cloud capital expenditure remains strong, but procurement normalizes as the supply chain expands, deployment schedules mature, and customers improve utilization of installed infrastructure. The forecast model assumes a 50% increase in cloud capital expenditure in 2027—below the roughly 70% growth contemplated by the most bullish industry forecasts.
That assumption is deliberately more conservative because optical-component supply chains historically respond aggressively to changes in customer procurement signals. Current conditions already show evidence of this effect: suppliers are expanding capacity and product portfolios rapidly in response to exceptional demand for high-speed pluggable optics.
Historical transceiver sales data from 2004 through 2025 also indicate that the sector is cyclical. Periods of two to three years of strong growth have frequently been followed by flat or declining years as inventory, manufacturing capacity, and end-market deployment plans return to balance. In that context, a soft landing is possible, but a more volatile bumpy-ride scenario—characterized by a supply-chain correction during 2027–2030—remains plausible.
Architecture matters:
The forecast also incorporates a structural counterweight to unit demand: optical-interconnect efficiency is improving. AI-cluster architectures are evolving in ways that can reduce the number of optical transceivers required per accelerator, even as total cluster bandwidth continues to rise.
Several developments are relevant:
-
TPU-based and other tightly integrated accelerator systems can reduce the optical-interconnect requirement per XPU relative to more externally networked cluster designs.
-
Multi-plane network topologies can improve path diversity and bisection bandwidth while reducing the need for redundant interconnect resources in certain deployments.
-
Higher-radix switch silicon enables flatter fabrics, reducing the number of network tiers, hop count, and associated optical interfaces.
-
The transition from 100 Gb/s-per-lane to 200 Gb/s-per-lane signaling—under development in IEEE P802.3dj—raises port density and system bandwidth, but also changes the optics-per-bandwidth relationship.
Accordingly, the relevant demand metric is not simply accelerator count. It is the interaction among accelerator architecture, scale-up versus scale-out topology, switch radix, oversubscription design, optical reach, packaging approach, and the extent to which the deployment uses pluggable optics, linear-drive optics, linear-receive optics, co-packaged optics, or near-packaged optics.
Light Counting Report Scope:
The report covers more than 100 Ethernet optical-interconnect product categories, including:
-
100G, 200G, 400G, 800G, 1.6T, 2.4T, and 3.2T retimed transceivers.
-
Linear pluggable optics and linear-drive/linear-receive optical architectures, including LPO and LRO.
-
Co-packaged optics and near-packaged optics, including CPO and NPO.
-
Products segmented by reach, interface technology, and application.
The market analysis is segmented by end customer into cloud, telecommunications, and enterprise markets. The cloud segment is further divided by customer group—top-five U.S. cloud providers, top-five Chinese cloud providers, and other cloud operators—and by application: conventional cloud and front-end networking, AI scale-out networks, and AI scale-up networks.
Conclusions:
The Ethernet optical transceiver market is benefiting from an AI-driven infrastructure build-out that is materially stronger than expected only six months ago. Yet the same intensity that creates the 2026 upside also increases the risk of a later inventory, capacity, or capital-expenditure correction. The key analytical question for 2027–2031 is no longer whether the market will grow; it is whether the industry can transition from extraordinary demand acceleration to a sustainable deployment cadence without repeating the supply-chain overshoots that have characterized prior optical-networking cycles.
Addendum – The Ultra Ethernet Consortium (UEC):
The UEC is separate from IEEE 802.3, but its work is deliberately built on—and coordinated with—the IEEE Ethernet PHY and MAC ecosystem. UEC is not an IEEE 802.3 task force and does not itself ratify IEEE 802.3 amendments. Instead, it publishes an Ethernet-based AI/HPC networking specification across multiple layers and works with relevant standards-development organizations where changes or formal standardization are needed. UEC uses and extends Ethernet, rather than that UEC defines a separate Ethernet PHY.
Division of responsibility:
How UEC relates to IEEE 802.3:
UEC’s stated premise is an Ethernet-based, open, interoperable stack for AI and HPC. Its work is designed to retain compatibility with the broad Ethernet ecosystem while optimizing behavior above—and in selected optional cases at—the PHY/link boundary. It does not replace IEEE 802.3-defined Ethernet port rates or optical PMDs.ultraethernet+1
That means:
-
IEEE 802.3df supplies the standardized 800GbE Ethernet MAC/PHY foundation.
-
IEEE P802.3dj is developing 200 Gb/s-per-lane electrical and optical interfaces for 200GbE through 1.6TbE operation.
-
UEC defines how AI/HPC systems can use such Ethernet links more effectively: particularly host-to-network interaction, RDMA-oriented transport, congestion control, traffic distribution, reliability behavior, and large-scale fabric operation.ieee802+2
UEC Specification 1.0 was released in June 2025, with Version 1.0.2 published in January 2026. UEC describes the result as a full communications stack, with scope extending from applications and transport through switching, link behavior, optics/cables integration, management, and security. UEC 1.0 is designed to operate with Ethernet-compatible physical-layer technology. It contemplates 100 Gb/s-per-lane and 200 Gb/s-per-lane signaling, which aligns naturally with the industry transitions covered by IEEE 802.3df and P802.3dj. However, UEC does define optional Ethernet PHY and link-layer features, so it is not accurate to say that it has no Layer 1 or Layer 2 relevance whatsoever.
……………………………………………………………………………………………………………………………………………………………………………………………………………..
References:
https://www.lightcounting.com/newsletter/en/september-2026-quarterly-market-update-371
https://www.lightcounting.com/report/september-2026-ethernet-optics-372
Dell’Oro: Data Center capex grew 92% in 2Q-2026 (caveats galore)
Hyperscaler capex > $600 bn in 2026 a 36% increase over 2025 while global spending on cloud infrastructure services skyrockets
Dell’Oro: 2H2026 Data Center Capex to Accelerate due to massive AI Deployments
Alphabet’s 2026 capex forecast soars; Gemini 3 AI model is a huge success
Bain & Co: AI Infrastructure Buildout Will Require $6 Trillion Revenue by 2031 to Support Massive CAPEX
Impact of optical component shortages & bottlenecks explained + Hyperscaler’s CAPEX
Hyperscaler AI Race: Soaring Capex Wipes Out Free Cash Flow; AGI and Digital Gods
How will fiber and equipment vendors meet the increased demand for fiber optics in 2026 due to AI data center buildouts?
China’s 2030 ICT Plan focus: 50G-PON, AI Traffic and Satellite–Terrestrial Networks
Executive Summary:
China’s Ministry of Industry and Information Technology (MIIT) has issued its 15th Five-Year Plan for the Development of the Information and Communication Industry, setting a 2030 target for a next-generation communications infrastructure with nationwide coverage, high performance, and a foundation for the sector’s broader modernization by 2035.
The plan sets several quantitative goals for 2030:
-
Information and communications industry revenue of RMB 4.1 trillion.
-
Deployment of 50 5G/5G-Advanced base stations per 10,000 people.
-
95% penetration of 5G/5G-Advanced users.
-
320 million fixed-broadband subscribers with access rates of at least 1 Gbit/s.
-
Intelligent-computing capacity of 9,800 EFLOPS.
- Digital economy: Core industries aim to reach 12.5% of GDP by 2030.
- Networks: Build next-generation communications with full coverage and leading performance.
- Security: Enhance domain coordination and practical network/data security.
The strategy also emphasizes tighter satellite–terrestrial integration. MIIT calls for coordinated construction of satellite–terrestrial interconnection centers and development of direct-to-device satellite services and satellite IoT applications. It further identifies 6G base stations and terminals as development priorities, alongside stronger standards frameworks for optical communications, computing networks, and quantum communications.
China’s 50G-PON push:
The plan’s broader infrastructure objectives reinforce China’s interest in 50G-PON as a successor to today’s 10G-class PON deployments. ITU-T G.9804 defines 50G-PON as a higher-speed passive optical network supporting 50 Gbit/s downstream capacity and at least 12.5 Gbit/s upstream capacity. The technology is intended to extend fiber-access performance for residential, enterprise, cloud, industrial, and mobile-network backhaul use cases.
While operators and equipment suppliers in most markets remain in early trial and evaluation phases, China has accumulated practical deployment experience through 136 10 Gbit/s network pilots conducted last year. Those trials evaluated 50G-PON ultra-broadband access, fiber-to-the-room (FTTR) integrated with Wi-Fi 7, and optical-AI integration, as well as cloud-computing and cloud-gaming applications.
At the China International Optoelectronic Expo in Shenzhen, industry participants argued that China’s supply chain is technically positioned for larger-scale 50G-PON deployment. The remaining constraints are primarily economic and operational: system cost, terminal economics, and power consumption remain material barriers to broad commercial rollout.
AI changes the access-network equation:
Unlike several earlier optical-access upgrade cycles, 50G-PON is being positioned against a more immediate traffic and workload driver: AI. Zhang Dechao, deputy head of basic-network research at the China Mobile Research Institute, said token-based AI workloads are reshaping optical-network traffic patterns, particularly by increasing upstream and more symmetric bandwidth requirements.
Historically, consumer broadband traffic was strongly downstream-weighted. AI inference, distributed data processing, edge-cloud interaction, enterprise collaboration, and high-resolution interactive applications are changing that profile. Zhang said uplink traffic now represents roughly 40% to 50% of total traffic in some network scenarios, making symmetrical bandwidth an increasingly important design requirement. He also cited projections that AI inference could account for 25% of total network traffic by 2035 and contribute to more than 63% growth in aggregate traffic demand.
That shift matters for PON evolution. A network designed primarily for high downstream residential consumption is not necessarily optimized for AI-era workloads that require sustained upstream capacity, lower latency, more predictable performance, and closer integration between access, edge, cloud, and data-center infrastructure.
Supply-chain conflict:
AI is also creating an uncomfortable contradiction for the optical-access sector. The same AI investment cycle that is expanding demand for higher-capacity access and transport networks is redirecting capital, component capacity, and engineering resources toward AI data centers, high-speed Ethernet optics, accelerator interconnects, and cloud infrastructure.
Lin Tao, marketing director at component supplier Accelink Technologies, warned that this concentration of investment could constrain PON-specific R&D and production capacity. Suppliers may find higher near-term returns in AI-related optical modules and interconnect products than in access-network components, particularly where 50G-PON volumes remain uncertain.
The implication is straightforward: technical readiness alone will not determine the timing of 50G-PON deployment. Operators must establish sufficiently compelling service, enterprise, mobile backhaul, and AI-connectivity business cases to justify investment amid competition for optical components, manufacturing capacity, and capex.
Chinese optical suppliers nevertheless contend that core 50G-PON technology—including ASICs, optical modules, and devices—has reached maturity. Large-scale shipments of standardized customer-premises terminals are expected to begin next year, potentially marking the transition from pilots to broader commercial deployment.
References:
http://finance.people.com.cn/n1/2026/0909/c1004-40794989.html
https://www.lightreading.com/optical-networking/china-targets-1m-50g-pon-ports-by-2030
China Mobile and Huawei Turn High-Speed Railway 5G-A into a Premium Service
Key take-aways: “16th Smart City and Intelligent Economy Expo” for Huawei, Alibaba & China’s three state backed carriers
China vs U.S.: Race to Generate Power for AI Data Centers as Electricity Demand Soars
Analysis & Economic Implications of AI adoption in China
China’s telecom industry rapid growth in 2025 eludes Nokia and Ericsson as sales collapse
China’s open source AI models to capture a larger share of 2026 global AI market
China ITU filing to put ~200K satellites in low earth orbit while FCC authorizes 7.5K additional Starlink LEO satellites
China gaining on U.S. in AI technology arms race- silicon, models and research
Broadcom lending Anthropic up to $42 billion in yet another AI circular financing deal
Backgrounder:
According to Reuters, which obtained Anthropic’s IPO prospectus, the Big Tech giants are depicted in multiple ways in the IPO filing- as distribution partners, financial backers, computer suppliers, and competitors, all at once. They uncovered the clearest view yet of how circular the AI world really is, and how much an AI lab’s success depends on the giants it’s also competing against.
Reuters was able to calculate that Anthropic pays roughly 16% of every dollar it earns from its cloud partners (Amazon, Google, Microsoft) back to those same big tech partners. It counts the full value of contracts sold through a cloud marketplace as revenue, then treats the cloud platform’s cut of revenue as a marketing cost.
OpenAI does the opposite by only counting what it keeps after the cloud partner takes its share. That difference matters for understanding the big numbers floating around, and how to actually compare the two rivals’ toplines as they both eye the public market.
Broadcom’s relationship with Anthropic spans compute supply, equipment leasing and financing — giving the semiconductor company a central role in Anthropic’s infrastructure buildout. That differentiates it from other major partners and investors such as Amazon which primarily provide cloud infrastructure and distribution for Anthropic’s AI model Claude.
As part of that complex relationship, revealed in the IPO filing, Broadcom has agreed to lend Anthropic up to $42 billion to finance infrastructure spending. In turn, Anthropic stands to become the largest customer in Broadcom’s entire chip design business next year, making their relationship a prime example of the reciprocal spending that has animated AI skeptics on Wall Street, even as the AI lab readies a public offering that could see it valued at $2 trillion.
“It feels that there’s quite a concentrated bet right now on two companies being able to generate enough revenues to support all the financing that’s happened,” said Robert Leitao, managing partner of Rothschild & Co.
Anthropic disclosed that Broadcom’s role in supplying hardware and acting as a financing partner creates “potential conflicts of interest” that might affect Anthropic’s ability to access the computing power needed for its work, according to the prospectus.
The AI lab also warned that Broadcom’s decisions around pricing and hardware could affect its ability to procure enough computing infrastructure. Broadcom did not comment. Anthropic declined to comment to Reuters.
In April, Anthropic announced it was teaming up with Broadcom and Google for a deal that would see Google provide its Tensor Processing Unit (TPU) chip capacity to Anthropic, with the supply coming online in 2027. Broadcom designs Google’s TPUs that are manufactured by TSMC in Taiwan.

A Broadcom circuit board for chip testing is pictured during a lab tour as Broadcom prepares to launch new optical chip tech to fend off Nvidia in San Jose, California, U.S., September 5, 2025. Brittany Hosea-Small · REUTERS via Yahoo Finance.
Anthropic is also relying on Broadcom for equipment leasing and financing. Broadcom could designate a financing partner, and the debt instruments could be converted into Anthropic shares. Anthropic said in its filing it doesn’t expect any notes to be sold before it completes its IPO. The convertible note Anthropic would issue could finance about a third of the $125.2 billion commitment the AI lab has made for a five-year lease of tensor processing unit (TPU) computing capacity.
Other Players:
Broadcom rivals Nvidia and AMD have also provided funding to their own customers, including OpenAI and Anthropic, which the labs then used to pay for access to the companies’ high-powered chips. The concern about such circular financial schemes is that if one domino in the row falls, it will cause a chain reaction that will decimate the AI trade and, as a result, the global equities markets that have benefited from and come to rely on AI firms and hyperscalers.
As to the circularity of all of this financing, the BIS notes (via FT Alphaville):
“… circular relationships make reported demand partly endogenous to firms’ own financing decisions. For example, when a supplier finances a customer, part of the supplier’s revenue growth reflects its own capital investment, rather than organic final demand. This makes it harder for investors, lenders and supervisors to gauge what part of the current AI boom is based on organic demand.”
“The parallel with the telecom boom of the late 1990s is instructive: upstream equipment vendors financed network operators so they could buy the vendors’ equipment. This meant that part of the equipment vendors’ reported sales was being funded by the vendors themselves. For a time, as operators expanded their networks, equipment orders also expanded and vendors booked both the sales and loans as assets. However, when operators’ own revenues failed to materialize or slowed, they could neither repay the loans nor sustain the equipment purchases. Equipment vendors then sustained both financial losses and a loss of sales. Such dynamics may also play out in AI if revenue growth and end user demand fall short of firms’ expectations.”
……………………………………………………………………………………………………………………………………………………………………………………………..
- 2026 Debt Issuance: Projected between $220 billion and $250+ billion for major US hyperscalers (Alphabet / Google, Amazon, Meta, Microsoft, and Oracle), with broader AI-related market debt reaching up to $570 billion.
- 2027 Forecast: Goldman Sachs projects direct hyperscaler debt issuance to nearly double to around $400 billion (Jeff Pu estimates $419 billion) as companies finance over a third of their infrastructure needs.
- Aggregate Capex: Combined capital expenditures are expected to hit roughly $940 billion in 2026 and scale past $1.3 trillion in 2027.
- Market Share: Hyperscaler investment-grade bond sales have jumped from roughly 2% of total US supply (2022–2024) to roughly 9% in 2026.
- Credit Impact: Credit spreads on a 10-year hyperscaler credit basket have widened from historical 40–75bp ranges toward 90bp+, driven by leverage concerns.
- Cash Flow Outlook: S&P Global Ratings expects all major hyperscalers to run negative free operating cash flow through 2026 and 2027, with a cash-flow inflection point not projected until 2028–2029.
Source: Google Gemini
…………………………………………………………………………………………………………………………………………………………
References:
https://www.ft.com/content/87875b20-4081-4511-9afe-4ee389409742
Curmudgeon: Caveat Emptor: Huge Debt and Circular Financing Deals Dominate AI Build-Outs (07/23)
Bain & Co: AI Infrastructure Buildout Will Require $6 Trillion Revenue by 2031 to Support Massive CAPEX
The AI Infrastructure Build-Out: A $10 Trillion Bet on Compute, Power, and Networks
Nvidia CEO Huang: AI is the largest infrastructure buildout in human history; AI Data Center CAPEX will generate new revenue streams for operators
AI risks and backlash increase; Recap of the circular loop of fake AI profits and hyperscaler markups of private AI companies
China vs U.S.: Race to Generate Power for AI Data Centers as Electricity Demand Soars
How will fiber and equipment vendors meet the increased demand for fiber optics in 2026 due to AI data center buildouts?
Expose: AI is more than a bubble; it’s a data center debt bomb
Will billions of dollars big tech is spending on Gen AI data centers produce a decent ROI?
Huge Risks for the proposed $500B AI Investments from Giant Wall Street firms
Can the debt fueling the new wave of AI infrastructure buildouts ever be repaid?