RAN
Dell’Oro: Private Wireless Revenue Growth Prospects and Challenges
Executive Summary:
Dell’Oro Group just published its 2Q26 Private Wireless Report [1.]. The latest findings support the premise that the momentum is slowing, particularly in the enterprise campus segment, prompting another downward revision to their forecast.
Note 1. Dell’Oro Group explicitly measures Private Wireless RAN revenue. I believe they are referring ONLY to the cellular RAN equipment market, rather than a Wi-Fi LAN or conventional WAN market. However, private cellular deployments may coexist with Wi-Fi, and the RAN revenue measure should not be presented as total private-network spending.
“Private wireless continues to grow, but the market is developing more slowly than initially anticipated,” said Stefan Pongratz, Vice President at the Dell’Oro Group. “The divergence between campus and wide-area deployments is becoming more pronounced. While enterprise adoption remains gradual, demand for larger and more demanding wide-area networks is providing an important source of growth. We remain optimistic about the broader long-term private 5G/6G opportunity, though the adoption curve is clearly more gradual than initially expected.”
Private Wireless RAN revenue increased at a mid-single-digit rate in 1H26, down from the double-digit growth recorded in 2025. The slowdown is more pronounced in the Campus Network segment. Meanwhile, Wide-Area private wireless grew at a double-digit rate, reflecting stronger momentum in larger, mission-critical networks.
Supplier concentration remains high. Huawei continues to lead globally, while Nokia and Ericsson dominate outside China. The top five suppliers accounted for approximately 95% of Private Wireless RAN revenue in the first half of 2026. Despite slowing growth and downward forecast revisions, private wireless remains one of the stronger growth opportunities within the broader RAN market, which is expected to remain relatively flat. Private Wireless RAN revenue is projected to grow at a 10 to 13 percent CAGR over the next five years [2.].
Note 2. The 10–13% CAGR is a forecast, not an observed growth rate. The reported mid-single-digit growth in 1H2026 indicates near-term deceleration, while the latest forecast revision signals that the adoption trajectory remains less favorable than previously expected.

Dell’Oro’s message has not changed. Private wireless remains a largely untapped growth opportunity, but broader adoption is proving slower and more challenging than expected. The opportunity is increasingly shifting toward larger, wide-area and mission-critical deployments, while the enterprise campus segment continues to face headwinds. Private wireless network revenues are expected to account for 5 to 10% of total RAN revenues by 2030.
Analysis- Private Cellular Growth Prospects and Adoption Barriers:
Dell’Oro’s findings highlight an important distinction between the growth of private cellular RAN equipment revenue and the broader adoption of private wireless networking. The projected 10–13% CAGR over five years is attractive relative to a largely flat overall RAN market, but it starts from a comparatively small revenue base and follows another downward forecast revision. A double-digit growth rate therefore does not, by itself, establish that private wireless will become a major RAN revenue contributor.
Several factors help explain the slower-than-expected enterprise campus adoption. Private LTE/5G networks must compete with mature, less expensive Wi-Fi solutions that already meet many enterprise connectivity requirements. Additional obstacles include deployment and integration costs, spectrum availability, a limited ecosystem of compatible industrial devices, and the expertise required to operate cellular networks. Private 5G is most compelling where coverage, mobility, reliability, security, or predictable performance justify the additional investment.
The relative strength of wide-area deployments is consistent with the requirements of utilities, transportation systems, public safety, ports, mines, and other geographically extensive or mission-critical operations. These applications can justify dedicated cellular infrastructure where conventional Wi-Fi is impractical or insufficient.
The key question is whether private cellular can move beyond specialized industrial and mission-critical applications into repeatable, economically attractive enterprise deployments. Simpler turnkey solutions, lower total cost of ownership, and stronger integration with existing IT and operational technology networks will be important to expanding the addressable market. For RAN suppliers, private wireless represents a credible growth opportunity, but its commercial scale and timing remain uncertain.
References:
Private Wireless RAN Growth Slows to Mid-Single Digits in 1H26, According to Dell’Oro Group
Private 5G’s Business Model Shifts: Ericsson’s Move Signals a Market Reset
Nokia’s ECE Divestiture: Impact on Private 5G Market & Disaggregation
Dell’Oro: 6G RAN Capex to reach $500 billion by 2034 + Counterpoint
SNS Telecom & IT: Private 5G for the Defense Sector to hit $2.5 Billion by 2029
5G infrastructure moves from coverage and speeds to cloud-native, orchestration, automation and AI-assisted networks
SNS Telecom & IT: Private 5G Market to Reach $6.6 Billion as Physical AI Takes Hold
GSA: Global private mobile networks exceed 2,000 worldwide; Ericsson Private 5G from Verizon Business extends beyond U.S.
SNS Telecom & IT: Mission-Critical Networks a $9.2 Billion Market
Dell’Oro: Fixed Wireless Access revenues +10% in 2025 & will continue to grow 10% annually through 2029
Dell’Oro: RAN revenue growth in 1Q2025; AI RAN is a conundrum
Dell’Oro: Global RAN Market to Drop 21% between 2021 and 2029
Ericsson leads SK Telecom AI RAN vs. NVIDIA’s GPU centric AI RAN Alliance
AT&T/Ericsson Demonstrate 5G-Based ISAC for Drone Detection at World Cup Stadium
AI-RAN and Agentic AI get real: Ericsson, Nokia, Verizon & other operators enter into a new network automation era
Analysis: Ericsson’s leading role in French INTENTION 6G project
Ericsson’s June 2026 Mobility Report Highlights + AI impact on network traffic
SNS Telecom & IT report on RAN Automation: Opportunities, Challenges, Strategies and Forecasts
by James Bennett with Alan J Weissberger
Introduction:
SNS Telecom & IT has just published their 648 page 2026 RAN Automation report. The report presents an in-depth assessment of the RAN automation market, including the value chain, market drivers, barriers to uptake, enabling technologies, functional areas, use cases, key trends, future roadmap, standardization, case studies, ecosystem player profiles and strategies. The report also provides global and regional market size forecasts for RAN and end-to-end mobile network automation from 2026 to 2040. The forecasts cover three network domains, nine functional areas, three access technology generations, 12 use case categories, three network types, two supplier categories and five regional markets.
Automation of the RAN (Radio Access Network):
The RAN is the most expensive, technically complex and power-intensive part of cellular infrastructure – is a key aspect of mobile operators’ AN (Autonomous Network) journeys towards L4 (Highly Autonomous) and eventually L5 (Fully Autonomous) operations. In conjunction with AI (Artificial Intelligence) and ML (Machine Learning), RAN automation has the potential to significantly transform mobile network economics by reducing the OpEx (Operating Expenditure)-to-revenue ratio, minimizing energy consumption, lowering CO2 (Carbon Dioxide) emissions, deferring avoidable CapEx (Capital Expenditure), optimizing performance, improving user experience and enabling new services.
Rakuten Mobile, China Mobile, STC (Saudi Telecom Company), TDC NET and several other operators have already achieved a limited level of L4 autonomy for specific use cases in their live RAN operations. The proven, quantifiable benefits of this level of intent-driven, closed-loop RAN automation range from 20% energy savings without compromising customer experience to a reduction of up to 60% in cell outages during major events such as the annual Hajj pilgrimage. Beyond terrestrial public mobile networks, RAN automation is also gaining traction in other segments of the cellular industry, supporting applications ranging from NTN (Non-Terrestrial Network) resource orchestration and terrestrial-satellite interworking to agentic AI-enabled private 5G network management, adaptive power control in offshore cellular deployments, ISAC (Integrated Sensing & Communications) for counter-drone operations and emission control for tactical 5G networks.
The RAN automation market traces its origins to the early 2010s when SON (Self-Organizing Network) technology – in the form of both embedded D-SON (Distributed SON) and C-SON (Centralized SON) implementations – was introduced to reduce cellular network complexity through self-configuration, self-optimization and self-healing. The pursuit of higher levels of autonomy, coupled with the multi-vendor interoperability, scalability and latency-related limitations of legacy SON solutions, is accelerating the transition to Open RAN automation with standards-based components that enable greater levels of RAN programmability and automation. These include the Near-RT (Real-Time) and Non-RT RICs (RAN Intelligent Controllers), SMO (Service Management & Orchestration) framework, rApps (RAN Applications), xApps (Extended Applications) and dApps (Distributed Applications).
…………………………………………………………………………………………………………………………………………………………..
| Term | Description |
| AN | Autonomous Network |
| AI | Artificial Intelligence |
| ML | Machine Learning |
| AI-RAN | Artificial Intelligence – Radio Access Network |
| RAN | Radio Access Network |
| OpEx | Operating Expenditure |
| CapEx | Capital Expenditure |
| CO2 | Carbon Dioxide |
| NTN | Non-Terrestrial Network |
| ISAC | Integrated Sensing & Communications |
| SON | Self-Organizing Network |
| D-SON | Distributed SON |
| C-SON | Centralized SON |
| RIC | RAN Intelligent Controller |
| Near-RT RIC | Near-Real-Time RAN Intelligent Controller |
| Non-RT RIC | Non-Real-Time RAN Intelligent Controller |
| SMO | Service Management & Orchestration |
| rApps | RAN Applications |
| xApps | Extended Applications |
| dApps | Distributed Applications |
| RU | Radio Unit |
| DU | Distributed Unit |
| CU | Centralized Unit |
| E3 | Edge-Enhanced Exposure Interface |
| RF | Radio Frequency |
| GPU | Graphics Processing Unit |
| M&A | Mergers & Acquisitions |
Discussion:
Centrally coordinated rApps hosted on the SMO and Non-RT RIC layer have emerged as the preferred approach to multi-vendor RAN automation on a network-wide basis, especially as hybrid and Open RAN architectures become increasingly common in new RAN swap and rollout contracts. Additionally, SMO platforms are being positioned as a common foundation for cross-domain network autonomy that links observability, intelligence, intent management and closed-loop automation. From Swedish wireless giant Ericsson to Spanish private 5G orchestration specialist Neutroon, multiple SMO providers have already incorporated core network interfaces for end-to-end management and automation.
SMO/Non-RT RIC adoption is beginning to accelerate among brownfield operators – including but not limited to AT&T, Verizon, Telus, Vodafone, DT (Deutsche Telekom), Swisscom, STC, NTT DoCoMo, Chunghwa Telecom and Telstra – to enable network-wide automation across thousands of cell sites through RAN vendor-supplied, third-party and internally developed rApps. This follows greenfield operator Rakuten Mobile’s nationwide RIC deployment, along with in-house and third-party rApp integration, across its Open RAN-compliant footprint of 350,000 cells supplied by 10 distinct RU (Radio Unit) and DU/CU (Distributed and Centralized Unit) vendors.
While reluctance among DU/CU vendors has held back adoption of xApps and the Near-RT RIC, there is growing interest in the recently proposed E3 (Edge‑Enhanced Exposure) interface, which provides a standardized mechanism for dApps to directly interface with Open RAN baseband nodes for closed-loop control beyond the 10-millisecond latency limits of xApps, including lower-layer performance optimization, geolocation, integrated sensing, spectrum sharing and interference cancellation in 5G and future 6G deployments. RAN vendors and application developers – such as Nokia, NVIDIA, Radisys, IS-Wireless, Cohere Technologies, DeepSig, ISCO International, Unikie, Booz Allen Hamilton and ODC (ORAN Development Company) – have already committed to support the E3 interface. An alternative to dApps being pursued by some vendors is to offer proprietary AI-enabled, real-time optimization capabilities as software upgrades to existing RAN platforms through subscription-based licensing models. For example, Ericsson has recently launched a software subscription offering for service providers that embeds AI/ML models directly into RAN basebands and radios to improve performance and efficiency through microsecond-level inference for use cases such as scheduling, link adaptation, beamforming and multi-layer coordination.
Commonly referred to as AI-for-RAN, the deeper integration of AI, ML and their derivatives for RAN automation and optimization is the most commercially mature facet of the broader AI-RAN movement, which also encompasses AI-and-RAN – the co-hosting of RAN and external AI workloads on shared, GPU-accelerated infrastructure; and AI-on-RAN – the enablement of edge AI services for mobile subscribers. The launch of the first 6G networks – which are being standardized as AI-native systems from the outset – around 2030 is expected to significantly increase the scope for hardware-agnostic, software-led innovation and take the industry closer to fully autonomous network operations. RAN digital twins are also expected to play an increasingly important role, allowing operators to validate AI-enabled air interface features and train optimization algorithms in high-fidelity virtual environments before introducing them into live 6G networks.
- Largely driven by growing investments in both centrally coordinated SMO/RIC-enabled automation at the network level and AI-for-RAN software upgrades for embedded real-time intelligence and the replacement of static rule-based algorithms in RAN nodes, annual spending on AI-RAN automation and optimization software and services is expected to grow at a CAGR of 9% over the next four years, eventually reaching $1.1 billion by the end of 2030.
- Total spending on the wider RAN automation market – which includes traditional SON/proprietary network-level automation, AI-for-RAN upgrades, Open RAN SMO/RIC and d/x/rApps, RF planning tools and automated test/measurement solutions – is expected to grow at a CAGR of approximately 4% during the same period.
Progress Towards L4 RAN Operations & Quantifiable Benefits
- Mobile operators are making tangible progress towards L4 RAN operations as they work towards the longer-term goal of L5 networks. Rakuten Mobile, China Mobile, STC, TDC NET and several other operators have already achieved a limited level of L4 autonomy for specific use cases in their live networks. The proven, quantifiable benefits of this level of intent-driven, closed-loop RAN automation range from 20% energy savings without compromising customer experience to a reduction of up to 60% in cell outages during major events such as the annual Hajj pilgrimage.
- The pursuit of higher levels of autonomy, coupled with the multi-vendor interoperability, scalability and latency-related limitations of legacy SON solutions, is accelerating the transition to Open RAN automation with standards-based components that enable greater levels of RAN programmability and automation.
- In particular, centrally coordinated rApps hosted on the SMO and Non-RT RIC layer have emerged as the preferred approach to multi-vendor RAN automation on a network-wide basis, especially as hybrid and Open RAN architectures become increasingly common in new RAN swap and rollout contracts. Additionally, SMO platforms are being positioned as a common foundation for cross-domain network autonomy that links observability, intelligence, intent management and closed-loop automation. From Swedish wireless giant Ericsson to Spanish private 5G orchestration specialist Neutroon, multiple SMO providers have already incorporated core network interfaces for end-to-end management and automation.
- SMO/Non-RT RIC adoption is beginning to accelerate among brownfield operators – including but not limited to AT&T, Verizon, Telus, Vodafone, DT, Swisscom, STC, NTT DoCoMo, Chunghwa Telecom and Telstra – to enable network-wide automation across thousands of cell sites through RAN vendor-supplied, third-party and internally developed rApps. This follows greenfield operator Rakuten Mobile’s nationwide RIC deployment, along with in-house and third-party rApp integration, across its Open RAN-compliant footprint of 350,000 cells supplied by 10 distinct RU and DU/CU vendors.
- While reluctance among DU/CU vendors has held back adoption of xApps and the Near-RT RIC, there is growing interest in the recently proposed E3 interface, which provides a standardized mechanism for dApps to directly interface with Open RAN baseband nodes for closed-loop control beyond the 10-millisecond latency limits of xApps, including lower-layer performance optimization, geolocation, integrated sensing, spectrum sharing and interference cancellation in 5G and future 6G deployments. RAN vendors and application developers – such as Nokia, NVIDIA, Radisys, IS-Wireless, Cohere Technologies, DeepSig, ISCO International, Unikie, Booz Allen Hamilton and ODC – have already committed to support the E3 interface.
- An alternative to dApps being pursued by some vendors is to offer proprietary AI-enabled, real-time optimization capabilities as software upgrades to existing RAN platforms through subscription-based licensing models. For example, Ericsson has recently launched a software subscription offering for service providers that embeds AI/ML models directly into RAN basebands and radios to improve performance and efficiency through microsecond-level inference for use cases such as scheduling, link adaptation, beamforming and multi-layer coordination.
Evolution Towards AI-Native 6G
- The deeper integration of AI, ML and their derivatives for RAN automation and optimization – commonly referred to as AI-for-RAN – is the most commercially mature facet of the broader AI-RAN movement. The launch of the first 6G networks – which are being standardized as AI-native systems from the outset – around 2030 is expected to significantly increase the scope for hardware-agnostic, software-led innovation and take the industry closer to fully autonomous network operations. RAN digital twins are also expected to play an increasingly important role, allowing operators to validate AI-enabled air interface features and train optimization algorithms in high-fidelity virtual environments before introducing them into live 6G networks.
RAN Automation for NTNs & Private 5G Networks
- Beyond terrestrial public mobile networks, there is growing interest in RAN automation for other segments, including the use of an SMO/RIC governance layer for dynamic resource orchestration in NTNs and interworking with terrestrial RAN infrastructure, from mobility and handover management to on-demand satellite coverage activation – particularly during disaster response scenarios.
- In the private 5G segment, RAN automation applications are being pursued for diverse use cases, including agentic AI to simplify network deployment and administration, converged management of Wi-Fi and private 5G networks, dynamic spectrum allocation between incumbents and other user groups, adaptive power control in offshore cellular deployments, indoor positioning for physical AI and industrial automation in 5G-connected factories, ISAC for drone detection and emission control to limit the electromagnetic signature of tactical 5G infrastructure during military operations.
- One recent example is the implementation of an NVIDIA-powered agentic AI solution for autonomous private 5G network optimization aboard vessels operated by Norwegian shipping company Color Line. In Japan, domestic integrator NTT East has recently concluded a series of tests with 26 vendors to evaluate RIC functionality for AI-enabled autonomous network control applications supporting transmit power optimization and interference mitigation in private 5G networks.
SMO/RIC Ecosystem Consolidation
- The Open RAN automation ecosystem is exhibiting signs of consolidation with Nokia’s acquisition of Juniper Networks’ SMO/RIC assets from HPE (Hewlett Packard Enterprise) and VMware’s exit from the market altogether. We anticipate seeing further M&A activity reminiscent of the SON boom in the previous decade. However, there’s no lack of diversity in the application segment with dozens of companies – including RAN vendors, third-party developers and mobile operators themselves – actively engaged in the development of rApps, xApps and, more recently, dApps.
Nokia & Ericsson’s United Front on rApp-Based Automation
- Nordic telecommunications infrastructure giants Ericsson and Nokia are presenting an unusually united front by joining each other’s SMO/rApp ecosystems, seemingly moving away from the SON era walled garden approach to clear the path for true cross-vendor automation.
……………………………………………………………………………………………………………………………………….
About the Author:
 James Bennett is the Founder and Managing Director of SNS Telecom & IT, a market intelligence and consulting firm that specializes in the telecommunications and information technology industries, with a particular focus on dissecting and analyzing some of the most technically complex segments and their future evolution. Under his leadership, the company has built a client base ranging from incumbent wireless infrastructure vendors and national mobile operators to small startups, through syndicated market research reports and databases, annual service subscriptions and sponsored research.
James also co-founded and successfully divested SNS Research, a sister market intelligence business unit specializing in the digital health, biotechnology and pharmaceutical sectors. James has over 35 years of experience across multiple facets of telecommunications and information technology, including mainframe computers with IBM, transmission and switching with Marconi, network planning and optimization with Aircom International, RAN engineering for the very first third-generation cellular networks in the Middle East, systems integration for one of the world’s first city-wide mobile video surveillance solutions deployed by the Abu Dhabi Police, consulting on one of the largest optical fiber network rollouts undertaken by a state-owned operator in South Asia and a satellite television set-top box manufacturing venture.
…………………………………………………………………………………………………………………………………………………………
References:
https://www.snstelecom.com/son
SNS Telecom & IT: Private 5G for the Defense Sector to hit $2.5 Billion by 2029
SNS Telecom & IT: Private 5G Market to Reach $6.6 Billion as Physical AI Takes Hold
SNS Telecom & IT: Mission-Critical Networks a $9.2 Billion Market
SNS Telecom & IT: Private LTE & 5G Network Ecosystem – CAGR 22% from 2025-2030
SNS Telecom & IT: Private 5G Market Nears Mainstream With $5 Billion Surge
SNS Telecom & IT: Private 5G and 4G LTE cellular networks for the global defense sector are a $1.5B opportunity
SNS Telecom & IT: $6 Billion Private LTE/5G Market Shines Through Wireless Industry’s Gloom
Dell’Oro: AI RAN revenue forecast: $35B from 2026-to-2030; 3 types of AI RAN explained
According to a new AI RAN Advanced Research Report published by Dell’Oro Group, cumulative AI RAN revenue is projected to reach $35 B over the next five years (2026-2030). However, AI RAN is not expected to expand the overall RAN market.
“Our market assessment and long-term AI RAN position remain unchanged,” said Stefan Pongratz, Vice President at Dell’Oro Group. “AI RAN is already happening and will scale ahead of 6G. At the same time, these tools will enhance the RAN, but they are unlikely to expand the overall RAN market. Even as suppliers introduce new software-based subscription models, we expect AI RAN to generate little, if any, incremental RAN revenue the end of the forecast period,” continued Pongratz.
Additional highlights from the June 2026 AI RAN Advanced Research Report:
- The base-case forecast assumes that AI RAN will not expand the RAN market. Nevertheless, AI RAN is expected to become an important technology enabler as operators incorporate greater virtualization, intelligence, automation, and O-RAN capabilities into their RAN roadmaps.
- GPU RAN projections have been revised upward—GPU RAN is now expected to be a $1 B+ market by the end of the forecast period.
- In the near term, the AI RAN market will remain centered on AI-for-RAN, single-purpose deployments, non-GPU architectures, D-RAN, and 5G.
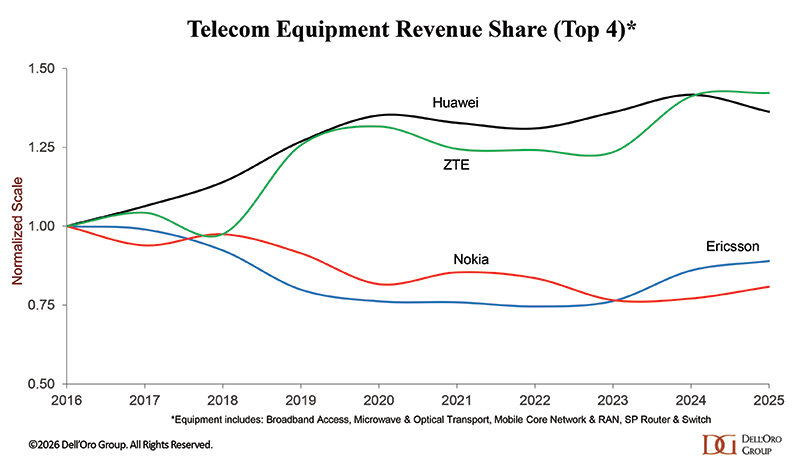
- Incumbent RAN radio and baseband suppliers are well-positioned in the initial AI RAN phase, driven primarily by AI-for-RAN upgrades leveraging existing hardware. Per Dell’Oro Group’s regular RAN coverage, the top five RAN suppliers contributed approximately 96 percent of 2025 RAN revenue. See charts below.
Dell’Oro Group’s AI RAN Advanced Research Report includes a 5-year forecast for AI RAN by location, tenancy, technology, and region. To purchase this report, please contact us at [email protected].
………………………………………………………………………………………………………………………………………………………………………….
Total & Wireless Telecom Equipment Revenue- top 4 and top 3:

………………………………………………………………………………………………………………………………………………………………………………….
Analysis (Source: Perplexity.ai AND Google Gemini):
There are three versions of AI-RAN which are not mutually exclusive:
- AI for RAN: Embeds AI into the base software stack to automatically manage radio waves, optimize spectrum efficiency, enhance beamforming, and reduce energy consumption in real time. Nokia, Ericsson, NVIDIA.
- AI on RAN: Uses cell towers and base stations as decentralized computing nodes. This allows telecom networks to host AI workloads locally rather than sending all data to distant cloud servers, providing ultra-low latency for applications like robotics, AR/VR, and autonomous vehicles. Nokia, NVIDIA, and operator trial partners like T-Mobile, Indosat, and SoftBank.
- AI and RAN: Combines the two to support “Networks for AI,” where distributed telecom networks act as an active, intelligent backbone to serve end-user AI traffic. AI-RAN Alliance plus Nokia and NVIDIA as the most visible industry champions.
References:
AI RAN to Reach $35 B Over Next Five Years, According to Dell’Oro Group
NVIDIA AI RAN video: youtube.com/watch?v=hwLLBfzoSko&t=26
AI-Era Cloud Network Transformation: A Reference Architecture and Implementation Roadmap
Ericsson goes with custom silicon (rather than Nvidia GPUs) for AI RAN
Dell’Oro: RAN Market Stabilized in 2025 with 1% CAG forecast over next 5 years; Opinion on AI RAN, 5G Advanced, 6G RAN/Core risks
AI-RAN Reality Check: hype vs hesitation, shaky business case, no specific definition, no standards?
Analysis: Nvidia’s rumored new 6G AI-RAN – likely features/functions and industry impact
Dell’Oro: 2H2026 Data Center Capex to Accelerate due to massive AI Deployments
Dell’Oro: Analysis of the Nokia-NVIDIA-partnership on AI RAN
RAN silicon rethink – from purpose built products & ASICs to general purpose processors or GPUs for vRAN & AI RAN
Dell’Oro: AI RAN to account for 1/3 of RAN market by 2029; AI RAN Alliance membership increases but few telcos have joined
Dell’Oro: RAN revenue growth in 1Q2025; AI RAN is a conundrum
Dell’Oro: Global RAN market stable (again) in 1Q 2026; top 5 RAN vendors are unchanged
A recently published report from Dell’Oro Group indicates that the stable trends shaping the Radio Access Network (RAN) market in 2025 extended into the first quarter of 2026. Worldwide RAN revenue, excluding services, increased at a low-single-digit year-over-year rate in 1Q 2026, marking the fifth consecutive quarter where the market remained within a relatively narrow range (-4 to +4% year-over-year). However, market fundamentals remain constrained by slower mobile broadband growth.
“This positive start does not alter the fundamentals shaping the growth prospects of this market,” said Stefan Pongratz, Vice President for RAN market research at the Dell’Oro Group. “We attribute the improved conditions primarily to a favorable regional mix and easier comparisons in markets that experienced sharp declines. Meanwhile, RAN remains growth-constrained, and operators are increasingly preparing for a slower mobile broadband growth environment,” Pongratz added.
Additional highlights from the 1Q 2026 RAN report:
- Growth in EMEA and APAC offset weaker activity in North America.
- Revenue rankings were unchanged in 1Q 2026. Based on trailing four-quarter worldwide revenue, the top five RAN suppliers are Huawei, Ericsson, Nokia, ZTE, and Samsung [1.].
- Regional imbalances continue to shape the market recovery trajectory, with APAC excluding China improving while North America and China remain under pressure.
Note 1. There were no significant market share shifts quarter-to-quarter for these five vendors whose ranking remains the same. The ongoing war in Iran, with the Strait of Hormuz closed, has disrupted supply chains for specialized components, while higher energy prices are raising operational costs for infrastructure deployment, creating an increasingly complex environment for network equipment suppliers.

Dell’Oro Group’s RAN Quarterly Report offers a complete overview of the RAN industry, with tables covering manufacturers’ and market revenue for multiple RAN segments including 5G NR Sub-7 GHz, 5G NR mmWave, LTE, Macro BTS, small cells, Massive MIMO, and Cloud RAN. The report also tracks the RAN market by region and includes a four-quarter outlook. To purchase this report, please contact us by email at [email protected]
References:
Worldwide RAN Market Remained Stable in 1Q 2026, According to Dell’Oro Group
Dell’Oro: RAN Market Stabilized in 2025 with 1% CAG forecast over next 5 years; Opinion on AI RAN, 5G Advanced, 6G RAN/Core risks
Dell’Oro: Analysis of the Nokia-NVIDIA-partnership on AI RAN
ABI Research: mobile network spending to fall 29% from 2026-to-2031
Dell’Oro: RAN market stable, Mobile Core Network market +14% Y/Y with 72 5G SA core networks deployed
Market research firms Omdia and Dell’Oro: impact of 6G and AI investments on telcos
Mulit-vendor Open RAN stalls as Echostar/Dish shuts down it’s 5G network leaving Mavenir in the lurch
ABI Research: mobile network spending to fall 29% from 2026-to-2031
According to ABI Research, global mobile network infrastructure spending is projected to peak at ~$92 billion in 2026–2027 before falling 29% to $65 billion by 2031. This decline reflects the maturation of 5G deployments and a shift in operator focus toward 6G, with reduced demand for traditional Radio Access Network (RAN) equipment.
“5G deployments have seen significant growth over the years, with industry estimates placing the current number of launched 5G networks at over 350 globally,” said Matthias Foo, Principal Analyst at ABI Research. “By the end of 2025, global 5G population coverage is expected to reach 60%, driven in part by rapid deployments in India, where more than 500,000 5G Base Transceiver Stations have been installed within three years.”
As 5G rollouts mature, RAN equipment vendors are beginning to report slower growth. Even as advanced deployments such as 5G-Advanced emerge in markets like the United States, China, and Saudi Arabia, overall infrastructure demand is stabilizing following years of rapid expansion.
Recent financial results from major vendors reinforce this trend.
- Ericsson reported flat RAN growth in 2025 and expects a similar outlook for 2026.
- Nokia also posted flat performance in its Mobile Networks business.
- ZTE reported a 5.9% Year-on-Year decline in its Carriers’ Networks segment in the first half of 2025.
Following the release of their respective financial reports, both Ericsson and Nokia said they expect the RAN market to be more or less flat this year. Nokia is focusing on data center networking, while Ericsson is concentrating on mission critical communications, defense, and enterprise networking.
ABI says some near-term growth is still expected in 2026, supported by ongoing deployments in markets such as Malaysia, India, Argentina, Peru, and Vietnam.
Open RAN adoption is forecast to grow at a 26.5% CAGR through 2031, accounting for approximately 23% of the installed base. However, despite high-profile announcements from operators and vendors, the market is still expected to remain largely dominated by incumbent suppliers rather than new entrants initially expected.
These findings are from ABI Research’s Indoor, Outdoor, and IoT Network Infrastructure market data report, part of its 5G, 6G & Open RAN research service. The report provides detailed forecasts, market share analysis, and insights into key infrastructure investment trends.
Research Highlights:
- mMIMO market tracker across regions and by configurations.
- DAS revenue forecasts by region, technology, and verticals.
- Small cell market tracker for both indoor and outdoor infrastructure.
………………………………………………………………………………………………
Dell’Oro Group is slightly less pessimistic than ABI Research. In January, it forecast that global RAN revenues will grow at a 1% CAGR for the remainder of the 2020s, as ongoing 5G investments. Stefan Pongratz said at the time that downside risks still outweigh the upside potential though, the most notable of those being slowing data growth.
References:
Dell’Oro: RAN Market Stabilized in 2025 with 1% CAG forecast over next 5 years; Opinion on AI RAN, 5G Advanced, 6G RAN/Core risks
Dell’Oro: RAN market stable, Mobile Core Network market +14% Y/Y with 72 5G SA core networks deployed
RAN Silicon Rethink- Part II; vRAN and General-Purpose Compute
Will “AI at the Edge” transform telecom or be yet another telco monetization failure?
Ericsson goes with custom silicon (rather than Nvidia GPUs) for AI RAN
Omdia on resurgence of Huawei: #1 RAN vendor in 3 out of 5 regions; RAN market has bottomed
Omdia: Huawei increases global RAN market share due to China hegemony
Dell’Oro Group: RAN Market Grows Outside of China in 2Q 2025
Dell’Oro: AI RAN to account for 1/3 of RAN market by 2029; AI RAN Alliance membership increases but few telcos have joined
RAN Silicon Rethink- Part II; vRAN and General-Purpose Compute
Overview:
The global Radio Access Network (RAN) market has experienced a significant decline, dropping by nearly $10 billion in annual product revenue between 2022 and 2024, from roughly $45 billion to about $35 billion by the end of last year (source: Omdia).
- As the IEEE Techblog previously reported, Nokia is gradually moving away from its long-held reliance on custom RAN baseband (BBU) silicon from Marvell [1.] as it pivots to use Nvidia’s GPUs, as part of the latter’s $1B investment in Nokia in October 2025.
Note 1. Nokia uses Marvell RAN silicon in its 5G ReefShark portfolio. The companies collaborate to develop custom OCTEON SoC (System-on-a-Chip) and Infrastructure Processors, which are used to boost 5G AirScale base station performance.
- Samsung has long partnered with Marvell Technology on purpose-built 5G baseband silicon. However, rising development costs and a contracting market for proprietary RAN hardware are reshaping that strategy. The economic case for new, custom RAN chipsets is becoming weaker as operators accelerate network virtualization.
- In sharp contrast, Ericsson continues to defend its investment in proprietary silicon architectures while maintaining a flexible approach for operators that prefer virtualized or cloud RAN implementations running on standard central processing units (CPUs). At present, those solutions rely exclusively on Intel processors, though Ericsson notes its software is being engineered with portability in mind to support future hardware diversity.
Samsung’s Silicon Strategy:
Among RAN equipment vendors accessible to operators across North America and much of Europe, Samsung now stands as the principal alternative to the two Nordic RAN equipment suppliers, following the exclusion of Huawei and ZTE from many Western markets.
The South Korean conglomerate has become the global frontrunner in virtualized RAN (vRAN) deployments. Whereas custom silicon once dominated RAN infrastructure design, Samsung’s strategy has notably inverted that paradigm: vRAN is now its mainstream offering, and purpose-built hardware has moved to the periphery.
By the close of last year, Samsung reported supporting approximately 53,000 vRAN sites worldwide — a significant share of which lies within Verizon’s U.S. footprint. The company also disclosed major European developments, including Vodafone’s planned rollout across Germany and other markets, which will rely entirely on vRAN technology. For Samsung, discussions of bespoke, purpose-built 5G infrastructure have become increasingly rare.
According to Alok Shah, Vice President of Network Strategy at Samsung Networks, this transition reflects both the rising cost of developing custom silicon and the performance enhancements achieved by general-purpose CPU platforms.
“We’re still selling our purpose-built BBUs to a number of customers, but I do believe that it’s a matter of time,” Shah told Light Reading during MWC Barcelona, when asked if Samsung envisions an eventual phaseout of its proprietary baseband hardware portfolio.
Virtualized RAN Gains Momentum:
Transitioning to virtualized RAN (vRAN) allows network equipment vendors to capitalize on the scale economies of commercial data-center silicon. Samsung has established commercial vRAN contracts with Verizon and Vodafone, reflecting growing operator confidence in software-defined architectures.
“Virtual RAN performance has reached parity,” Shah said. “I know not all of our competitors feel that way, but that’s certainly how we feel. And the cost of building that modem is pretty high, even for a company like Samsung that’s really good at semiconductors,” he added.
Intel’s Granite Rapids Xeon platform exemplifies this shift to vRAN. The processor’s increased core density enables operators to cut hardware footprints; in many configurations, a single server can now support workloads that previously required two. Several network operators have confirmed this performance improvement during field evaluations.
Samsung and Ericsson continue to explore additional CPU suppliers. AMD’s latest multicore x86 processors offer up to 84 cores, compared with 72 in Intel’s Granite Rapids. However, offloading Forward Error Correction (FEC)—one of the most compute-intensive RAN processes—remains a challenge. Intel’s vRAN Boost feature integrates a dedicated hardware accelerator for FEC, while AMD currently lacks a direct equivalent.
Samsung has also evaluated Arm-based platforms, which increasingly support efficient software migration from x86. Nvidia’s Grace CPU, built on Arm architecture, has emerged as a potential candidate, especially when paired with its GPUs for selective Layer 1 acceleration.
Samsung’s roadmap aligns with a gradual and selective introduction of GPU acceleration. The company demonstrated GPU-based beamforming optimization during MWC, illustrating how AI can refine radio energy targeting. However, Samsung executives maintain that the latest Intel CPUs also provide sufficient capacity to host AI inference workloads directly. “Granite Rapids has plenty of capacity to support AI algorithms on-platform,” noted Shah.
While Nokia is building a GPU-compatible Layer 1 to accelerate computationally intensive baseband functions—including FEC—Samsung’s approach appears incrementally narrower, focusing on targeted AI for RAN optimization rather than complete GPU offload. GPUs may ultimately support AI at the Edge applications—so-called AI and RAN—where telecom operators leverage deployed GPUs for latency-sensitive inference services.
The degree to which such applications will reside within RAN sites remains uncertain. Some operators suggest that edge inference may instead remain within core network clusters that can meet latency requirements more efficiently.
Samsung’s architecture already supports GPU integration through commercial off-the-shelf (COTS) servers from manufacturers such as HPE, Dell, and Supermicro—aligning with broader cloud-native RAN trends. “It’s an off-the-shelf card that can be integrated directly into standard servers,” said Shah.
For now, Intel remains Samsung’s primary compute partner for commercial vRAN products. “We haven’t had an instance where customers are pushing for a second platform—it’s primarily a matter of commercial interest,” Shah added. The direction is clear: Samsung, like other leading vendors, is prioritizing scalable, general-purpose compute over bespoke 5G silicon as vRAN deployment accelerates.
……………………………………………………………………………………………………………………………………………………………………
References:
https://www.lightreading.com/5g/samsung-eyes-death-of-purpose-built-5g-but-has-no-ai-ran-fears
RAN silicon rethink – from purpose built products & ASICs to general purpose processors or GPUs for vRAN & AI RAN
Ericsson goes with custom silicon (rather than Nvidia GPUs) for AI RAN
Marvell shrinking share of the RAN custom silicon market & acquisition of XConn Technologies for AI data center connectivity
Intel FlexRAN™ gets boost from AT&T; faces competition from Marvel, Qualcomm, and EdgeQ for Open RAN silicon
Analysis: Nokia and Marvell partnership to develop 5G RAN silicon technology + other Nokia moves
Dell’Oro: RAN Market Stabilized in 2025 with 1% CAG forecast over next 5 years; Opinion on AI RAN, 5G Advanced, 6G RAN/Core risks
A recently published report from Dell’Oro Group reveals that the Radio Access Network (RAN) market ended the year on a stable note, with stronger than typical 3Q to 4Q seasonality. Fourth-quarter results were consistent with the broader stabilization trend that shaped the RAN market throughout the year, resulting in stable revenue trends for the full year.
“Taking into consideration that the RAN market lost around a fifth of its value between 2022 and 2024, this improved stability in 2025 represents a welcome shift in market conditions,” said Stefan Pongratz, Vice President for RAN market research at the Dell’Oro Group. “Helping to explain the improved sentiment are the more favorable regional mix, easier comparisons, and the weaker USD. Even so, we have not made any material changes to the short-term outlook and still expect the market to be mostly flat in 2026,” continued Pongratz.
Additional highlights from the 4Q 2025 RAN report:
- Revenue rankings did not change in 2025. The top 5 RAN suppliers by worldwide revenue are Huawei, Ericsson, Nokia, ZTE, and Samsung.
- RAN vendor dynamics shifted in 2025—leading vendors strengthened their positions, while smaller suppliers adjusted their strategies. As a result, overall RAN market concentration increased during the year.
- Overall market concentration, as measured by the Herfindahl–Hirschman Index, reached a 10-year high in 2025.
- In 2025, Huawei and Nokia gained ground, Ericsson and Samsung were stable, and ZTE’s RAN revenue share fell.
- The fundamentals that shape the RAN market have not changed, and the long-term trajectory discussed in the most recent 5-year forecast still holds (1% CAGR, 2025-2030).
- The short-term outlook is mostly unchanged, with total RAN expected to remain stable in 2026.
RAN is not a growth market over time (0% CAGR 2020-2025 in nominal US $). However, it can go through periods of higher and lower capital intensity ratios as operators align investment needs with the availability of new spectrum/technologies and demand for capacity. The base case forecast is for stable RAN and capex trends, resulting in further improvements in capital intensity ratios before 6G investments commence towards the end of the forecast period. Worldwide RAN revenue is projected to grow at a 1% CAGR over the next five years, as rapidly declining LTE capex will offset continued 5G and initial 6G investments. RAN as a share of wireless capex is expected to average in the 20 to 25 percentage share range over the forecast period.

Dell’Oro Group’s RAN Quarterly Report offers a complete overview of the RAN industry, with tables covering manufacturers’ and market revenue for multiple RAN segments including 5G NR Sub-7 GHz, 5G NR mmWave, LTE, macro base stations and radios, small cells, Massive MIMO, Open RAN, and vRAN. The report also tracks the RAN market by region and includes a four-quarter outlook. To purchase this report, please contact us by email at [email protected].
…………………………………………………………………………………………………………………………………………………………………………………………..
Editors Opinion:
This author believes that the only RAN growth driver over the next 5 years will be investments in 5G SA core networks, which finally is starting to be deployed more than 5G NSA networks as we noted in today’s companion IEEE Techblog post. Omdia forecasts that 5G SA core network software spending will grow at an 8.8% CAGR between 2025 and 2030, making it a primary driver of investment. Continued 5G investments by global telcos are largely being offset by sharply declining 4G-LTE investments, leading to a “stable” rather than a growing RAN market.
Neither AI RAN, 5G Advanced, or Open RAN will be significant RAN market growth drivers:
- 5G Advanced (5G-A): 5G Advanced is widely considered a key part of the roadmap toward 6G. While some operators are focusing on it, its initial impact on overall global RAN revenue is expected to be more incremental rather than a massive boom in the next 2-3 years. If 5G-Advanced is seen by operators as “incremental” and 6G is legally/technically bound to a 2030/2031 ITU-R standards and 3GPP spec finalization, there is very little “must-have” radio hardware for a network operator to buy before 2030 at the earliest.
- AI-RAN: While AI-RAN is viewed as a key tool for improving efficiency and reducing energy costs (operational expenditure), its immediate impact on capital investment (Capex) in RAN equipment is likely to be slower. However, some, like Samsung, argue that AI-RAN is already driving optimizations in 2026. AI-RAN is primarily an OpEx play. Network operators are buying software and specialized silicon to lower their energy bills and automate frequency management. While this is critical for their survival, it doesn’t create a new “coverage wave” of RAN spending. It’s simply a “treading water” investment.
- Open RAN: has not led to increased RAN sales or multi-vendor equipment in the same RAN. Rather, it is a procurement shift, not a market expander.
There may be pockets of RAN growth in 5G-Advanced for specific performance needs, 5G private networks, and AI-enabled efficiency tools. However, we believe that the global RAN market will continue to stagnate till 6G network are deployed in early 2031.
Stefan had forecast that “cumulative 6G RAN investments over the 2029-2034 period are projected to account for 55 to 60% of the total RAN capex over that time period.” However, 6G capex does not translate into 6G RAN revenue until 6G is actually deployed!
Any earlier 6G deployment will be BEFORE the 5G RAN (IMT 2030 RIT/SRITs) and IMT 2030 Frequency arrangements standards are approved by ITU-R in late 2030 or early 2031 as IMT 2030 recommendations. Note that 3GPP Release 21 marks the official start of its normative 6G work. While the specific milestones for Release 21 are to be decided by June 2026, it is widely expected to produce the first formal 6G RAN technical specifications by late 2028 or early 2029 and submit them to ITU-R WP 5D via ATIS. Therefore, any 6G RAN equipment shipped before the 2030 ITU seal of approval would be based on pre-standardized or early 3GPP specifications that may require later alignment and hardware/software updates.
–>No rational wireless network operator wants to deploy thousands of “6G-ready” sites in 2029 only to find that the ITU-R IMT 2030 RIT/SRITs and/or Frequency Arrangements finalized in late 2030 require a hardware filter change or a different sub-carrier spacing to meet global interference requirements.
Hopefully, 3GPP will have finalized its 6G core network specs during the same time period so that 6G RANs will be complemented with 6G core networks- unlike the initial 5G RAN rollouts which had 4G evolved packet cores (5G NSA).
Potential Repeat Problem of No 6G Core Network Standard:
It’s highly likely that 3GPP will once again (like with 5G) not submit their 6G core network specs to ITU-T which is responsible for non-radio aspects of wireless networks. That means that 3GPP effectively operates as a silo for the 6G Core Network (refusing ITU-T oversight),so there will likely be no unified global regulatory mandate for the “6G system” as a whole—only for the “radio” (ITU-R IMT 2030 recommendations). This might allow operators to delay 6G SA Core deployments indefinitely, which in turn kills the business case for buying new 5G-Advanced or AI-RAN hardware.
Google Gemini: If the 6G Core Network isn’t standardized in a way that allows operators to actually monetize these new radio architectures, it doesn’t matter if the RAN is “Open,” “AI-enabled,” or “Advanced.” It’s still just a cost center on a stagnant balance sheet. If the “brain” (6G Core) doesn’t support the “limbs” (6G RAN), the market may not buy the limbs and 6G RAN sales will disappoint, just as 5G RAN sales did. Many carriers are still struggling to recoup the billions spent on 5G deployment so are seriously concerned about the 6G ROI.
| Feature | 5G Challenge | 6G Challenge |
|---|---|---|
| Spectrum | Mid-band & mmWave (24-52 GHz) | Sub-THz & THz (>100 GHz) |
| Connectivity | Massive IoT (1M devices/km²) | Internet of Senses (10M devices/km²) |
| Architecture | Cloud-native | AI-native & “Cell-free” MIMO |
| Primary Goal | Enhanced Mobile Broadband | Convergence of Physical & Digital worlds |
………………………………………………………………………………………………………………………………………………………………………………………..
References:
https://www.linkedin.com/feed/update/urn:li:activity:7422420902362988544/
6G Capex Ramp to Start Around 2030, According to Dell’Oro Group
Dell’Oro: Mobile Core Networks +15% in 2025; Ookla: Global Reality Check on 5G SA and 5G Advanced in 2026
Dell’Oro: RAN market stable, Mobile Core Network market +14% Y/Y with 72 5G SA core networks deployed
Omdia on resurgence of Huawei: #1 RAN vendor in 3 out of 5 regions; RAN market has bottomed
Dell’Oro Group: RAN Market Grows Outside of China in 2Q 2025
Dell’Oro: AI RAN to account for 1/3 of RAN market by 2029; AI RAN Alliance membership increases but few telcos have joined
Omdia: Huawei increases global RAN market share due to China hegemony
Network equipment vendors increase R&D; shift focus as 0% RAN market growth forecast for next 5 years!
vRAN market disappoints – just like OpenRAN and mobile 5G
Analysis: Rakuten Mobile and Intel partnership to embed AI directly into vRAN
Today, Rakuten Mobile and Intel announced a partnership to embed Artificial Intelligence (AI) directly into the virtualized Radio Access Network (vRAN) stack. While vRAN currently represents a small percentage of the total RAN market (Dell’Oro Group recently forecasts vRAN to account for 5% to 10% of the total RAN market by 2026), this partnership could boost increase that percentage as it addresses key adoption hurdles—performance, power, and AI integration. Key areas of innovation include:
- Enhanced Wireless Spectral Efficiency: Optimizing spectrum utilization for superior network performance and capacity.
- Automated RAN Operations: Streamlining network management and reducing operational complexities through intelligent automation.
- Optimized Resource Allocation: Dynamically allocating network resources for maximum efficiency and subscriber experience.
- Increased Energy Efficiency: Significantly reducing power consumption in the RAN, contributing to sustainable network operations.
The partnership essentially aims to make vRAN superior in performance and TCO (Total Cost of Ownership) compared to traditional, proprietary, purpose built RAN hardware.
“We are incredibly excited to expand our collaboration with Intel to pioneer truly AI-native RAN architectures,” said Sharad Sriwastawa, co-CEO and CTO, Rakuten Mobile. “Together, we are validating transformative AI-driven innovations that will not only shape but define the future of mobile networks. This partnership showcases how intelligent RAN can be achieved through the seamless and efficient integration of AI workloads directly within existing vRAN software stacks, delivering unparalleled performance and efficiency.”
Rakuten Mobile and Intel are engaged in rigorous testing and validation of cutting-edge RAN AI use cases across Layer 1, Layer 2, and comprehensive RAN operation and network platform management. A core objective is the seamless integration of AI directly into the RAN stack, meticulously addressing integration challenges while upholding carrier-grade reliability and stringent latency requirements.
Utilizing Intel FlexRAN reference software, the Intel vRAN AI Development Kit, and a robust suite of AI tools and libraries, Rakuten Mobile is collaboratively training, optimizing, and deploying sophisticated AI models specifically tailored for demanding RAN workloads. This collaborative effort is designed to realize ultra-low, real-time AI latency on Intel Xeon 6 SoC, capitalizing on their built-in AI acceleration capabilities, including AVX512/VNNI and AMX.
“AI is transforming how networks are built and operated,” said Kevork Kechichian, Executive Vice President and General Manager of the Data Center Group, Intel Corporation. “Together with Rakuten, we are demonstrating how AI benefits can be achieved in vRAN. Intel Xeon processors power the majority of commercial vRAN deployments worldwide, and this transformation momentum continues to accelerate. Intel is providing AI-ready Xeon platforms that allow operators like Rakuten to design AI-ready infrastructure from the ground up, with built-in acceleration capabilities.”
Rakuten says they are “poised to unlock new levels of RAN performance, efficiency, and automation by embedding AI directly into the RAN software stack, this AI-native evolution represents the future of cloud-native, AI-powered RAN – inherently software-upgradable and built on open, general-purpose computing platforms. Additionally, the extended collaboration between Rakuten Mobile and Intel marks a significant step toward realizing the vision of autonomous, self-optimizing networks and powerfully reinforces both companies’ commitment to open, programmable, and intelligent RAN infrastructure worldwide.”
……………………………………………………………………………………………………………………………………………………………………..
- AI-Native Efficiency & Performance: The collaboration focuses on integrating AI to improve network performance and energy efficiency, which is a major pain point for operators. By embedding AI directly into the vRAN stack, they are enhancing wireless spectral efficiency, reducing power consumption, and automating RAN operations.
- Leveraging High-Performance Hardware: The initiative utilizes Intel® Xeon® 6 processors with built-in vRAN Boost. This eliminates the need for external, power-hungry accelerator cards, offering up to 2.4x more capacity and 70% better performance-per-watt.
- Validation of Large-Scale Commercial Viability: Rakuten Mobile operates the world’s first fully virtualized, cloud-native network. Its continued collaboration with Intel to make the vRAN AI-native provides a proven blueprint for other operators, reducing the perceived risk of adopting vRAN, particularly in brownfield (existing) networks.
- Acceleration of Open RAN Ecosystem: The collaboration supports the broader push towards Open RAN, which is expected to see a significant rise in market share, doubling between 2022 and 2026.
………………………………………………………………………………………………………………………………………………………………
- Market Share Shift: Omdia forecasts that vRAN’s share of the RAN baseband subsector will reach 20% by 2028. That’s a significant jump from its current low single-digit percentage.
- Explosive CAGR: The global vRAN market is projected to grow from approximately $16.6 billion in 2024 to nearly $80 billion by 2033, representing a 19.5% CAGR.
- Small Cell Dominance: By the end of 2026, it is estimated that 77% of all vRAN implementations will be on small cell architectures, a key area where Rakuten and Intel have demonstrated success.
References:
https://corp.mobile.rakuten.co.jp/english/news/press/2026/0210_01/
Virtual RAN gets a boost from Samsung demo using Intel’s Grand Rapids/Xeon Series 6 SoC
RAN silicon rethink – from purpose built products & ASICs to general purpose processors or GPUs for vRAN & AI RAN
vRAN market disappoints – just like OpenRAN and mobile 5G
LightCounting: Open RAN/vRAN market is pausing and regrouping
Dell’Oro: Private 5G ecosystem is evolving; vRAN gaining momentum; skepticism increasing
https://www.mordorintelligence.com/industry-reports/virtualized-ran-vran-market
https://www.grandviewresearch.com/industry-analysis/virtualized-radio-access-network-market-report
Vodafone Spain (Zegona), MasOrange and Telefonica in possible RANco joint venture
In an interview with Expansion published on January 26, 2026, Zegona [1.] CEO Eamonn O’Hare revealed that Vodafone Spain, MasOrange and Telefonica have been holding talks on the possibility of joining their mobile networks together since late last year. “We are talking with Orange and Telefónica to create a RANco,” he said.
Note 1. Zegona owns 100% of Vodafone Spain.
However, Zegona was unable to give the potential joint venture its full attention due to demands of its ongoing fiber projects. Telefonica and Vodafone created their Fiberpass joint venture (JV) in 2025 and agreed to sell a 40% stake to AXA in November. Meanwhile, Vodafone and MasOrange brought in GIC as an investor in their PremiumFiber JV last summer.
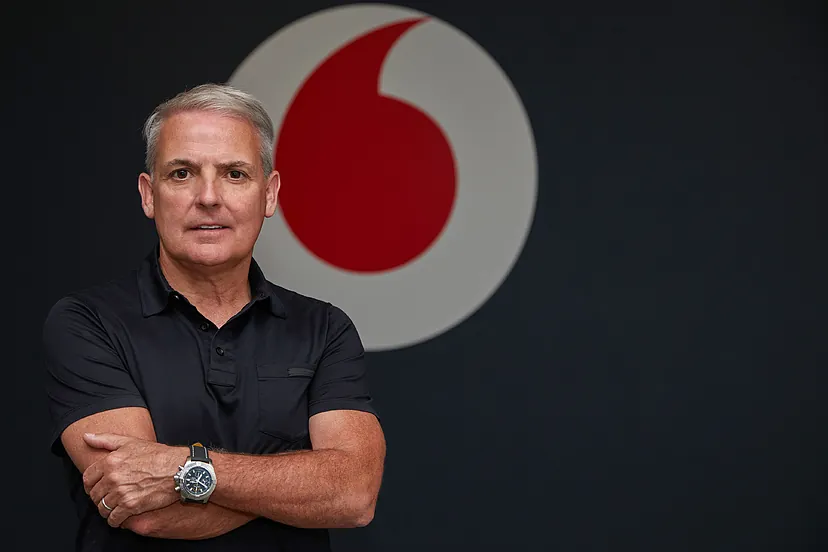
Eamonn O’Hare, president and CEO of Zegona
“The whole team was so involved in the fibercos that we didn’t have the time or energy to thoroughly develop the project,” O’Hare told the Expansion. Instead, his staff focused on tying up the fiber optic projects and then took a break over the Christmas period, he explained. “And now we’re back with more energy.”
Why a JV rather than a merger of telcos: “Mergers and acquisitions are not a priority in Spain and the regulatory risk is very high,” he said. Zegona has a greater motivation to make the RANco a reality. “Today there are three companies…that manage three national mobile networks with exactly the same fixed costs, but Orange and Telefónica have twice as many customers as us,” O’Hare explained. “Therefore, our national mobile network is inefficient. Just as our fixed infrastructure was inefficient and unprofitable, [and] that’s why we powered the fibercos.”
“It would be easier to broker a deal with MasOrange to share the network in certain areas, so the synergies would be in urban areas. But we don’t have anything with Telefónica, so there it would all be synergies.” Telefonica already has a mobile network sharing deal in place with Vodafone in sparsely populated areas, and was rumoured to be in talks with the telco on a broader RANco arrangement this time last year.
As a result, a partnership with Telefonica would bring greater synergies as there are no existing arrangements in place in the mobile space, but any deal would be a more difficult deal to hammer out and it would be trickier to bring in an investor, O’Hare added. Zegona has three priorities in Spain: to align its valuation with those of its competitors; to boost its cash flow to €1 billion; and to develop a RANco. “As long as we are in the middle of that transformation, we have no interest in mergers and acquisitions,” he said. And in addition, “the regulatory obstacle is…too big.”
“Historically, these small businesses have grown and then tried to sell themselves to MásMóvil. But MásMóvil no longer buys. Neither do we or Telefónica,” O’Hare said. “No one is buying. So they… will just be devoured by us and by Digi, as in the Pac-Man game.”
Would Huawei network equipment be used in the proposed Spanish RanCo? Vodafone is the mobile operator with the largest network provided by Huawei. Orange is reducing its share, and Telefónica only uses Huawei in part of its core network in Spain and not at all in its radio network. If the Brussels Cybersecurity Act mandates the replacement of this Chinese equipment, what will Vodafone Spain (Zegona) do?
“If Europe is more aggressive on the Huawei issue , I suppose we should accelerate efforts to reduce the amount of Huawei equipment in the network… should we accelerate RANco for this reason? Officially, the answer is no.”
……………………………………………………………………………………………………………….
References:
https://www.expansion.com/empresas/tecnologia/2026/01/26/6973ab17468aebd1418b4590.html
SNS Telecom & IT: Private 5G Market Nears Mainstream With $5 Billion Surge
España hit with major telecom blackout after power outage April 28th
Orange Spain & Ericsson to build 5G Infrastructure for 3 High-Speed Rail Lines
Telefónica and Nokia partner to boost use of 5G SA network APIs
Telefónica launches 5G SA in >700 towns and cities in Spain
Telefónica – Nokia alliance for private mobile networks to accelerate digital transformation for enterprises in Latin America
Ericsson and O2 Telefónica demo Europe’s 1st Cloud RAN 5G mmWave FWA use case
Telecom and AI Status in the EU
Marvell shrinking share of the RAN custom silicon market & acquisition of XConn Technologies for AI data center connectivity
Samsung and Nokia currently use Marvell’s OCTEON Fusion baseband processors and OCTEON Data Processing Units (DPUs) in their 5G Radio Access Network (RAN) equipment.
- OCTEON Fusion Processors: Samsung uses these baseband processors in its 5G base stations, particularly for massive MIMO (Multiple-Input Multiple-Output) deployments that require significant compute power for complex beamforming algorithms.
- OCTEON and OCTEON Fusion Families: Samsung has leveraged multiple generations of these processors for baseband and transport processing solutions.
- Customized OCTEON Silicon: Nokia uses customized Marvell OCTEON silicon across key applications, including multi-RAT (Radio Access Technology) RAN and transport.
- OCTEON Fusion Processors: These are used for baseband processing in Nokia’s 5G products.
- OCTEON TX2 and OCTEON 10 Families: These infrastructure processors are used for demanding tasks like packet processing, security, and edge inferencing within Nokia’s 5G infrastructure.
- OCTEON 10 Fusion: Nokia is working with the latest generation of this 5nm baseband platform, which supports use cases from radio units (RU) to distributed units (DU) for both traditional and Open RAN architectures.
……………………………………………………………………………………………………………………………………………………………………………….
Meanwhile, the total global RAN market has been declining for years as network operators slash investment in network equipment and cut jobs. According to Omdia (owned by Informa):
- Global RAN equipment sales fell from $45 billion in 2022 to $40 billion in 2023 and just $35 billion in 2024. Nokia’s mobile networks business group suffered an operating loss of €64 million (US$75 million) on sales of €5.3 billion ($6.2 billion) for the first nine months of 2025.
- For its 2023 fiscal year (ending in January 2023), Marvell’s carrier division made almost $1.1 billion in revenues, more than 18% of total company sales. Two years later, annual revenues had slumped to just $338.2 million, less than 6% of turnover.
- Marvell’s carrier sales have also recently improved in fiscal 2026, rising 88% year-over-year for the first nine months, to $436.3 billion. However, that’s still half as much as Marvell made during the first nine months of fiscal 2024, and interest in the RAN has seemingly evaporated.
- Samsung’s share of the shrinking RAN market has declined. Amid contraction of the entire addressable market, revenues generated by Samsung Networks fell from 5.39 trillion South Korean won ($3.74 billion) in 2022 to just KRW2.82 trillion ($1.95 billion) in 2024. For the first nine months of 2025, Samsung reported network sales of KRW2.1 trillion ($1.46 billion). But it has also lost market share, which dipped from 6.1% in 2023 to 4.8% in 2024, according to Omdia.
- Ericsson has two development tracks – one for purpose-built RAN products based partly on its own custom RAN silicon and the other for an Intel-based virtual RAN. In contrast to Samsung, the purpose-built RAN silicon portfolio today accounts for nearly all of the company’s sales.
- Ericsson’s senior managers increasingly talk about virtualization as a means of developing one set of software for multiple hardware platforms. The hope is that software originally designed for use with Intel’s processors could be redeployed on CPUs from AMD or licensees from ARM Ltd. with minimal coding changes. Such optionality combined with the narrowing of the performance gap between CPUs and purpose built RAN silicon would make it hard for Ericsson to justify investment in its own custom silicon.
…………………………………………………………………………………………………………………………………………………………………………….
Today, Marvell announced it will acquire XConn Technologies for $540 million to boost AI/data center connectivity. In late 2025, the company announced the acquisition of Celestial AI for up to $5.5 billion to expand its optical interconnects for next-gen data centers, solidifying its position in infrastructure semiconductors.
Adding XConn’s PCIe and CXL switching technology (see illustrations below), fills gaps in Marvell’s silicon portfolio and enables the company to expand into higher-speed interconnects (like PCIe Gen 6).

XConn Technologies XC 50256 chip: 256 lanes with total 2,048GB/s switching capacity
…………………………………………………………………………………………………………………………………….

XC50256 CXL 2.0 Switch Chip
……………………………………………………………………………………………………………………………………………………………
As AI workloads scale, data center system design is evolving from single-rack deployments to larger, multi-rack configurations. These next-generation platforms increasingly require a high-bandwidth, ultra-low latency scale-up fabric such as UALink to efficiently connect large numbers of XPUs and enable more flexible resource sharing across the system.
UALink is a new open industry standard purpose-built for scale-up connectivity, enabling efficient, high-speed communication so multiple accelerators can operate together as a single, larger system. UALink builds on decades of PCIe ecosystem innovation and incorporates proven high-speed I/O techniques to meet the bandwidth, latency, and reach requirements of next-generation accelerated infrastructure.
Together, Marvell and XConn will bring together a significantly larger, integrated team to fully address the rapidly emerging opportunity in UALink switching as well as comprehensively support the growing list of customers and partners who want to work with Marvell in evolving their next generation AI platforms.
About Marvell:
To deliver the data infrastructure technology that connects the world, we’re building solutions on the most powerful foundation: our partnerships with our customers. Trusted by the world’s leading technology companies for over 30 years, we move, store, process and secure the world’s data with semiconductor solutions designed for our customers’ current needs and future ambitions. Through a process of deep collaboration and transparency, we’re ultimately changing the way tomorrow’s enterprise, cloud and carrier architectures transform—for the better.
About XConn Technologies:
XConn is the innovation leader in next-generation interconnect technology for high-performance computing and AI applications. The company is the industry’s first to deliver a hybrid switch supporting both CXL and PCIe on a single chip. Privately funded, XConn is setting the benchmark for data center interconnect with scalability, flexibility, and performance. For more information visit: https://www.xconn-tech.com
……………………………………………………………………………………………………………………………………………………………
References:
https://www.lightreading.com/5g/fragile-samsung-deal-with-marvell-shows-challenge-for-ran-chipmakers
RAN silicon rethink – from purpose built products & ASICs to general purpose processors or GPUs for vRAN & AI RAN
Dell’Oro: Analysis of the Nokia-NVIDIA-partnership on AI RAN
Intel FlexRAN™ gets boost from AT&T; faces competition from Marvel, Qualcomm, and EdgeQ for Open RAN silicon
Analysis: Nokia and Marvell partnership to develop 5G RAN silicon technology + other Nokia moves
Samsung and Marvell develop SoC for Massive MIMO and Advanced Radios
China gaining on U.S. in AI technology arms race- silicon, models and research
Omdia on resurgence of Huawei: #1 RAN vendor in 3 out of 5 regions; RAN market has bottomed