Author: Alan Weissberger
Fierce Network Research report examines telcos role in the AI economy and profiles early AI adopters
The telecommunications industry is at a critical crossroads. As AI reshapes global value chains, communications service providers (CSPs) must determine their strategic position: will they remain infrastructure enablers or evolve into full-scale participants in the AI economy?
A new Fierce Network Research report — “Risk, Reward and Revenue: Defining Telcos’ Role in the AI Economy” — examines this identity challenge — and how network operators are recalibrating for the next generation of network-driven intelligence. Based on a global survey of 500 technology decision-makers across 40 countries, the findings reveal a pronounced industry divide. A majority (57%) of operators see their core opportunity in infrastructure — networks, data centers, and secure connectivity — while 43% advocate for a more integrated position, aspiring to orchestrate AI ecosystems (19%) or participate fully in the AI value chain (24%).
Some of the industry’s early adopters are already showing what that future might look like.
- AT&T reports a twofold increase in cash flow for every dollar it invests in AI, emphasizing measurable outcomes over vague productivity gains. An AT&T executive said that success in the AI era depends on “Goldilocks governance” — a balance not too rigid to stifle innovation, and not too loose to compromise compliance and trust.
- Bell Canada is moving in a similar direction, targeting a doubling of enterprise AI revenue by 2028 and positioning its Ateko subsidiary and AI Fabric platform as the backbone of a “sovereign digital spine” for Canada.
- “We’re using AI to enhance our products and services and make them better,” Ed Fox, MetTel CTO. The company provides a private network to deliver integrated communications and IT services to U.S. businesses and government agencies, including voice, data, network, cloud, mobility, IoT and security solutions. MetTel also provides managed network services such as SD-WAN and secure access service edge (SASE).
- Rick Lievano, Microsoft CTO for the worldwide telecommunications industry, sees operators expanding their use of AI beyond efficiency. “Initially, the first place where telcos began to experiment with AI is around efficiency gains — how can I save money, and how can I do more with fewer people? That’s been the target of the first couple of waves of AI,” Lievano said. “However, their eyes light up when we talk with them about new revenue opportunities,” Lievano said.
The research highlights that telcos possess critical assets few other industries can match: globally distributed data center capacity, secure and resilient networks, and deep, long-standing relationships with enterprise and government customers. But the barriers are equally significant — from proving the business case for AI infrastructure to navigating a shortage of data science and AI talent. Legacy technology debt continues to drag, with one executive lamenting that 145 years of accumulated systems make modern data integration “extraordinarily complex.”

A new Fierce Network Research report reveals how communication service providers are navigating the AI economy amid uncertainty about their role and strategy. (Google Gemini)
The bottom line is clear: to remain relevant in the AI-driven economy, telcos must modernize both infrastructure and business models — transforming from connectivity providers into intelligent digital enablers. However, we’ve heard that cry for telco transformation from dumb pipes to intelligent and autonomous network and IT providers, but it has yet to be realized. Will this time be any different?
References:
https://www.fierce-network.com/cloud/dumb-pipes-or-ai-powerhouses-telcos-face-identity-crisis
Full REPORT: “Risk, Reward and Revenue: Defining telcos’ role in the AI economy.”
Private 5G networks move to include automation, autonomous systems, edge computing & AI operations
Palo Alto Networks and Google Cloud expand partnership with advanced AI infrastructure and cloud security
Generative AI could put telecom jobs in jeopardy; compelling AI in telecom use cases
Generative AI in telecom; ChatGPT as a manager? ChatGPT vs Google Search
Allied Market Research: Global AI in telecom market forecast to reach $38.8 by 2031 with CAGR of 41.4% (from 2022 to 2031)
Markets and Markets: Global AI in Networks market worth $10.9 billion in 2024; projected to reach $46.8 billion by 2029
Ericsson integrates Agentic AI into its NetCloud platform for self healing and autonomous 5G private networks
Ericsson CEO’s strong statements on 5G SA, WRC 27, and AI in networks
New Linux Foundation white paper: How to integrate AI applications with telecom networks using standardized CAMARA APIs and the Model Context Protocol (MCP)
Vodafone Spain (Zegona), MasOrange and Telefonica in possible RANco joint venture
In an interview with Expansion published on January 26, 2026, Zegona [1.] CEO Eamonn O’Hare revealed that Vodafone Spain, MasOrange and Telefonica have been holding talks on the possibility of joining their mobile networks together since late last year. “We are talking with Orange and Telefónica to create a RANco,” he said.
Note 1. Zegona owns 100% of Vodafone Spain.
However, Zegona was unable to give the potential joint venture its full attention due to demands of its ongoing fiber projects. Telefonica and Vodafone created their Fiberpass joint venture (JV) in 2025 and agreed to sell a 40% stake to AXA in November. Meanwhile, Vodafone and MasOrange brought in GIC as an investor in their PremiumFiber JV last summer.
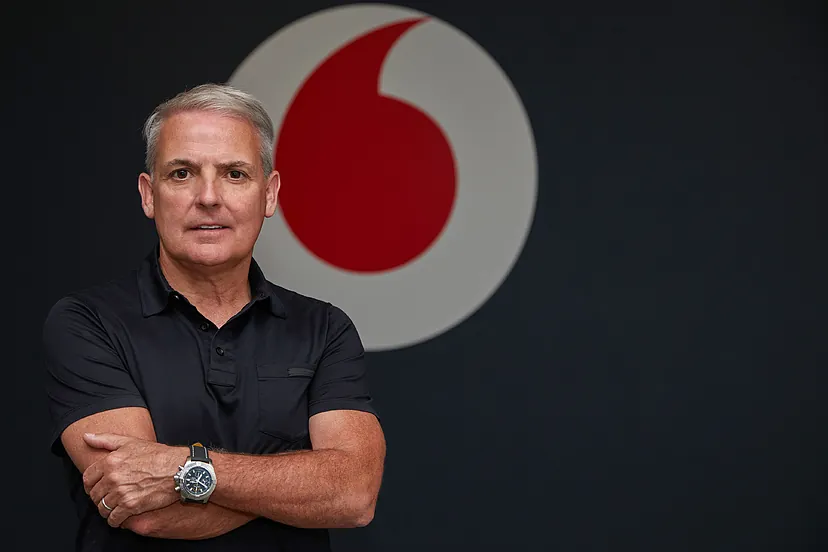
Eamonn O’Hare, president and CEO of Zegona
“The whole team was so involved in the fibercos that we didn’t have the time or energy to thoroughly develop the project,” O’Hare told the Expansion. Instead, his staff focused on tying up the fiber optic projects and then took a break over the Christmas period, he explained. “And now we’re back with more energy.”
Why a JV rather than a merger of telcos: “Mergers and acquisitions are not a priority in Spain and the regulatory risk is very high,” he said. Zegona has a greater motivation to make the RANco a reality. “Today there are three companies…that manage three national mobile networks with exactly the same fixed costs, but Orange and Telefónica have twice as many customers as us,” O’Hare explained. “Therefore, our national mobile network is inefficient. Just as our fixed infrastructure was inefficient and unprofitable, [and] that’s why we powered the fibercos.”
“It would be easier to broker a deal with MasOrange to share the network in certain areas, so the synergies would be in urban areas. But we don’t have anything with Telefónica, so there it would all be synergies.” Telefonica already has a mobile network sharing deal in place with Vodafone in sparsely populated areas, and was rumoured to be in talks with the telco on a broader RANco arrangement this time last year.
As a result, a partnership with Telefonica would bring greater synergies as there are no existing arrangements in place in the mobile space, but any deal would be a more difficult deal to hammer out and it would be trickier to bring in an investor, O’Hare added. Zegona has three priorities in Spain: to align its valuation with those of its competitors; to boost its cash flow to €1 billion; and to develop a RANco. “As long as we are in the middle of that transformation, we have no interest in mergers and acquisitions,” he said. And in addition, “the regulatory obstacle is…too big.”
“Historically, these small businesses have grown and then tried to sell themselves to MásMóvil. But MásMóvil no longer buys. Neither do we or Telefónica,” O’Hare said. “No one is buying. So they… will just be devoured by us and by Digi, as in the Pac-Man game.”
Would Huawei network equipment be used in the proposed Spanish RanCo? Vodafone is the mobile operator with the largest network provided by Huawei. Orange is reducing its share, and Telefónica only uses Huawei in part of its core network in Spain and not at all in its radio network. If the Brussels Cybersecurity Act mandates the replacement of this Chinese equipment, what will Vodafone Spain (Zegona) do?
“If Europe is more aggressive on the Huawei issue , I suppose we should accelerate efforts to reduce the amount of Huawei equipment in the network… should we accelerate RANco for this reason? Officially, the answer is no.”
……………………………………………………………………………………………………………….
References:
https://www.expansion.com/empresas/tecnologia/2026/01/26/6973ab17468aebd1418b4590.html
SNS Telecom & IT: Private 5G Market Nears Mainstream With $5 Billion Surge
España hit with major telecom blackout after power outage April 28th
Orange Spain & Ericsson to build 5G Infrastructure for 3 High-Speed Rail Lines
Telefónica and Nokia partner to boost use of 5G SA network APIs
Telefónica launches 5G SA in >700 towns and cities in Spain
Telefónica – Nokia alliance for private mobile networks to accelerate digital transformation for enterprises in Latin America
Ericsson and O2 Telefónica demo Europe’s 1st Cloud RAN 5G mmWave FWA use case
Telecom and AI Status in the EU
STL completes successful Multi-Core Fiber (MCF) trial with Colt in London, UK
India based STL, a global provider of optical and digital connectivity solutions for AI-era networks, has completed multi-core fiber (MCF) field trials with Colt Technology Services on Colt’s London metro optical network. The trial is a meaningful proof point for space-division multiplexing (SDM) in carrier environments, demonstrating that MCF can lift per-fiber strand capacity while staying within existing civil and duct constraints and improving overall network energy and cost metrics.
The deployment used STL’s Multiverse™ four-core MCF, designed with the same 125 µm cladding diameter as conventional single-mode fibre (SMF) and a 250/200 µm coating, enabling seamless handling with existing cable designs and installation practices. The trial route connected two Colt Points of Presence (PoPs) on the London metro network over spans of approximately 9 km and 63 km, representing both short-haul metro and longer metro-regional use cases.
From a transmission standpoint, the network achieved an 800 Gbps line rate with service validation for 100GE and 400GE, aligning with current high-capacity router and data-centre interconnect interfaces. STL and Colt validated performance across a broad set of optical and system parameters, including chromatic dispersion (CD), polarization mode dispersion (PMD), inter-core crosstalk, throughput, fault behavior, OTDR signatures, insertion loss, and optical return loss (ORL), with results within expected design envelopes. This indicates that Multiverse™ MCF can be engineered and operated to comparable performance baselines as legacy SMF while delivering higher spatial capacity.
Architecturally, STL’s MCF platform integrates four independent cores within a standard SMF cladding profile, effectively multiplying per-fibre capacity without increasing cable diameter. For operators, this directly addresses constraints in congested metro ducts, legacy civil infrastructure, and brownfield routes where augmenting capacity by pulling additional cables is either cost-prohibitive or operationally disruptive. In these scenarios, MCF creates a higher bit-per-mm² and bit-per-duct investment profile, improving both capex efficiency (less civil work, fewer ducts) and opex metrics such as energy per transported bit.
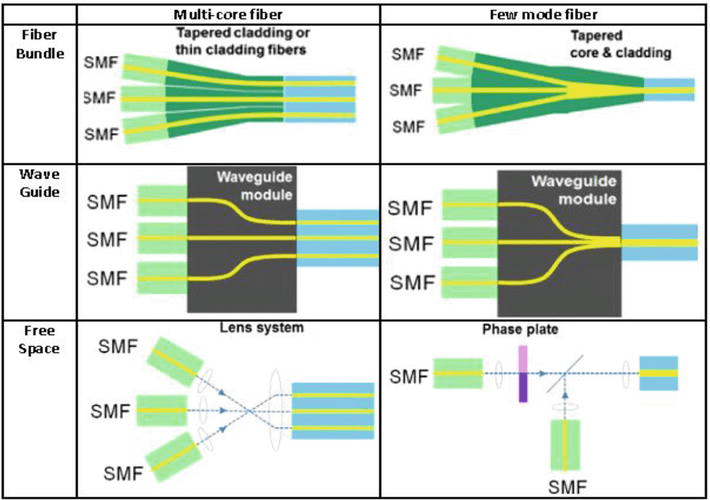
STL positions itself as one of the early movers in taking MCF from controlled lab demonstrations into operational networks, including buried and ducted plant, backed by a full ecosystem spanning fibre, cable, and connectivity hardware through its Optotec portfolio. Coupled with STL’s broader focus on AI-ready optical infrastructure and 5G-ready digital network solutions, the Colt trial underlines a practical migration path for carriers looking to future-proof metro and data-centre interconnect footprints against emerging AI, cloud, and 5G traffic patterns without wholesale rebuilds of underlying passive infrastructure.
“As network demand accelerates, customers are looking for more bandwidth without sacrificing security, performance, or sustainability,” said Buddy Bayer, Chief Operating Officer, Colt Technology Services. “At Colt, we continue to push optical networking forward, and this pilot represents an important step in Europe and the USA. It reflects our focus on building scalable networks that deliver growth in capacity without increasing environmental impact.”
Dr Badri Gomatam, CTO, STL, said the trial highlights the value of joint innovation in advancing optical infrastructure. “Collaborations like this speed up adoption of next-generation connectivity technologies. STL’s Multiverse MCF portfolio is designed for the high-density, ultra-low latency, and resilient connectivity requirements of AI, hyperscale cloud, and future digital platforms globally,” he said. STL stated that the trial results strengthen confidence in MCF as a viable technology for the growing bandwidth requirements driven by AI workloads, cloud scale-out, and new digital services.
“As network demand accelerates, customers are looking for more bandwidth without sacrificing security, performance, or sustainability,” said Buddy Bayer, Chief Operating Officer, Colt Technology Services. “At Colt, we continue to push optical networking forward, and this pilot represents an important step in Europe and the USA. It reflects our focus on building scalable networks that deliver growth in capacity without increasing environmental impact.”
Dr Badri Gomatam, CTO, STL, said the trial highlights the value of joint innovation in advancing optical infrastructure. “Collaborations like this speed up adoption of next-generation connectivity technologies. STL’s Multiverse MCF portfolio is designed for the high-density, ultra-low latency, and resilient connectivity requirements of AI, hyperscale cloud, and future digital platforms globally,” he said. STL stated that the trial results strengthen confidence in MCF as a viable technology for the growing bandwidth requirements driven by AI workloads, cloud scale-out, and new digital services.
………………………………………………………………………………………………………………………………………………………………….
About STL-– Sterlite Technologies Ltd:
STL is a global provider of advanced connectivity solutions, offering end-to-end products and services for building AI-ready networks across FTTx, rural broadband, enterprise, and data centres. With manufacturing operations in North America, Europe, and Asia, STL supplies connectivity solutions in more than 100 countries and works with telecom operators, cloud and data center companies, internet service providers, and large enterprises to build future-ready AI digital infrastructure.
On January 23, 2026, STL reported continued sequential improvement in Operational EBITDA margin for the fifth consecutive quarter, driven by a higher-margin product mix and increased contribution from the US market. With the US–India Bilateral Trade Agreement under advanced discussion, STL remains well-positioned to leverage emerging opportunities by offering reliable, high-quality solutions for building AI-ready digital infrastructure.
……………………………………………………………………………………………………………………………………………………
References:
https://www.intechopen.com/chapters/78908
How will fiber and equipment vendors meet the increased demand for fiber optics in 2026 due to AI data center buildouts?
Big tech spending on AI data centers and
AT&T sets 1.6 Tbps long distance speed record on its white box based fiber optic network
Huawei Cloud Review and Global Sales Partner Policies for 2026
Huawei Cloud is the cloud computing platform of Huawei Technologies Co. Ltd., offering a comprehensive suite of cloud services and solutions for enterprises and individual consumers. It’s ranked as the second-largest cloud service provider in China by market share, consistently placing behind the market leader, Alibaba Cloud.
Huawei Cloud provides a full range of services including Infrastructure as a Service (IaaS), Platform as a Service (PaaS), and Software as a Service (SaaS), supporting public, private, and hybrid cloud architectures. Cloud services include:
- Compute Services such as Elastic Cloud Servers (ECS), Bare Metal Servers (BMS), and container management via the Cloud Container Engine (CCE).
- Storage and Data Management Offerings include Object Storage Service (OBS), Elastic Volume Service (EVS), backup and disaster recovery solutions, and a range of database options like GaussDB and RDS for MySQL.
- Networking Services cover Virtual Private Cloud (VPC), Elastic IP (EIP), load balancing, and content delivery networks (CDN) to ensure fast and reliable connectivity.
- AI and Analytics This is a key focus area, featuring AI development platforms like ModelArts, pre-trained Pangu models, big data analytics services (MapReduce Service, Data Warehouse Service), and various AI-powered solutions for specific industries.
- Security and Compliance The platform offers robust security measures including firewalls, anti-DDoS services, data encryption, identity and access management (IAM), and comprehensive security operations centers.
- Developer and Management Tools A variety of tools for application development, operations management (O&M), migration, and governance.
Charles Yang, Huawei Senior Vice President, highlighted that the intelligent era presents immense opportunities and challenges for Huawei Cloud and its partners.
…………………………………………………………………………………………………………………………………………………….
- Global Visibility: Amplifying partner visibility through Huawei Cloud’s international media channels.
- Brand Enhancement: Assisting partners in improving their brand image using established global communication benchmarks.
- Enhanced Benefits: Upgrading partner benefits, including an increased Market Development Fund and comprehensive promotional support.
- Collaborative Marketing: Inviting partners to participate in Huawei Cloud’s own global marketing initiatives.
- Executive Level (CXO): Facilitating strategic exchanges on industry trends, digital transformation, and AI strategy to ensure vision alignment.
- Core Teams: Offering courses focused on business operations, industry analysis, and growth strategies.
- Sales and Technical Roles (BDs, SAs, CSMs): Providing hands-on training, including sales simulations and technical workshops, to enhance practical expertise.
References:
https://thetimes.com.au/news/press-releases?rkey=20260123AE69710&filter=24774
HUAWEI CLOUD launches partner programs in LatAm and Caribbean
Huawei’s Electric Vehicle Charging Technology & Top 10 Charging Trends
Huawei launches CloudMatrix 384 AI System to rival Nvidia’s most advanced AI system
Huawei to Double Output of Ascend AI chips in 2026; OpenAI orders HBM chips from SK Hynix & Samsung for Stargate UAE project
Omdia on resurgence of Huawei: #1 RAN vendor in 3 out of 5 regions; RAN market has bottomed
Blue Origin announces TeraWave – satellite internet rival for Starlink and Amazon Leo
The BBC reports that Jeff Bezos owned Blue Origin plans to create a new communications network called TeraWave, launching more than 5,400 satellites to offer global internet coverage. TeraWave will be focused on data centers, businesses and governments.
In a satellite internet market dominated by Elon Musk’s Starlink, Blue Origin would still have fewer satellites in orbit than Starlink. Yet TeraWave’s network at maximum speed would allow upload and download speeds of up to 6 terabits per second, much faster than rival commercial satellite offerings. The satellites are set to start launching by the end of 2027.
In April, Blue Origin launched an 11-minute space flight with an all-female crew, including Bezos’ now-wife Lauren Sánchez, singer Katie Perry and CBS presenter Gayle King. However, some commentators said it was “tone deaf” for celebrities to be taking part in such a fleeting and expensive trip at a time of economic struggle.
Blue Origin says TeraWave will be focused on data centers, businesses and governments. Blue Origin said its network, at its fastest, would allow upload and download speeds of as much as 6 terabits per second, much faster than rival commercial satellite services currently offer.
TeraWave is Optimized for Enterprise, Data Center, & Government Customers

- Starlink – part of Musk’s rocket firm SpaceX (which is 40% owned by Elon Musk) is by far the #1 satellite internet and phone service provider, primarily to individual customers.
- Blue Origin’s TeraWave satellite network will also compete with Amazon Leo, but they are targeting different market segments despite both being backed by Jeff Bezos. While it currently has around 180 satellites in orbit, having launched dozens more just last week, it plans to have more than 3,000 in orbit. Like Starlink, Amazon is also more focused on the general public than businesses and governments, positioning Leo as a way to offer high-speed internet access globally. It has not said when all of the Leo satellites will be in orbit.
| Feature | Blue Origin TeraWave | Amazon Leo (formerly Project Kuiper) |
|---|---|---|
| Target Market | Enterprises, data centers, governments, and other high-capacity users. | Consumers and communities in remote and underserved areas. |
| Service Goal | Provide extremely high-speed, symmetrical, and redundant backbone connectivity. | Deliver general high-speed broadband internet access (consumer speeds). |
| Projected Speeds | Up to 6 terabits per second (Tbps) via optical links in MEO. | Up to 1 gigabit per second (Gbps) for its highest-end user terminal. |
| Constellation Size | Plan for 5,408 satellites (LEO and MEO). | Plan for over 3,200 satellites (LEO only). |
In November, Blue Origin successfully landed a rocket booster on a floating platform for the first time. Only SpaceX had previously accomplished that feat.
………………………………………………………………………………………………………………………………………………………………..
References:
https://www.bbc.com/news/articles/cn0yydwe89jo
AST SpaceMobile to deliver U.S. nationwide LEO satellite services in 2026
FCC grants Amazon’s Kuiper license for NGSO satellite constellation for internet services
Amazon to Spend Billions on 38 Space Launches for Project Kuiper
Starlink doubles subscriber base; expands to to 42 new countries, territories & markets
China ITU filing to put ~200K satellites in low earth orbit while FCC authorizes 7.5K additional Starlink LEO satellites
Amazon Leo (formerly Project Kuiper) unveils satellite broadband for enterprises; Competitive analysis with Starlink
Amazon launches first Project Kuiper satellites in direct competition with SpaceX/Starlink
NBN selects Amazon Project Kuiper over Starlink for LEO satellite internet service in Australia
Elon Musk: Starlink could become a global mobile carrier; 2 year timeframe for new smartphones
GEO satellite internet from HughesNet and Viasat can’t compete with LEO Starlink in speed or latency
Ericsson announces capability for 5G Advanced location based services in Q1-2026
Ericsson’s 5G Advanced location based services (LBS) offering is a comprehensive suite of innovations designed to redefine location-based services across commercial 5G Standalone (SA) networks. Set for release in Q1 2026, it makes Ericsson the leader in 5G positioning technology, offering a scalable and fully integrated solution on top of Ericsson’s dual-mode 5G Core network.
By embedding positioning as a core 5G SA network capability, Ericsson 5G Advanced location services enables Communications Service Providers (CSPs) to monetize precise location services and expand beyond traditional mobile offerings into verticals such as manufacturing, healthcare, public safety, automotive, drones, and more.
Key benefits:
- High Accuracy: Down to sub-meter for indoor and sub-10 cm for outdoor positioning, enabling precise tracking
- Scalability: Scalable, precise positioning for outdoor applications (automotive, agriculture, drones)
- Seamless Indoor/Outdoor Coverage: Unified 5G positioning technology for both environments.
- Developer & Device Friendliness: No need for device-side apps; improved battery life compared to satellite-based solutions
- Support for Large-Scale Use Cases: Enables massive geofencing, population density analysis, and tracking use cases.
Monica Zethzon, Head of Core Networks, Ericsson, says: “With the launch of 5G Advanced Location Services we are evolving the value of 5G Standalone networks. This innovation gives CSPs the precision and scalability to create differentiated services based on location capabilities.”
Caroline Gabriel, Partner at Analysys Mason, says: “Ericsson’s integrated approach to indoor and outdoor positioning sets a new benchmark in the industry. It addresses critical pain points for operators and enterprises, particularly in sectors where location accuracy is mission-critical.”
The global market for 5G positioning is in its early stages but poised for rapid growth, driven by demand for enhanced precision in diverse sectors. Ericsson’s solution responds to this demand with scalable, developer-friendly capabilities that improve device battery life compared to legacy systems.
This launch further strengthens Ericsson’s location solutions based on Real-Time Kinematics technology, with related devices from Ericsson planned for Q1 2026.

Photo Credit: Ericsson
………………………………………………………………………………………………………………………………………………………….
- Integrated Positioning: Positioning is built into the 5G Standalone (SA) architecture, moving beyond traditional GPS reliance.
- High Accuracy & Efficiency: New techniques improve accuracy (e.g., bandwidth aggregation, carrier-phase measurements) and reduce power consumption for devices.
- AI/ML Integration: Artificial Intelligence/Machine Learning is applied to enhance positioning accuracy, especially for challenging scenarios like beyond-visual-line-of-sight (BVLOS).
- Support for New Devices/Apps: Enables precise tracking for wearables, industrial sensors (RedCap), augmented reality (AR), drone control, and smart grids.
- Beyond-Line-of-Sight (BVLOS): Focus on reliable positioning for industrial and public safety applications where line-of-sight isn’t guaranteed.
- Reduced Power: Solutions target lower power usage, crucial for IoT devices.
- Release 18 (5G Advanced Start): Finalized mid-2024, introduced major LBS enhancements, including RedCap positioning, bandwidth aggregation, and carrier-phase support.
- Release 19 (Ongoing): Continues the evolution, extending LTM (L1/L2-triggered Mobility) and further exploring AI/ML for mobility and positioning.
- Release 20 & Beyond: Will build on these foundations, further evolving towards 6G capabilities.
References:
https://www.ericsson.com/en/press-releases/2026/1/5g-advanced-location-services
5G Advanced offers opportunities for new revenue streams; 3GPP specs for 5G FWA?
What is 5G Advanced and is it ready for deployment any time soon?
Hutchison Telecom is deploying 5G-Advanced in Hong Kong without 5G-A endpoints
China Mobile & ZTE use digital twin technology with 5G-Advanced on high-speed railway in China
Huawei pushes 5.5G (aka 5G Advanced) but there are no completed 3GPP specs or ITU-R standards!
ZTE and China Telecom unveil 5G-Advanced solution for B2B and B2C services
India 5G subscribers top 400 Million with rapid adoption continuing without 5Gi
With over 400 million 5G subscribers, India now ranks #2 globally (China is #1 [1.]). What’s even more remarkable is the speed of adoption after 5G spectrum auctions were repeatedly delayed. Jyotiraditya Scindia, India’s union minister for communications and development of the North Eastern Region, said the country is “setting new global benchmarks in scale, speed and digital transformation.”
According to figures cited by the minister, the country’s 5G subscriber base now exceeds that of other major markets, including the United States with around 350 million users, the European Union with 200 million, and Japan with 190 million. China remains the global leader, with more than 1.2 billion 5G connections.
Note 1. China has over 1.2 billion 5G subscribers as of late 2025, representing over 60% of all mobile connections in the country, driven by massive infrastructure rollout and strong adoption across major operators like China Mobile, China Telecom, and China Unicom, making it the global leader in 5G penetration.
……………………………………………………………………………………………………………………………………………………………………………………………………..
Bharti Airtel and Reliance Jio Infocomm spearheaded the launch, becoming the first carriers to operationalize 5G networks and achieving significant subscriber acquisition, with each surpassing the 50 million user milestone within their initial year of service [1]. Vodafone Idea subsequently entered the 5G market with launches in specific cities during 2025.
State-owned telecom provider BSNL is projected to launch 5G services within the current year [1]. This deployment is slated to exclusively utilize India’s indigenously developed telecom technology stack, a collaborative effort involving the Centre for Development of Telematics (C-DOT), Tejas Networks, and Tata Consultancy Services (TCS).
As of the close of 2025, the national 5G infrastructure comprised 518,854 operational base stations, marking a substantial increase from approximately 464,990 recorded at the start of the year [1]. The Department of Telecommunications (DoT) reported the deployment of 4,112 new 5G base transceiver stations (BTS) in December 2025 alone, contributing to the year-end cumulative total

- Infrastructure Growth: Rapid BTS deployment, exceeding 4,100 new installations in December 2025 alone, demonstrates intense network densification, with coverage now reaching most districts.
- Vodafone Idea’s Entry: Vi, after initial delays, commenced its phased 5G service introduction in select cities during 2025.
- BSNL’s Indigenous Strategy: The state-owned operator is slated to launch 5G using India’s homegrown stack (C-DOT, Tejas, TCS), showcasing self-reliance in telecom technology.
- Market Dynamics: The rapid expansion aims to unlock enterprise and consumer use cases, positioning India as a significant global 5G player, despite ongoing discussions about monetization and infrastructure investment.
Technical & Deployment Highlights:
- Architecture: A mix of 5G SA (Jio) and 5G NSA (Airtel) is prevalent, with SA offering lower latency and true 5G capabilities.
- Spectrum: Operators utilize various bands, including sub-6 GHz (3.3 GHz, 26 GHz) for broad coverage and capacity.
- Deployment Pace: Driven by ministerial targets, operators installed BTS at an accelerated pace, focusing initially on high-revenue urban centers.
This author deeply regrets that the Telecommunications Standards Development Society India (TSDSI)’s 5Gi RIT specification, included as part of the ITU-R M.2150 IMT 2020 RIT/SRIT standard, was not implemented in India. On January 25, 2022, TSDSI told the Telecommunication Engineering Center (TEC) under the DoT not to proceed with the adoption of 5Gi as a national 5G standard. TSDSI added that it “does not intend to further update 5Gi specifications.”
References:
OpenSignal: real world 5G deployment in India, market status & what happened to 5Gi?
Nokia Executive: India to Have Fastest 5G Rollout in the World; 5Gi/LMLC Missing!
LightCounting & TÉRAL RESEARCH: India RAN market is buoyant with 5G rolling out at a fast pace
Nokia’s Bell Labs to use adapted 4G and 5G access technologies for Indian space missions
Reliance Jio in talks with Tesla to deploy private 5G network for the latter’s manufacturing plant in India
Communications Minister: India to be major telecom technology exporter in 3 years with its 4G/5G technology stack
India to set up 100 labs for developing 5G apps, business models and use-cases
Adani Group to launch private 5G network services in India this year
Adani Group planning to enter India’s long delayed 5G spectrum auction
At long last: India enters 5G era as carriers spend $ billions but don’t support 5Gi
5G in India to be launched in 2023; air traffic safety a concern; 5G for agricultural monitoring to be very useful
Bharti Airtel to launch 5G services in India this August; Reliance Jio to follow
5G Made in India: Bharti Airtel and Tata Group partner to implement 5G in India
India government wants “home-grown” 5G; BSNL and MTNL will emerge as healthy
5G in India dependent on fiber backhaul investments
Hindu businessline: Indian telcos deployed 33,000 5G base stations in 2022
Huawei’s Electric Vehicle Charging Technology & Top 10 Charging Trends
Huawei EV Charging Backgrounder –from Google Gemini:

- Ultra-Fast Charging Technology: Huawei’s flagship product is the FusionCharge system, which uses a fully liquid-cooled design to enable ultra-fast DC charging at high power levels, including up to 600 kW and even experimental 1.5 MW chargers. This technology is designed to add significant range (e.g., over 200 km in 5 minutes) and is compatible with most EV models.
- Integrated Energy Solutions: A core part of their strategy is the integration of EV charging with renewable energy (photovoltaics or PV) and energy storage systems (ESS). This “PV+ESS+Charger” solution helps maximize green power consumption, reduces the impact of high-power charging on the main power grid, and allows for intelligent peak shaving to optimize operational costs.
- Hardware and Components: Huawei designs and supplies key charging components, including power units, charging dispensers, and silicon carbide (SiC) chips that enhance efficiency and power density. Their modular designs allow for scalable power output and a service life of over 10 years.
- Smart Network Management: Huawei provides platforms for smart charging network management that enable remote monitoring, data analysis, and intelligent power distribution among multiple vehicles at a single station. This intelligent power pooling improves efficiency and ensures optimal use of available power.
- Innovation in Convenience: Huawei has showcased an experimental prototype of a robotic charging arm that can automatically locate and plug into a vehicle’s charging port, facilitating a seamless “self-charging” experience that would work well with autonomous vehicles.
- Strategic Partnerships and Market Deployment: Huawei works with partners, including logistics companies and car manufacturers, to deploy its charging solutions across China and other markets. They are also involved in joint ventures for manufacturing EVs, such as with Chery under the Harmony Intelligent Mobility Alliance (HIMA).
- Battery Technology Research: The company holds patents for advanced battery technology, including a solid-state battery with a high energy density, which could further revolutionize EV range and charging times if commercialized.
………………………………………………………………………………………………………………………………………………………………………………….
Here are Huawei’s top 10 trends in charging systems for electric vehicles:
- From passenger vehicles to commercial vehicles, “high quality” has become a must for ultra-fast charging infrastructure, driving large-scale upgrade of legacy charging devices to meet the energy needs of different vehicle models. High-quality development will extend from “cities of ultra-fast charging” to “cities of megawatt charging” through unified planning, standards, supervision, and O&M, enabling industry partners to turn high quality into high returns.
- Ultra-fast-charging vehicle models, once premium necessities, will be embraced by everyone. The extensive application of third-generation power semiconductor materials and high-C-rate traction batteries will further increase the market share of ultra-fast-charging vehicles. Megawatt-charging commercial vehicles will dominate the market.
- Megawatt-Scale Logistics Electrification: “Fuel-to-electricity” conversion for viable business will rapidly expand Heavy Goods Vehicle (HGV) from limited, closed applications to widespread, all-scenario adoption. The cost reduction of traction batteries and the innovation of megawatt charging technologies will make megawatt-scale logistics electrification an unstoppable trend, bringing significant economic and social values.
- 100 Megawatt Scale Charging Stations: For electrified logistics, 100 MW-scale charging stations will become the essential infrastructure for high-throughput operations. Factors such as technical strengths, competitive electricity pricing, and scalable deployment will unlock powerful cluster effects and secure long-term, sustainable profitability for charging station investments.
- Security and Trustworthiness: Compared with passenger vehicles, commercial vehicles require higher charging power and a greater proportion of energy storage system (ESS) capacity in charging stations. Therefore, security and trustworthiness will become fundamental requirements for charging networks. The comprehensive electrical safety protection architecture will seamlessly safeguard people, vehicles, and chargers, reinforced by a robust cybersecurity foundation.
- Liquid-cooled ultra-fast charging delivers superior heat dissipation and protection, enabling reliable performance across increasingly distributed charging scenarios. In contrast, conventional air-cooled systems struggle in demanding environments such as high heat, humidity, salt fog, and heavy dust. In the future, the liquid cooling technology will be applied in vehicles and chargers, enabling efficient megawatt charging and contributing to overall vehicle cost reduction.
- A DC-based ESS+charger system can effectively increase power capacity, helping customers quickly and cost-effectively deploy ultra-fast charging stations, even in locations with limited grid power. This system is ideal for upgrading legacy low-capacity stations, enabling ultra-fast charging stations to be rapidly repurposed or newly deployed with minimal grid power, and maximizing the capability to meet vehicle charging demands.
- Modular Station Construction: The station-level modular solution is built for engineering construction and device commissioning, adapting to a wide range of charging scenarios. Its low cost, rapid deployment, and easy relocation make it a flexible choice, while its durable design ensures long-term value and protection for investors.
- Campus Microgrid: The grid-forming PV+ESS system integrates the liquid-cooled ultra-fast charging technology, and can operate in on-grid or off-grid mode. This forms a one-stop “PV+ESS+charger+vehicle+network” solution that boosts power capacity, maximizes the use of green energy, and enhances revenue through time-of-use arbitrage.
- AI Empowerment: The intelligent evolution of charging networks will enable seamless collaboration across networks, stations, chargers, and vehicles. By breaking down digital silos, it will elevate the end-to-end charging experience for vehicle owners and enhance overall logistics and transportation efficiency.
Huawei says they will continue to work with partners to accelerate the rollout of seamless, high-quality ultra-fast charging networks, and capture opportunities of mobility electrification.
SOURCE Huawei Digital Power
………………………………………………………………………………………………………………………………………………………………………………………………………………
https://interestingengineering.com/energy/china-huawei-worlds-first-100mw-charging
Agentic AI and the Future of Communications for Autonomous Vehicles (V2X)
Private 5G networks move to include automation, autonomous systems, edge computing & AI operations
Telecom operators investing in Agentic AI while Self Organizing Network AI market set for rapid growth
Arm Holdings unveils “Physical AI” business unit to focus on robotics and automotive
2025 Year End Review: Integration of Telecom and ICT; What to Expect in 2026
Fiber Optic Networks & Subsea Cable Systems as the foundation for AI and Cloud services
Introduction:
A foundational enabler of global AI infrastructure and cloud service expansion are the fiber-optic networks interconnecting data centers worldwide. These high-capacity optical systems form the invisible backbone of modern digital society, facilitating everything from real-time financial transactions and mission-critical enterprise traffic to defense systems, entertainment, and personal communications. Access to cloud-based AI platforms—and the data-driven intelligence they deliver—depends on efficient, low-latency connectivity to data centers. As AI workloads proliferate across industries and continents, the unifying role of optical fiber becomes paramount, ensuring equitable global access to advanced digital capabilities.
A core prerequisite for scaling AI and cloud services is the mesh of high-capacity fiber-optic networks that interconnect data centers globally. These networks silently underpin digital society, carrying the data that powers financial markets, mission-critical enterprise applications, national security, entertainment platforms, and everyday human communication.
Cloud-based AI services only become meaningful when users, enterprises, and machines can reach them with low latency, high reliability, and predictable performance. In this context, the unifying role of fiber is increasingly strategic, as it determines who can participate in the AI economy and at what scale.
Subsea (fiber) cable systems as digital unifier:
The massive capacity and spectral efficiency of optical fiber have driven its deployment from access networks to backbone routes and across the world’s oceans. Today, more than 570 subsea cables carry over 99% of international traffic, effectively stitching together a single global fabric for AI and cloud connectivity.
New subsea systems highlight how infrastructure investments are closing regional gaps rather than just adding raw terabits: the Medusa submarine cable system will help narrow the digital divide between Europe and North Africa, the Bangladesh Private Cable System (BPCS) will establish the country’s first private subsea on-ramps to global cloud and AI ecosystems, and a new Jakarta–Singapore route by PT Solusi Sinergi Digital Tbk (Surge) is set to increase data center interconnectivity while expanding affordable broadband to tens of millions of Indonesians.
As multiple new subsea cable system build outs enter planning and deployment, global bandwidth growth is expected to remain strong, extending the reach of AI and cloud platforms to more geographies, users, and industries.
From PoPs to data centers:
The traffic matrix of the AI era looks very different from that of legacy telecom networks. Instead of primarily connecting PoPs, carrier hotels, and central offices, modern optical networks are being engineered around dense, high-capacity flows between data centers.
More than 11,000 data centers, including over one thousand hyperscale facilities, now form the core nodes of the global digital infrastructure, generating on the order of thousands of petabytes of WAN traffic daily. Subsea bandwidth demand is expected to grow at roughly 30% per year as AI and cloud services scale, placing new design pressure on how subsea and terrestrial backhaul networks are engineered end-to-end.
Unifying subsea and terrestrial backhaul:
This shift is driving a deliberate architectural pivot: instead of treating subsea and terrestrial backhaul as separate domains, leading operators and cloud providers are moving toward unified, end-to-end design philosophies. Traffic no longer “terminates” at a cable landing station or central office; it flows optically and logically from data center to data center across continents.
By optimizing subsea and terrestrial segments as a single system, operators can simplify their networks, reduce CapEx and OpEx, and unlock higher effective capacity. Approaches such as optical pass-through at cable landing sites reduce cost, footprint, and power, while spectrum expansion into C+L bands can deliver a twofold or greater increase in per-fiber capacity, significantly lowering the cost of backhauling subsea traffic to inland data centers.
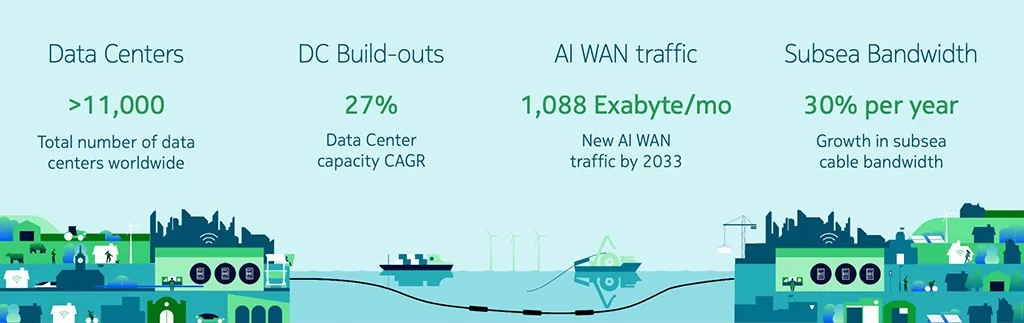
An ever-increasing number of data centers powering AI services is driving significant bandwidth growth over subsea fiber optic cables. Image Credit: Nokia
Unified optical platforms for the AI supercycle:
Realizing this vision at scale requires platforms that unify roles traditionally split across multiple, specialized systems. For Nokia’s customers, this means leveraging the 1830 Global Express (GX) compact modular portfolio as a single, DCI-optimized solution for transponders, open optical line systems (OLS), and submarine line terminal equipment (SLTE) across both subsea and terrestrial applications.
High-performance coherent transponders on the 1830 GX support 800 Gigabit Ethernet across trans-oceanic distances, using techniques such as Probabilistic Constellation Shaping, Nyquist filtering, and continuous baud rate tuning to push performance toward the Shannon limit. The integrated OLS delivers the full suite of SLTE capabilities, including ROADM-based wavelength switching and spectrum management, ASE or CW idler insertion, and optical channel monitoring, while C+L operation on terrestrial backhaul provides step-function increases in capacity per fiber and reduces the cost of leased backhaul infrastructure.
Photo Credit: Nokia
Operational simplicity and resilience:
Beyond raw capacity, unified platforms enable operators to rationalize operations. Using a common hardware and software stack across subsea and terrestrial domains simplifies planning, training, sparing, deployment, and lifecycle management.
Capabilities such as constant-power ILAs for stable end-to-end DC-to-DC transport, integrated OTDR for proactive fiber monitoring and fault localization, and a rich set of optical protection schemes for service protection and restoration help operators build networks that are not only faster and denser, but also more resilient and easier to run.
What’s next: pluggables and sensing:
The industry is now entering a phase where innovation in optics is tightly coupled to AI and automation. At PTC 2026 in Honolulu, discussions will highlight how pluggable coherent optics and fiber sensing are being introduced into subsea environments to further collapse layers and enhance awareness.
ICE-X 800G coherent pluggables are already enabling 400G, 600G, and 800G per wavelength over regional subsea spans exceeding 4,000 km, and future advances in chromatic dispersion tolerance are expected to extend the thin transponder layer paradigm to trans-Atlantic routes. In parallel, operators are exploring fiber sensing, powered by machine learning and advanced coherent techniques, to transform existing fiber assets into distributed sensors capable of supporting security, integrity monitoring, and new data-driven services.
Connectivity for all:
“Advancing connectivity for the AI supercycle” is more than a tagline; it captures two simultaneous imperatives: scaling networks for performance, efficiency, and sustainability while extending those networks to every region and community. As described herein, fiber optics connectivity is becoming the strategic control point for value creation in the age of large-scale AI.
Nokia’s Role in Subsea Fiber Optic Networks:
Nokia has invested for more than 15 years in helping subsea operators and their customers design, deploy, and operate end-to-end SLTE and terrestrial optical networks, backed by global services and multi-country program support. Following its unification with Infinera, Nokia has emerged as the number-two global vendor of subsea optical transport equipment, earning the confidence of a large majority of operators involved in the latest wave of Asia-Pacific subsea builds. These partnerships position Nokia to help the industry scale and unify networks for the AI supercycle—and to ensure that the benefits of AI-era connectivity reach as many people, countries, and enterprises as possible.
Nokia’s 1830 Global Express (GX) supports high-performance coherent transponders for transmission of high-speed data connections such as 800 Gigabit Ethernet (800GE) across trans-oceanic distances, leveraging features such as Probabilistic Constellation Shaping (PCS), Nyquist filtering and continuous baud rate adjustment to maximize optical reach and fiber capacity up to the Shannon Limit. The 1830 GX OLS supports all needed SLTE functions including ROADM-based wavelength switching and spectrum management, insertion of ASE spectrum or continuous-wave (CW) idler channels, and optical channel monitor.
……………………………………………………………………………………………………………………..
References:
https://www.nokia.com/blog/the-unifying-role-of-subsea-fiber-networks/
https://www.nokia.com/optical-networks/1830-global-express/
Subsea cable systems: the new high-capacity, high-resilience backbone of the AI-driven global network
FCC updates subsea cable regulations; repeals 98 “outdated” broadcast rules and regulations
Automating Fiber Testing in the Last Mile: An Experiment from the Field
Virtual RAN gets a boost from Samsung demo using Intel’s Grand Rapids/Xeon Series 6 SoC
Samsung is the fifth largest worldwide RAN equipment vendor, behind Huawei, Ericsson, Nokia and ZTE. This week, the South Korean conglomerate claimed to have reached a virtual RAN (vRAN) milestone with the completion of a commercial phone call using Granite Rapids – Intel’s Xeon 6700P-B SoC processor series. The call took place on the network of a large, undisclosed U.S. network operator, but apparently Verizon. Samsung said, “this builds upon the company’s previous achievement in 2024, when it completed the industry-first end-to-end call in a lab environment with Intel Xeon 6 SoC.”
Samsung’s cloud-native vRAN with Intel’s latest Xeon SoC ran on a single commercial off-the-shelf (COTS) server from Hewlett Packard Enterprise with a cloud platform from Wind River. This milestone, coming only a few months after the first wave of Intel Xeon 6 SoC was made commercially available, presents an innovative pathway for single-server vRAN deployments for next-generation networks.
The commercial readiness of vRAN technology promises to give network operators the ability to run RAN and AI workloads on fewer, more powerful servers.
Samsung wrote: “As operators accelerate their transition to software-driven, flexible architectures while seeking more sustainable infrastructure, the ability to run RAN and AI workloads on fewer, more powerful servers becomes critical, On a single server of Samsung’s AI-powered vRAN with enhanced processors, operators can consolidate software-driven network elements such as mobile core, radio access, transport and security, which traditionally required multiple servers, significantly simplifying the management of complex site configuration.”
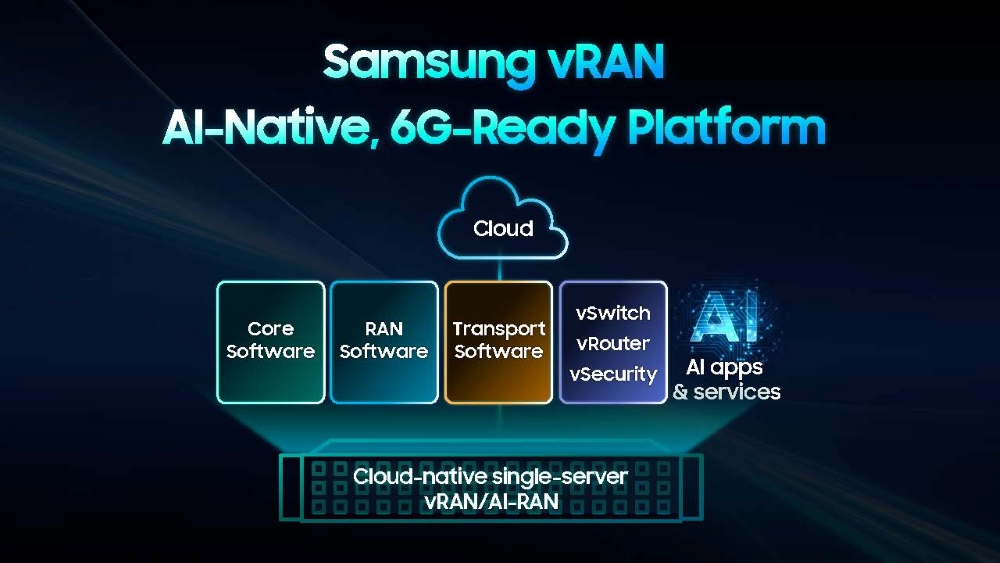
Image Credit: Samsung
“This breakthrough represents a major leap forward in network virtualization and efficiency. It confirms the real-world readiness of this latest technology under live network conditions, demonstrating that single-server vRAN deployments can meet the stringent performance and reliability standards required by leading carriers,” said June Moon, Executive Vice President, Head of R&D, Networks Business at Samsung Electronics. “We are not only deploying more sustainable, cost-effective networks, but also laying the foundation to fully utilize AI capabilities more easily and prepare for 6G with our end-to-end software-driven network solutions.”
Samsung’s vRAN leverages the latest Intel Xeon 6 SoC with Intel Advanced Matrix Extensions (Intel AMX), Intel vRAN Boost and up to 72 cores, delivering significant improvements in AI processing, memory bandwidth and energy efficiency compared to the previous generation.
“With Intel Xeon 6 SoC, featuring higher core counts and built-in acceleration for AI and vRAN, operators get the compute foundation for AI native, future ready networks,” said Cristina Rodriguez, VP and GM, Network & Edge, Intel. “This collaborative achievement with Samsung, HPE and Wind River enables greater consolidation of RAN and AI workloads, lowering power and total cost while speeding innovation.”
Samsung has been leading the deployment of vRAN solutions with major network operators worldwide and has achieved many industry breakthroughs, including the industry’s first call on a commercial network and large-scale deployments utilizing Intel Xeon processors with Intel vRAN Boost. The company continues to push the boundaries of network virtualization, working closely with ecosystem partners like Intel to deliver solutions that help operators build networks that are more efficient and sustainable.
“This successful first call is an important milestone for the industry,” said Daryl Schoolar, Analyst and Director at Recon Analytics. “By demonstrating multiple network functions running on next-generation processing technology, Samsung is showing what future networks look like — more cloud-native, more scalable and significantly more efficient. This achievement moves the industry beyond theoretical performance gains and into practical, deployable innovation that operators around the world can leverage to modernize their networks, accelerate automation and better support AI-driven use cases.”
“With Samsung’s vRAN and Intel’s Xeon 6 SoC running on a single server, Samsung expects enhanced cost savings for operators,” said a Samsung spokesperson via email to Light Reading, when asked what cost impact Granite Rapids would have. “The ability to consolidate multiple network functions including RAN, core, transport and security onto a single, high-performance COTS server reduces hardware footprint, simplifies site design and lowers power consumption.”
Vodafone is one Samsung customer that now expects to benefit from the availability of Granite Rapids. In November, Paco Pignatelli, Vodafone’s head of open RAN, told Light Reading that the new Intel platform offers “much better capacity and efficiency” than its predecessors. That was several weeks after the telco had announced plans to deploy Samsung’s virtual RAN technology in Germany and other European markets, starting in 2026.
…………………………………………………………………………………………………………………………………….
vRAN Market Assessment:
Virtual RAN still accounts for a very small share of the entire market. In 2023, data from Omdia put its market share at just 3% of the total RAN market which generates If vRAN is considered as part of the subsector for baseband RAN, its share was about 10% that year, implying baseband represents about 30% of the total expenditure on RAN products.
Hardware still dominates the RAN equipment business, but there is a rapid shift toward Commercial Off-The-Shelf (COTS) servers, particularly those using Intel’s Xeon 6 processors. Regional Dominance: North America and Asia-Pacific are expected to remain the largest markets in 2026, together accounting for over 70% of global vRAN revenue
- Dell’Oro Group:
- 2026 Stability: Predicts overall RAN revenues will remain “mostly stable” in 2026, but identifies AI-RAN, Cloud RAN, and Open RAN as favorable growth segments within that flat topline.
- Market Share: Expects vRAN to account for 5% to 10% of the total RAN market by 2026.
- Private Wireless: Forecasts that private wireless campus network RAN revenue will surpass USD 1 billion in 2026.
- Omdia:
- Growth Surge: Anticipates a doubling of vRAN’s market share by 2028. Specifically, it expects Open vRAN to reach a 16% share of the total RAN market in 2026, up from 7% in 2022.
- Automation Focus: Forecasts the Service Management and Orchestration (SMO) category to grow at a massive 99% CAGR through 2030 as operators align with O-RAN architectures.
- Research and Markets:
- Estimates the global Open RAN market size will reach between USD 5.0 billion and USD 10.0 billion by 2026, driven by aggressive greenfield deployments.
…………………………………………………………………………………………………………………………
References:
https://www.lightreading.com/5g/intel-and-samsung-add-to-pressure-on-purpose-built-5g
vRAN market disappoints – just like OpenRAN and mobile 5G
RAN silicon rethink – from purpose built products & ASICs to general purpose processors or GPUs for vRAN & AI RAN
LightCounting: Open RAN/vRAN market is pausing and regrouping
Dell’Oro: Private 5G ecosystem is evolving; vRAN gaining momentum; skepticism increasing
Heavy Reading: How network operators will deploy Open RAN and cloud native vRAN